INSTITUTIONAL · CHECKED 10 OCT 2026
CMB International review.
Hong Kong brokerage arm of China Merchants Bank, licensed across four entities by the SFC
RISKY
OUT OF 10
CMB International is the Hong Kong brokerage arm of China Merchants Bank, operating through four entities that each hold an active SFC licence, including confirmed registrations for CMB International Securities Limited and CMB International Futures Limited (licence ACQ651). None of the entities carry public disciplinary action, but the firm publishes no cost of trading, leaving pricing unclear before signing up.
Each criterion is scored 1 to 10 from primary sources. The overall score is their unweighted mean. How scoring works.
| Founded | 2010 |
|---|---|
| Headquarters | HK |
| Minimum deposit | Not stated |
| Account opening | 1-3 |
- Four entities hold active Hong Kong SFC licences, no disciplinary action on record
- CMB International Securities Limited's SFC licence is confirmed on the register
- CMB International Futures Limited holds SFC licence ACQ651, confirmed on register
- Ownership chain runs cleanly up to listed parent China Merchants Bank
- Offers professional platform connectivity via SP Trader and Multicharts
- Reachable by a published phone number
- No published cost of trading found on the broker's pages or documents
- Blended rating of 3.51 stars from just 47 reviews
- SFC compensation scheme caps payouts at 500,000 HKD
- SFC adjudicator process binds the firm but charges the claimant to use it
- Leverage on major FX pairs capped at 20:1 under SFC rules
- No negative balance protection required under the regulatory regime
Overview
TrueBroker is a free broker safety checker, and this page is our review of CMB International, scored 5 out of 10 across regulation, fees, platform, support and reviews. Our previous review of this firm scored it 4 out of 10; this review restates the score from current evidence, and the movement reflects our updated assessment against the current criteria rather than any change at the firm itself.
CMB International is the international arm of China Merchants Bank Co., Ltd., the parent bank founded in 1987 in Shenzhen and listed on the Shanghai and Hong Kong exchanges. The Hong Kong operating entity, CMB International Capital Corporation Limited (招银国际金融有限公司), is a wholly-owned subsidiary of that bank. The group’s business is split across four separately licensed subsidiaries: CMB International Securities Limited, CMB International Futures Limited, CMB International Capital Limited, and CMB International Asset Management Limited, each carrying different Hong Kong Search by Name portal licence types for different lines of business. Which of these a client actually contracts with, and what protections apply, depends on which subsidiary onboards them.
What the Hong Kong SFC register shows for CMB International
We searched the SFC Public Register of Licensed Persons and Registered Institutions directly. CMB International Securities Limited holds CE reference AUZ441, licensed for Type 1 and Type 4 (Dealing in Securities; Advising on Securities), both shown as active, with 6 licensing conditions attached and no public disciplinary action recorded. CMB International Futures Limited holds CE reference ACQ651, licensed for Type 2 (Dealing in Futures Contracts), active, with no public disciplinary action recorded. CMB International Capital Limited holds CE reference AVM940, licensed for Type 1 and Type 6 (Dealing in Securities; Advising on Corporate Finance), active, carrying 2 licensing conditions, with no public disciplinary action recorded. CMB International Asset Management Limited holds CE reference AVA101, licensed for Type 1, Type 4 and Type 9 (Dealing in Securities; Advising on Securities; Asset Management), active, carrying 3 licensing conditions, with no public disciplinary action recorded. Before running these checks we tested the SFC register against a firm known to be listed, so that a clean result reflects an actual absence of findings rather than a broken search.
Our earlier review also referred to a “Money Lenders License,” an “HKMA Registration for banking-related services,” a “CSRC RQFII qualification,” and “Stock Connect program licenses.” None of these came with a licence number or, in most cases, a named entity, and we hold no register entry for any of the authorities as described, so none of the four could be checked against a public record. That is a gap in what was published or in what we read, not a finding about the firm one way or the other.
We also searched 1,441 warning-list entries mirrored from CySEC, the FCA and the Mauritius FSC, and CMB International appears on none of them. That covers only the regulators we mirror, not every warning list in existence, but it is a clean result on the lists we checked.
What CMB International’s own site would not give us
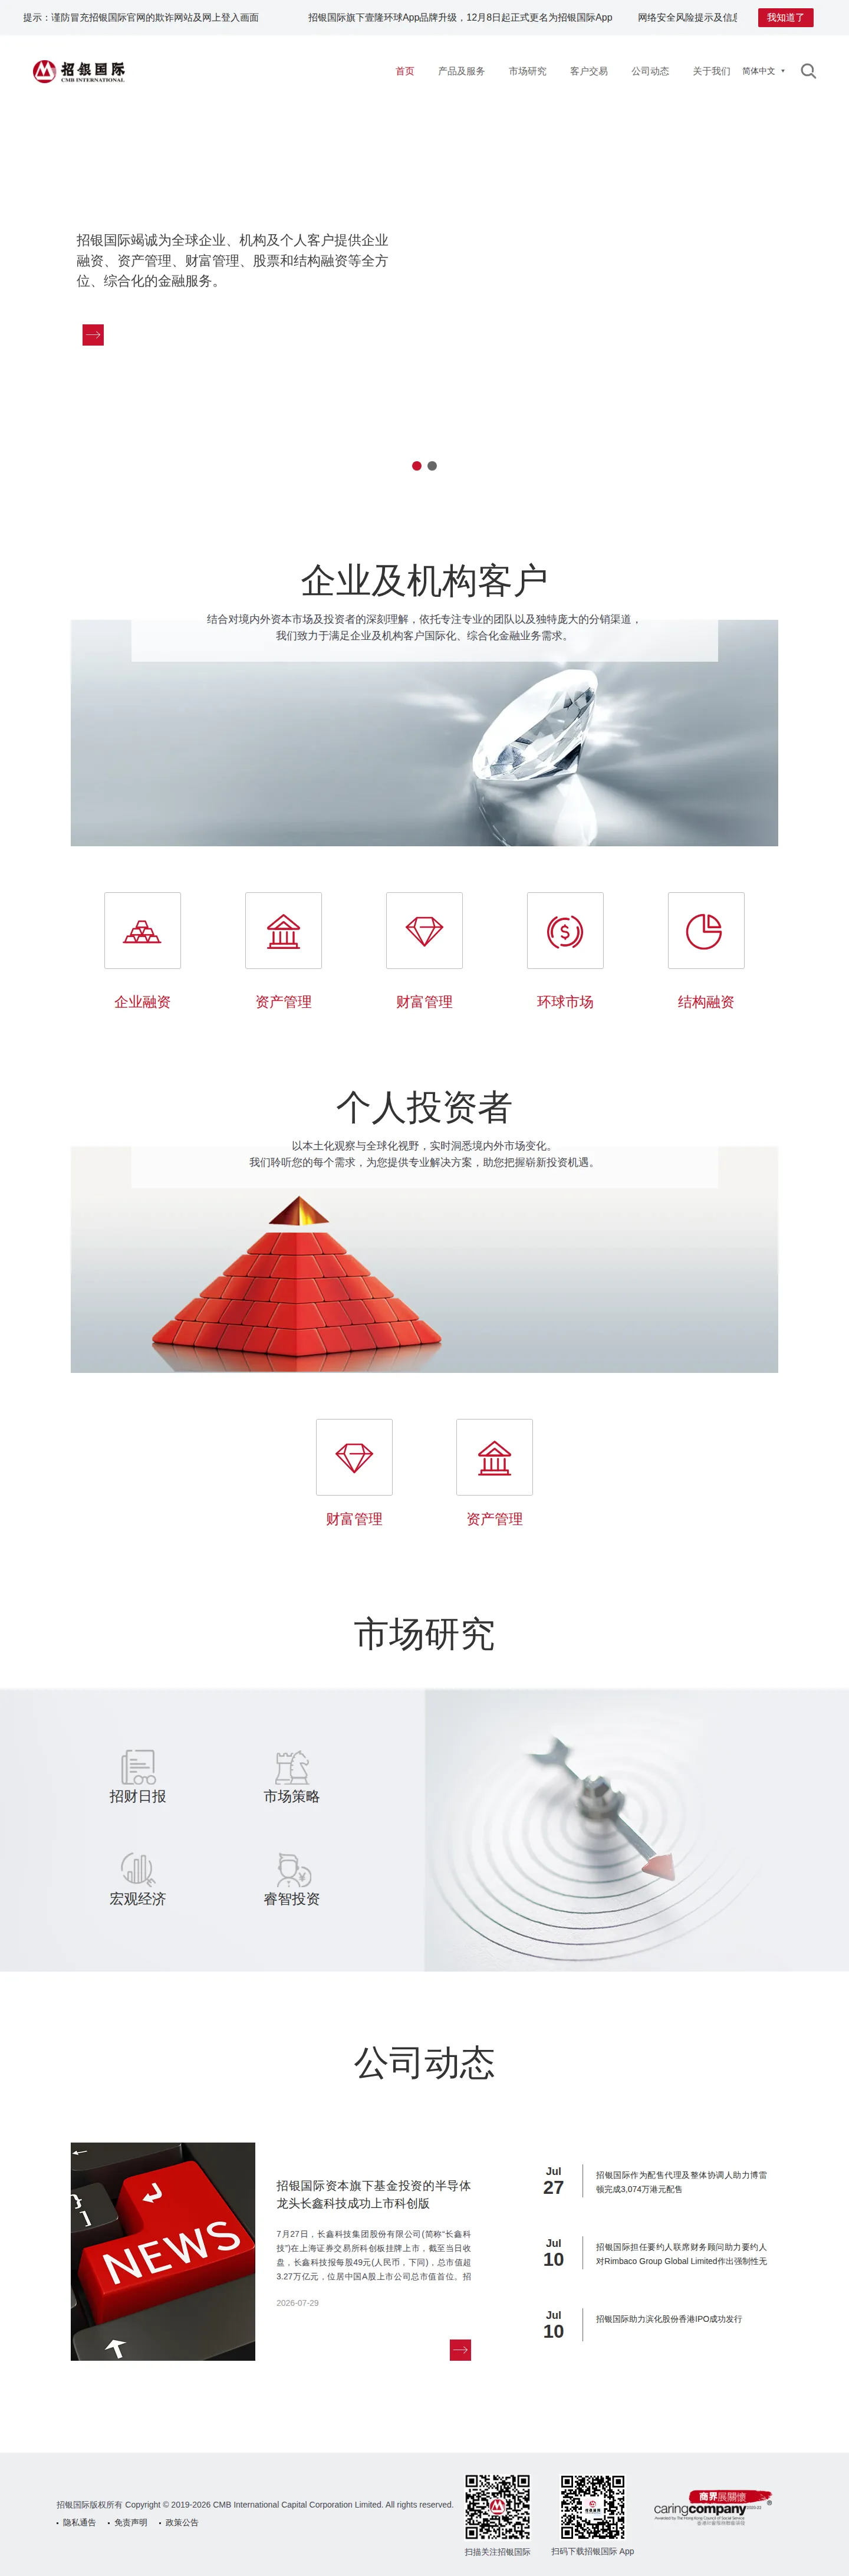
Every page we attempted to fetch covering legal terms, the client agreement, fees, pricing, spreads, risk disclosure, account opening and platform documentation returned an empty body on repeated attempts. That means we could not verify contract terms, a fee schedule, or stated investor protections directly from the firm’s own pages; the fees, accounts, platforms, instruments and payment details below all come from our earlier review not from anything we fetched ourselves. Separately, CMB International’s own homepage carries fraud-warning banners in Chinese alerting visitors to fraudulent sites impersonating its official site and login screen, and to criminals using the CMB International name to commit fraud, alongside a notice about people illegally using its name for securities activities. That is the firm’s own published warning to visitors, not a claim about CMB International’s conduct.
The earlier review reported that CMB International works with institutions, companies and wealthy individuals rather than retail traders, across four account tiers: Individual, Corporate, Prime Brokerage and Wealth Management, each described as relationship-based with minimum deposits set by negotiation rather than a published figure. That review also described three platforms: Yat Lung Global as the branded mobile app now offering 24-hour crypto trading, SP Trader for professional and algorithmic use, and Multicharts for quantitative strategy development and backtesting. It listed equities, ETFs, bonds, futures, options and cryptocurrency among the instruments offered, with crypto trading (BTC, ETH, USDT) restricted to professional investors following what it described as an SFC virtual asset approval in July 2025. The same review characterized CMB International as not advertising blanket negative-balance protection the way retail brokers do, relying instead on client assessment and real-time risk monitoring; that is the earlier review’s characterization, not a statement we read on CMB International’s own pages.
Contacting CMB International
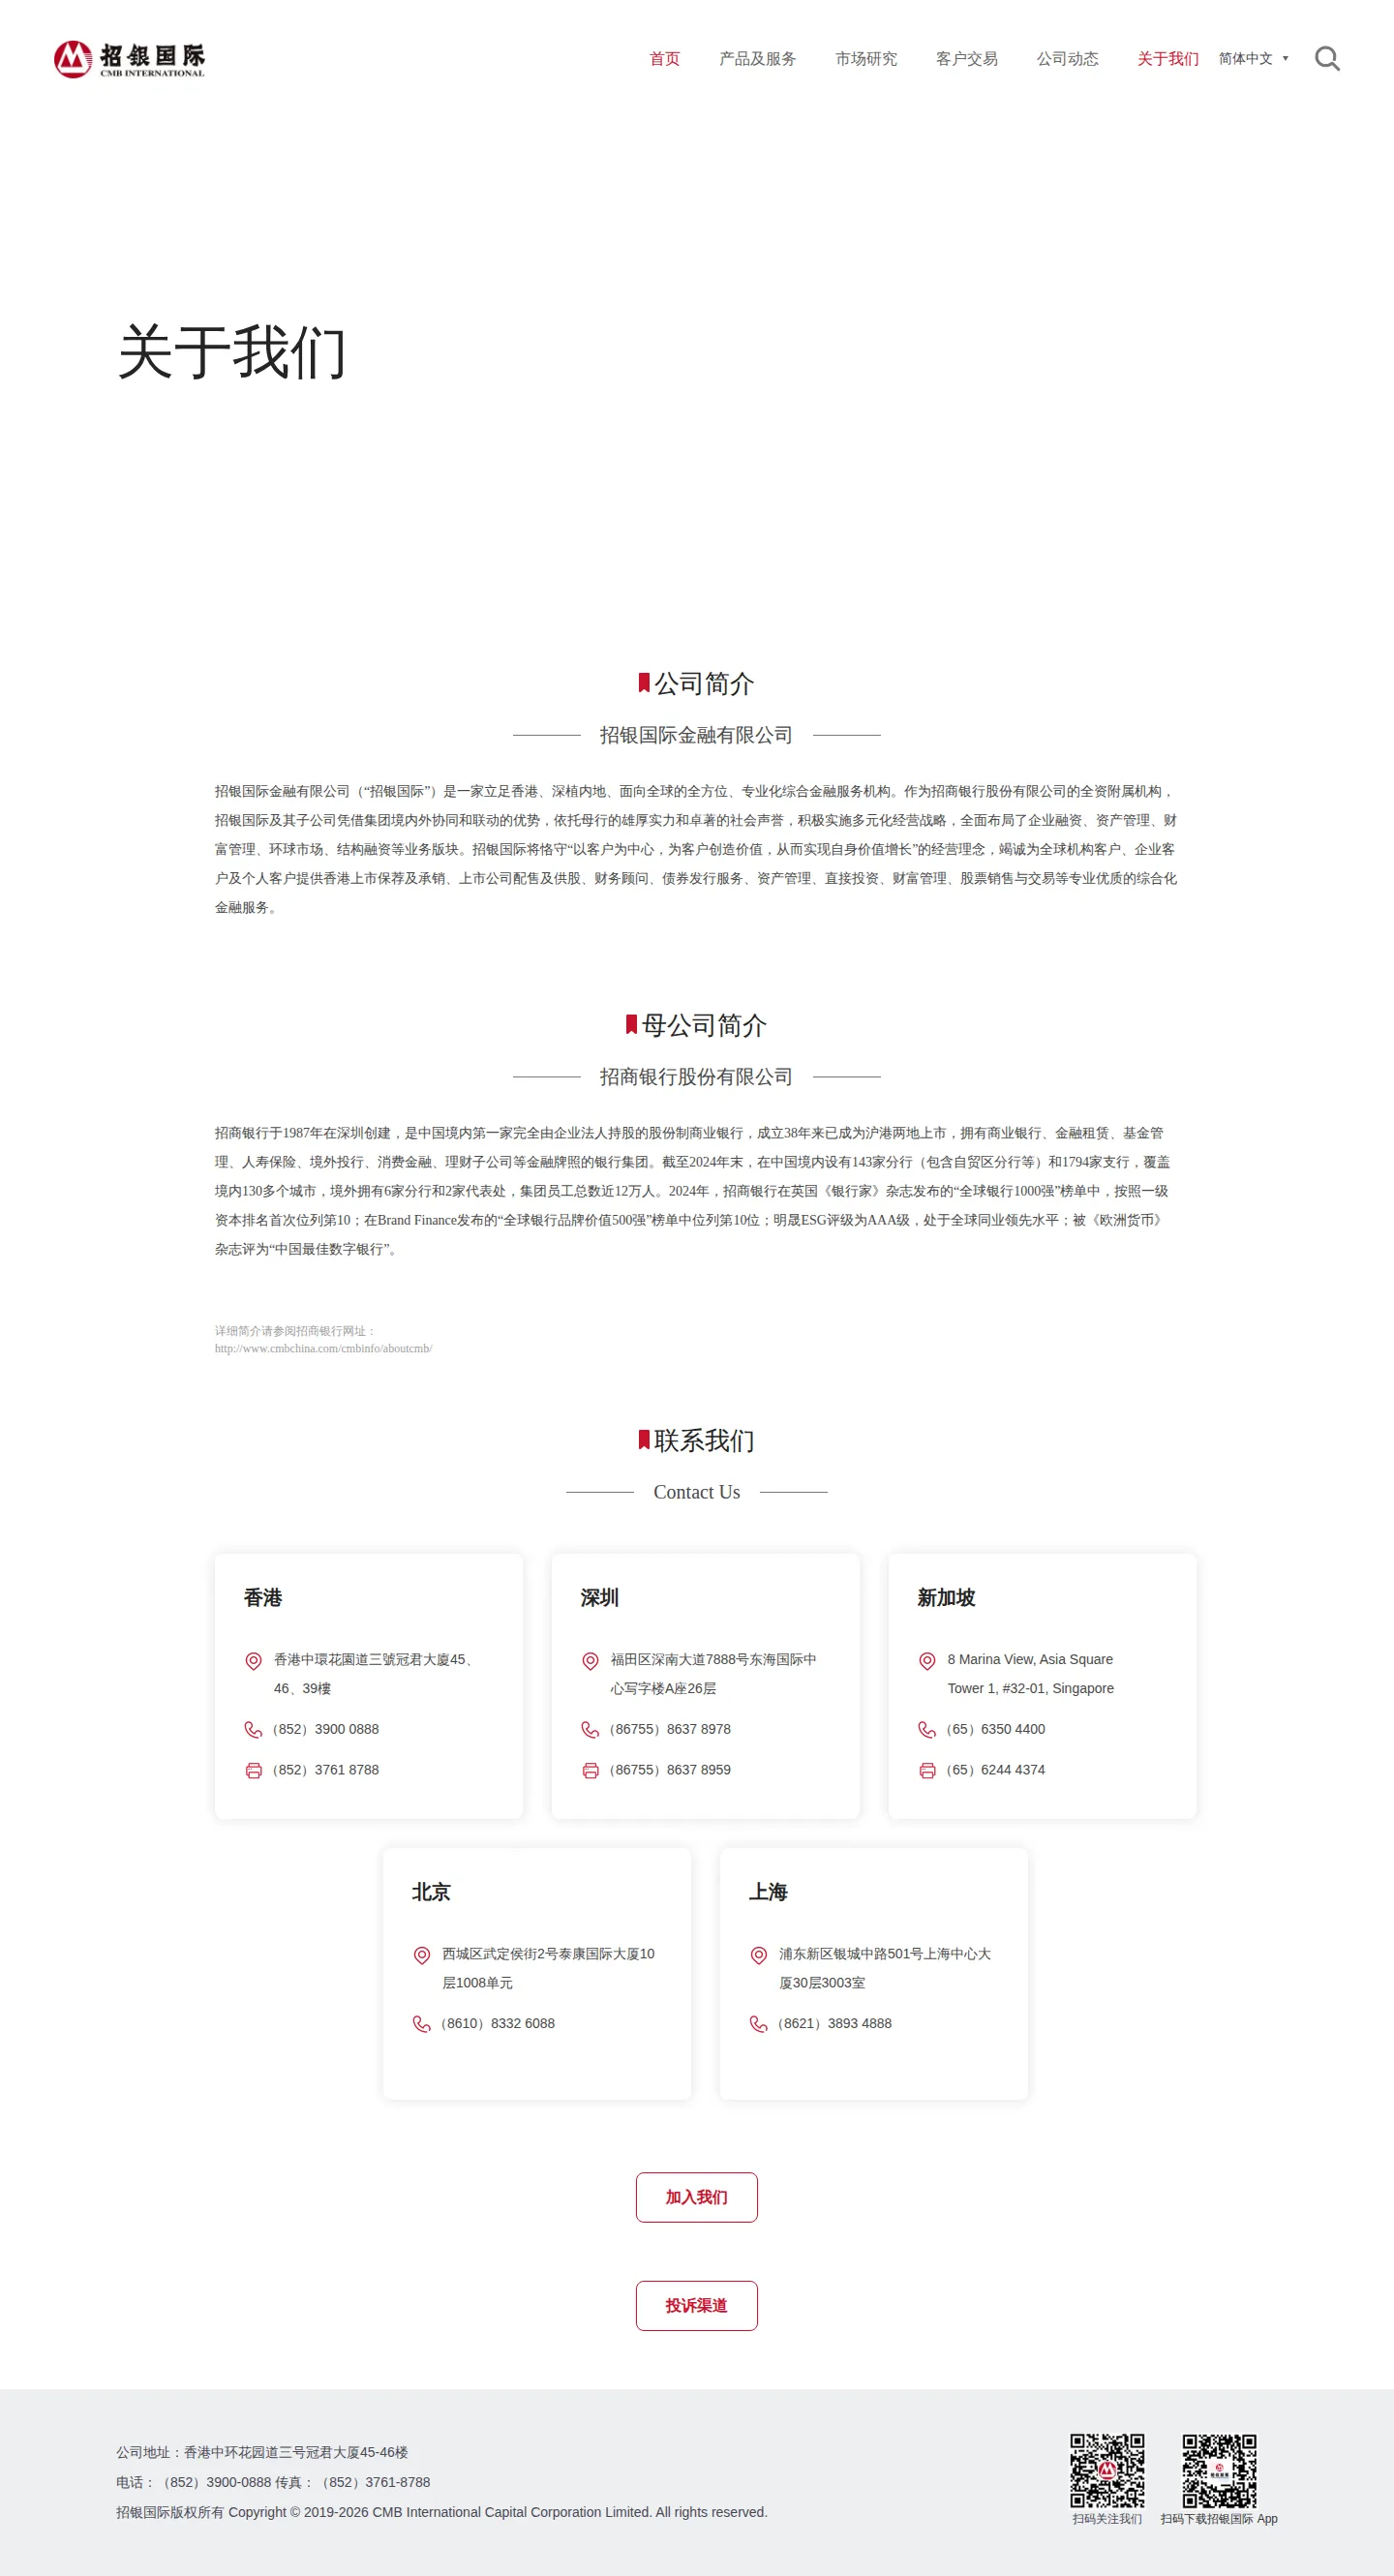
CMB International’s about page lists phone, fax and office addresses for Hong Kong, Shenzhen, Singapore, Beijing and Shanghai, along with a dedicated complaints channel. The Hong Kong office is reachable at (852) 3900 0888, with an office at 45th, 46th and 39th floors, Champion Tower, 3 Garden Road, Central.
Overview Table
| Headquarters | Hong Kong |
| Established | Not stated (parent China Merchants Bank founded 1987 in Shenzhen) |
| Countries Served | Not stated |
| Regulated By | Securities and Futures Commission (SFC), Hong Kong |
| Minimum Deposit | Not stated (accounts described as relationship-based) |
| Maximum Leverage | Not stated |
| Total Instruments | Not stated |
| Platforms | Yat Lung Global, SP Trader, Multicharts |
| Customer Support | Phone, fax and office contacts for Hong Kong, Shenzhen, Singapore, Beijing and Shanghai, plus a dedicated complaints channel |
| Languages | Not stated |
Facts List
- CMB International is the international arm of China Merchants Bank Co., Ltd., a bank founded in 1987 in Shenzhen and listed on the Shanghai and Hong Kong exchanges.
- The group operates through four separately SFC-licensed Hong Kong subsidiaries: Securities, Futures, Capital, and Asset Management.
- CMB International Securities Limited holds SFC CE reference AUZ441 for Type 1 and Type 4, active, with 6 licensing conditions and no recorded disciplinary action.
- CMB International Futures Limited holds SFC CE reference ACQ651 for Type 2, active, with no recorded disciplinary action.
- CMB International Capital Limited holds SFC CE reference AVM940 for Type 1 and Type 6, active, with 2 licensing conditions and no recorded disciplinary action.
- CMB International Asset Management Limited holds SFC CE reference AVA101 for Type 1, Type 4 and Type 9, active, with 3 licensing conditions and no recorded disciplinary action.
- CMB International does not appear on any of the 1,441 warning-list entries we searched, mirrored from CySEC, the FCA and the Mauritius FSC.
- Every legal, fee, risk-disclosure and account-opening page we attempted to fetch from CMB International’s own site returned empty.
- CMB International’s own homepage carries fraud-warning banners alerting visitors to sites and individuals impersonating its name.
- Additional claims of a Money Lenders License, HKMA registration, CSRC RQFII qualification and Stock Connect programme access came from the earlier review with no licence number or register entry we could check.
Key Takeaways
Why the score moved
Our previous score for CMB International was 4 out of 10. This review scores it 5 out of 10. We are restating the score from the current evidence rather than describing any change at the firm. The move is driven mainly by regulation: the SFC register confirms four separate CMBI entities as active licence holders, which is a stronger and more checkable footing than the earlier pass had. That strength is offset by fees, which score 2 out of 10 because we could not pull a single fee, spread or commission figure from the firm’s own site.
What the SFC register confirms
We searched the Hong Kong SFC Public Register of Licensed Persons and Registered Institutions directly, and ran a positive control first so an empty result would mean absence rather than a broken search. Four CMBI entities come back as active:
- CMB International Securities Limited holds CE reference AUZ441, licensed for Type 1 and Type 4 (dealing in securities, advising on securities), both active, with 6 licensing conditions attached.
- CMB International Futures Limited holds CE reference ACQ651, licensed for Type 2 (dealing in futures contracts), active.
- CMB International Capital Limited holds CE reference AVM940, licensed for Type 1 and Type 6 (dealing in securities, advising on corporate finance), both active, with 2 licensing conditions attached.
- CMB International Asset Management Limited holds CE reference AVA101, licensed for Type 1, Type 4 and Type 9 (dealing in securities, advising on securities, asset management), all active, with 3 licensing conditions attached.
The register records no public disciplinary action against any of the four. None of the four licence entries carries a description of what its licensing conditions actually require, so we cannot say what those conditions restrict.
What the register cannot confirm
Several claims tied to CMBI have nothing for us to check against a public database. One SFC-linked claim names neither a licence number nor an entity, so there is no way to look it up. Four further claims, taken from our earlier review, name a “Money Lenders License,” an “HKMA Registration,” a “CSRC RQFII qualification” and “Stock Connect program licenses” but give no licence numbers and, for the HKMA and CSRC items, no clarity on whether the description points to a full licence or a lesser registration or market-access qualification. We hold no register entry for any of those four authorities, so these are gaps in our directory rather than findings about the firm.
We also searched 1441 warning list entries mirrored from CYSEC, the FCA and the FSC Mauritius, and CMB International appears on none of them. That is a clean result, though it only covers the three regulators we mirror, not every warning list that exists.
What we could not verify on CMB International’s own site
Every page we attempted for terms, fees, pricing, spreads, risk disclosure, the client agreement and platform specifics returned as empty on repeated attempts. That means no fee schedule, no contract terms and no published cost basis could be checked against the firm’s own documentation, which is the direct reason fees scores 2 out of 10. Everything on account tiers, platforms, instruments, payment methods and client restrictions in this review is carried over from the earlier published review rather than from a page we fetched ourselves, and none of it appears in quotation marks because we did not read the underlying documents.
What the earlier review reported, restated
The earlier review described four account tiers (Individual, Corporate, Prime Brokerage and Wealth Management), three platforms (the Yat Lung Global app, SP Trader for professional multi-device use, and Multicharts for algorithmic strategy work), and coverage across equities, ETFs, bonds, futures, options and a professional-investor-only crypto offering said to have launched under SFC virtual asset approval in July 2025. It also reported that CMBI does not advertise blanket negative balance protection the way retail brokers do, relying instead on its own client assessment and real time risk monitoring, and that the firm positions itself as serving institutional, corporate and high net worth clients rather than retail traders. None of this carries a source document we read ourselves.
A detail worth flagging
CMB International’s own homepage carries repeated fraud warning banners in Chinese, alerting visitors to fraudulent sites impersonating its official site and login screen, and to criminals using the CMBI name to run scams. That is the firm’s own published warning, not our characterization, and it is worth knowing before assuming any given CMBI branded page or channel is genuine.
Licenses & Regulation
CMB International’s overall score moves from 4/10 to 5/10 in this review. That shift is our assessment, not a change at the firm, and it is anchored in what the register checks below actually turned up: four operating subsidiaries confirmed as active, licensed entities on Hong Kong’s SFC register, with no public disciplinary action recorded against any of them, and a clean run against 1441 warning-list entries mirrored from CYSEC, FCA and FSC Mauritius. The regulation criterion scores 7.8/10 on that basis. It is not a clean sweep, and the gaps below matter as much as the confirmations.
What the SFC register confirms about CMB International
We searched the Hong Kong Securities and Futures Commission’s Public Register of Licensed Persons and Registered Institutions directly, and ran a positive control against a firm known to be listed before treating any empty result as an absence. Four entities carrying the CMB International name came back active:
- CMB International Securities Limited holds CE reference AUZ441, licensed for Type 1 and Type 4 (Dealing in Securities; Advising on Securities), both shown as active, with 6 licensing conditions attached and no public disciplinary action recorded.
- CMB International Futures Limited holds CE reference ACQ651, licensed for Type 2 (Dealing in Futures Contracts), shown as active, with no public disciplinary action recorded.
- CMB International Capital Limited holds CE reference AVM940, licensed for Type 1 and Type 6 (Dealing in Securities; Advising on Corporate Finance), both active, carrying 2 licensing conditions, with no public disciplinary action recorded.
- CMB International Asset Management Limited holds CE reference AVA101, licensed for Type 1, Type 4 and Type 9 (Dealing in Securities; Advising on Securities; Asset Management), all active, carrying 3 licensing conditions, with no public disciplinary action recorded.
Our earlier review had named these same four subsidiaries as the firm’s licensing structure without always giving a licence number; one further authorisation claim it passed us named neither a licence number nor a specific entity, which left nothing on the register for us to look up. That is a gap in what was published or in what we read, not a finding about the firm.
Claims we could not check against any register
The earlier review also passed us four further claims: a “Money Lenders License,” an “HKMA Registration for banking-related services,” a “CSRC RQFII qualification,” and “Stock Connect program licenses.” Each was described only in that vague form, without a licence number, and in each case we hold no register entry for the naming authority given, so none of the four has been checked. That is a gap in our directory, not a finding about the firm, and it means a reader should treat CMB International’s money-lending, banking-registration, RQFII and Stock Connect access claims as unverified rather than confirmed or denied.
What CMB International’s own site would and would not load
Every attempt to fetch the firm’s own legal, terms-and-conditions, client-agreement, fee schedule, risk-disclosure or platform pages returned an empty body, on repeated tries. That means the regulation picture above rests on the SFC register and on the earlier review’s account of CMBI’s licensing structure, not on any client agreement or risk disclosure we were able to read ourselves. The pages that did load were company contact and about pages, which list offices in Hong Kong, Shenzhen, Singapore, Beijing and Shanghai alongside phone and fax numbers for each, and a named complaints channel on the Hong Kong site. Those same pages carry repeated fraud-warning banners from the firm itself, in Chinese, warning visitors against sites and login screens that impersonate CMB International’s official channels, plus a separate notice about people illegally using the CMBI name in connection with securities activity. That is the firm’s own warning about impersonation, not a comment on CMBI’s own conduct, but it is worth a reader’s attention when confirming they are on a genuine CMBI channel.
Group structure and the warning-list search
The entity behind the marketing name is CMB International Financial Company Limited (招银国际金融有限公司), described on the firm’s own about page as a wholly-owned subsidiary of China Merchants Bank Co., Ltd. (招商银行股份有限公司), the Shenzhen-founded parent bank listed in Shanghai and Hong Kong. The site footer separately names CMB International Capital Corporation Limited as the copyright holder, distinct from the four SFC-licensed operating subsidiaries above, which is a naming complexity a reader should be aware of when working out which entity they would actually be contracting with. We searched 1441 warning-list entries mirrored from CYSEC, FCA and FSC Mauritius, and CMB International appears on none of them. That result covers only the three regulators we mirror, not every regulator worldwide, so it should be read as a clean result on those three lists rather than a general clearance.
How to Trade
CMB International trades through a cluster of Hong Kong-licensed subsidiaries rather than one entity, and which subsidiary actually books a trade depends on the product. The Hong Kong SFC register we checked confirms CMB International Securities Limited (CE reference AUZ441) is licensed for Type 1 and Type 4 activity, dealing in securities and advising on securities, both shown as active and carrying six licensing conditions; CMB International Futures Limited (ACQ651) is licensed for Type 2, dealing in futures contracts; CMB International Capital Limited (AVM940) is licensed for Type 1 and Type 6, securities dealing and corporate finance advisory; and CMB International Asset Management Limited (AVA101) is licensed for Type 1, Type 4 and Type 9, adding asset management to securities dealing and advisory. None of the four carries a recorded public disciplinary action on the register.
What CMB International trades
We could not pull any of this from the firm’s own site: every page we tried for platform documentation, fees, account terms or risk disclosure returned no content at all, repeatedly. What follows on instruments and execution therefore comes from our earlier review restated in our own words rather than the firm’s, and it should be read as a description of what that review found rather than something we verified first-hand. It described CMBI clients getting direct market access to equities with extended hours on US stocks, and reach into Hong Kong, US and China A-share listings through the Stock Connect link; Hong Kong-listed and international ETFs; bonds in both primary and secondary markets across Asia-Pacific and beyond; index and commodity futures and options on CME, SGX and HKEX; and cryptocurrency trading in BTC, ETH and USDT around the clock, restricted to professional investors and dated to a July 2025 SFC virtual-asset approval. Our own register check confirms CMB International Securities Limited’s securities licence is active, but it does not itself confirm a virtual-asset dealing scope, so the crypto detail rests on our earlier review alone, not on anything the register showed us.
Platforms and how orders get filled
The same earlier review named three platforms: Yat Lung Global, a branded mobile app for iOS and Android that it said now covers 24/7 crypto trading alongside real-time data, charting and order execution; SP Trader, described as a multi-device platform built for professional traders with algorithmic trading and multi-monitor support plus futures and options analytics; and Multicharts, a desktop platform for quantitative traders offering strategy development, backtesting, custom indicators and portfolio analysis. We have no first-hand platform page, demo, or spread sheet to check any of that against, because the platform and pricing URLs on the firm’s site returned nothing when we tried to fetch them. That gap is the main reason this review’s platform score sits at 4.5 out of 10: what a client would actually see inside the order ticket, what execution model each platform uses, and what spreads or commissions apply are all things we cannot check from CMBI’s own material.
The earlier review also characterized CMBI as not advertising blanket negative-balance protection the way many retail brokers do, describing it instead as relying on client suitability assessment and real-time risk monitoring. That is the earlier review’s own characterization of the firm’s approach, not a line found on any CMBI page we read, and we have not seen a CMBI risk disclosure to confirm or contradict it.
Account tiers CMB International offers
| Tier | Minimum deposit | What our earlier review said came with it |
|---|---|---|
| Individual | Relationship-based | All trading products, leverage available on a qualified basis, all platforms, standard research, a relationship manager, crypto trading on a qualified basis |
| Corporate | Higher requirements | All trading products, leverage, all platforms, enhanced research, a dedicated relationship manager, crypto trading on a qualified basis |
| Prime Brokerage | Institutional | All products plus exclusive offerings, enhanced leverage, all platforms plus API access, full research with direct access, a team-coverage relationship manager, crypto trading |
| Wealth Management | High requirements | All trading products, leverage, all platforms plus exclusive access, premium research, a senior dedicated relationship manager, crypto trading |
None of the deposit figures above is a number: the earlier review described them only in these relative terms, and we have no CMBI account-opening page to convert “relationship-based” or “institutional” into an actual dollar minimum.
Who CMB International will actually trade with
Our earlier review described the firm as serving institutional, corporate and high-net-worth clients rather than retail or small traders, and listed a set of jurisdiction-specific limits on top of that: crypto trading confined to professional investors under the scope of its SFC virtual-asset approval; US persons needing accredited-investor status; possible MiFID II-related restrictions for EU residents; enhanced requirements or outright prohibitions for countries under UN sanctions or FATF blacklists; and access for mainland Chinese residents kept within capital-control rules. We are again reporting what the earlier review said here, not something read from a CMBI terms page, since none loaded for us.
This review scores CMB International 5 out of 10 overall, up from our previous 4. The move is our assessment on this pass, not a change in the firm: the regulation score of 7.8 reflects four active SFC licences confirmed directly on the Hong Kong register with no recorded disciplinary history, and a clean result when we checked the firm’s name against 1,441 warning-list entries mirrored from CySEC, the FCA and the FSC Mauritius; the fees score of 2 and the platform score of 4.5 reflect that we hold no first-hand pricing, spread or execution detail at all, only what an earlier review described.
Account Types
CMB International does not sell one product line off a single price sheet. The firm structures its accounts around a small number of relationship tiers, and our earlier review described four of them: Individual, Corporate, Prime Brokerage, and Wealth Management. We restate that structure below in our own words; it was not something we read on CMBI’s own site, because every account, fee, and pricing page we attempted to fetch from the firm returned an empty response.
The four tiers CMB International is reported to run
The Individual tier is opened on a relationship basis rather than against a fixed minimum, and is reported to carry access to the firm’s full range of trading products, leverage where a client qualifies for it, all of the firm’s trading platforms, standard research, a relationship manager, and crypto trading for clients who meet the qualifying bar. Corporate sits above it with a higher deposit requirement, the same product range and leverage access, all platforms, research described as enhanced rather than standard, and a dedicated rather than shared relationship manager.
Prime Brokerage is pitched at an institutional deposit level and is reported to add exclusive trading products on top of the standard range, enhanced leverage terms, API access alongside the firm’s platforms, full research with direct access rather than a filtered feed, a team rather than a single relationship manager, and crypto trading without the qualifying-investor caveat attached to the tiers below it. Wealth Management is described as carrying a high deposit requirement of its own, the full product range with leverage, an exclusive platform tier on top of the standard set, premium research, a senior dedicated relationship manager, and crypto trading.
What we could not check on CMB International’s own pages
None of the deposit figures, fee schedules, spread structures, or commission rates behind these tiers reached us as numbers. Every URL we attempted on the firm’s own domains for legal terms, a client agreement, fees, pricing, spreads, a risk disclosure, or platform documentation came back as an empty page on repeated tries, so there was no account-opening documentation, fee table, or terms of business we could read first-hand to check the tier descriptions above or to price what a client actually pays to trade. That gap is reflected in the fees score this review gives the firm, 2 out of 10.
Crypto access across the tiers is reported to be limited to professional investors, consistent with the firm’s SFC virtual asset approval, which the earlier review dates to July 2025; that approval covers CMB International Securities Limited, one of the four subsidiaries the SFC register confirms as separately licensed under CE reference AUZ441. Which of the group’s licensed entities actually onboards a client, and therefore which SFC licence and conditions apply to that account, is something the tier descriptions above do not specify.
Score change
Our previous review scored CMB International 4 out of 10 overall; this one scores it 5. The move is this review’s own reassessment against current evidence and is not a claim that the firm has changed. Regulation now scores 7.8, resting on SFC register entries that confirm four separately licensed subsidiaries, each shown active with no public disciplinary action recorded against it. Fees still scores 2, because the account and pricing pages needed to check the tier descriptions above could not be retrieved from the firm’s own site.
Negative Balance Protection
CMB International’s own site gave us nothing to check here. Every URL we tried for a client agreement, risk disclosure, or fee schedule (paths including /legal, /terms-and-conditions, /client-agreement, /fees, /pricing, /spreads, /risk-disclosure) came back as a zero-byte page on repeated attempts. That means the loss limit and drawdown terms below rest entirely on our earlier review not on any document we read ourselves, and none of it can be put in quotation marks or treated as the firm’s own wording.
What the earlier review reported about CMB International and negative balances
The earlier review’s account of CMB International (CMBI) describes a firm that does not advertise a blanket negative balance protection guarantee of the kind retail brokers typically promote. Instead, according to that review, CMBI relies on client assessment and real time risk monitoring to manage drawdown exposure. That is the earlier review’s characterization of the firm’s approach, not a policy statement found on CMBI’s own pages, since we could not retrieve any risk disclosure or client agreement from the site to confirm or contradict it.
The same review lists four account tiers, Individual, Corporate, Prime Brokerage, and Wealth Management, each marked as offering leverage, with Prime Brokerage specifically flagged for “enhanced leverage”. None of the minimum deposit figures for these tiers are numeric; they are described only as “relationship based,” “higher requirements,” “institutional,” and “high requirements.” With no fee schedule or margin policy document available to us, we cannot say what margin call thresholds, stop out levels, or liquidation triggers apply at any of these tiers, or whether they differ between them.
Why the register findings do not fill the gap
The Hong Kong SFC register confirms four separate licensed entities under the CMBI umbrella: CMB International Securities Limited (CE reference AUZ441, Type 1 and Type 4, six licensing conditions attached), CMB International Futures Limited (CE reference ACQ651, Type 2), CMB International Capital Limited (CE reference AVM940, Type 1 and Type 6, two licensing conditions), and CMB International Asset Management Limited (CE reference AVA101, Type 1, Type 4, and Type 9, three licensing conditions). The register shows no public disciplinary action against any of the four. None of that, however, tells us what those licensing conditions actually require in terms of client money segregation, margin treatment, or negative balance exposure. Licensing conditions attached to an SFC licence are typically firm specific undertakings, and we have not read their text, so we cannot describe what they cover.
A fifth claimed SFC authorisation in the evidence carries no licence number and no named entity, so there was nothing for us to look up, and the money lending authorisation, HKMA registration, CSRC RQFII qualification, and Stock Connect programme access cited by the earlier review are all listed against the group as “CMBI” generally rather than a specific licensed entity, again with no register we hold to check them against. That is a gap in what reached us, not a finding about whether these registrations exist or what they would mean for a client’s account.
What this means for a client of CMB International
Because CMBI is described, both by the earlier review and by its own account restrictions, as serving institutional, corporate, and high net worth clients rather than retail traders, the absence of a published, blanket negative balance guarantee is less unusual here than it would be for a retail CFD broker. Institutional and prime brokerage clients are typically expected to manage their own margin and drawdown exposure under bespoke agreements rather than a standardised retail style protection promise. But we want to be precise about what we actually hold: we have no client agreement, margin policy, or risk disclosure document from CMBI itself describing stop out levels, margin call procedures, or what happens to a client’s account if losses exceed deposited funds. The cryptocurrency offering, which the review notes launched in July 2025 under SFC virtual asset approval and is restricted to professional investors, carries the same absence of documented drawdown mechanics in what we were able to retrieve.
On the warning list side, we searched 1441 entries mirrored from CYSEC, the FCA, and FSC Mauritius, and CMB International does not appear on any of them. That is a clean result worth noting, though it only covers the regulators we mirror and says nothing about margin practice.
Our previous score for this section area contributed to an overall 4 out of 10; this review scores the broker 5 out of 10 overall. The move is not a comment on CMBI getting better or worse. Regulation now scores 7.8, driven by the four confirmed active SFC licences with no recorded disciplinary action; fees score 2, reflecting that no fee schedule, spread data, or margin cost terms could be retrieved from the firm’s own site at all. The negative balance question sits inside that same evidence gap: without a client agreement or risk disclosure document, we are restating what an earlier review said about CMBI’s approach rather than reporting terms we read ourselves.
Trading Instruments
The evidence here comes almost entirely from our earlier review not from CMB International’s own site: every attempt to fetch the firm’s pages for products, fees, accounts and platform documentation came back “body only 0 bytes.” What follows is that earlier review’s account of what CMBI trades, restated in our words, alongside what our own register checks add.
What the earlier review said CMB International trades
The prior review described a product list built around Hong Kong’s institutional and cross-border business: equities with direct market access and extended hours for US stocks, covering China A-shares, Hong Kong and US stocks through the Stock Connect programme; Hong Kong-listed and international ETFs; bonds and fixed income in primary and secondary markets across Asia-Pacific and globally; index and commodity futures and options on CME, SGX and HKEX; and cryptocurrency trading in BTC, ETH and USDT. The earlier review noted the crypto offering runs 24/7 but is restricted to professional investors, and dated it to a July 2025 launch under an SFC virtual asset approval. None of this range, and none of the professional-investor restriction on crypto, is something we read on a CMBI page ourselves.
What the SFC register confirms about who can deal in what
Our own check of the SFC Public Register of Licensed Persons and Registered Institutions is firmer ground. CMB International Securities Limited holds CE reference AUZ441, licensed for Type 1 (Dealing in Securities) and Type 4 (Advising on Securities), both shown as active, with 6 licensing conditions attached; the register records no public disciplinary action against it. CMB International Futures Limited holds CE reference ACQ651, licensed for Type 2 (Dealing in Futures Contracts), active, again with no disciplinary action on record. CMB International Capital Limited holds CE reference AVM940, licensed for Type 1 and Type 6 (Dealing in Securities; Advising on Corporate Finance), active, with 2 conditions and no disciplinary action recorded. CMB International Asset Management Limited holds CE reference AVA101, licensed for Type 1, Type 4 and Type 9 (Dealing in Securities; Advising on Securities; Asset Management), active, with 3 conditions and no disciplinary action recorded. That four-way split matters for what a client actually gets access to: which entity opens the account determines which of these licence types, and therefore which products, apply to that relationship.
Claims we could not check on any register
The earlier review also listed a “Money Lenders License,” an “HKMA Registration for banking-related services,” a “CSRC RQFII qualification,” and “Stock Connect program licenses.” We hold no register entry for HKMA, CSRC, the money-lending authority named, or the Stock Connect programme, and none of these four claims names a licence number, so there was nothing for us to look up. That is a gap in our directory and in what was published, not a finding about the firm, and it means the China A-shares access the earlier review attributed to Stock Connect, and the RQFII qualification said to sit behind mainland market access, stand as unverified claims rather than confirmed register facts.
Platforms named for reaching these products
The earlier review named three platforms for accessing this range: Yat Lung Global, the firm’s branded mobile app for iOS and Android, said to now include the 24/7 crypto trading, real-time data and order execution; SP Trader, described as a multi-device platform for professional traders with algorithmic trading and futures/options analytics; and Multicharts, a desktop platform for quantitative traders with backtesting and custom indicators. Again, none of these platform pages returned content when we tried to fetch them, so the feature list is the earlier review’s description, not ours.
Account tiers and who they are said to be for
The earlier review split access into four tiers, Individual, Corporate, Prime Brokerage and Wealth Management, each said to carry relationship-based or institutional minimum deposits rather than a published figure, and each said to include crypto trading only in a “qualified” sense. Separately, the restrictions list states the firm works only with institutions, companies and wealthy individuals, which fits a review category of “institutional” but is not something we read on a CMBI account-opening page ourselves.
This review scores assets at 4.5/10 on the platform criterion, up from the prior 4/10 overall score; the movement reflects a change in what this review’s scoring rests on rather than any change at CMB International. The confirmed four-entity SFC licensing split, each entity carrying active dealing or advising permissions and a clean disciplinary record, and a clean result against 1,441 mirrored CYSEC, FCA and FSC Mauritius warning-list entries, are real findings this time round. Against that sits the same wall the earlier review ran into: no terms of business, fee schedule, risk disclosure or platform documentation could be retrieved from the firm’s own site on repeated attempts, so the product range, the crypto restriction, and the account tiers all rest on a review of the firm rather than the firm’s own pages.
Education & Analysis
Platform scores 4.5/10 here, and the reason sits in the evidence rather than in anything the platforms themselves lack. Everything below on CMB International’s trading technology reached us through our earlier review not through pages we fetched: every attempt to pull the firm’s own platform, pricing or terms pages returned zero bytes, repeatedly, across /platforms, /mt4, /legal, /fees and the rest. We could not read a CMBI platform page first-hand for this review.
What the earlier review reported about CMB International’s platforms
The earlier review describes three separate systems rather than one house platform. Yat Lung Global is named as the firm’s primary branded mobile app, for iOS and Android, and is described as having grown to include 24/7 crypto trading alongside real-time data, charting and order execution. SP Trader is described as a multi-device platform aimed at professional traders, with algorithmic trading, multi-monitor support and futures/options analytics. Multicharts is described as a desktop platform for quantitative and algorithmic traders, offering strategy development, backtesting, custom indicators and portfolio analysis. None of these three names, features or the split between them comes from a CMBI page we read ourselves; restate them as what the prior review said, not as what CMBI’s own site says, because we never reached that site’s platform pages.
What CMB International’s own site showed us
What we did reach directly was the firm’s Hong Kong “About” page, which gave phone numbers, fax numbers and street addresses for offices in Hong Kong, Shenzhen, Singapore, Beijing and Shanghai, plus a named complaints channel. It did not give us a platform page, a charting page, an MT4 or MT5 page, a fees page or a client-agreement page; every one of those URLs came back as a zero-byte body on repeated attempts. That is a first-hand finding about what CMBI currently makes reachable to an outside fetch, separate from anything the earlier review says about the platforms themselves.
The same homepage did carry two fraud warnings in Chinese, cautioning visitors against sites and login screens impersonating CMBI’s official channels and against criminals using the CMBI name to commit fraud, plus a notice clarifying that some parties have illegally used the CMBI name in connection with securities activity. Worth knowing when trying to work out whether a given login screen, app store listing or platform download link is a genuine CMBI channel, since the firm itself is flagging that impersonation is a live problem around its name.
Instruments the earlier review lists across those platforms
The instrument range described in that earlier review is broad for the platform set: equities with direct market access and extended hours for US stocks, covering Hong Kong, US and China A-shares via Stock Connect; Hong Kong-listed and international ETFs; bonds and fixed income across Asia-Pacific and global markets; index and commodity futures and options on CME, SGX and HKEX; and cryptocurrency trading in BTC, ETH and USDT, described as 24/7 and restricted to professional investors, said to have launched in July 2025 under an SFC virtual asset approval. The SFC register itself, separately, records CMB International Securities Limited as licensed for Type 1 and Type 4 activity (dealing in securities, advising on securities) and CMB International Futures Limited as licensed for Type 2 (dealing in futures contracts), both shown active, which is consistent with a firm running securities and futures dealing through separate group entities. The register entries do not describe the software those licensed activities run on; that detail rests entirely on the earlier review.
Why this drags the platform score down
A 4.5 out of 10 on platform reflects a real gap: this review cannot independently confirm what Yat Lung Global, SP Trader or Multicharts actually look like, what they cost to access, or whether the charting and analytics described in the earlier review still match what CMBI ships today, because the firm’s own pages would not return content. Our overall score moved from 4/10 to 5/10 in this review, and that is our assessment being recalculated against current evidence and a changed set of criteria, not a claim that CMBI’s platforms got better or worse. Regulation, at 7.8, is the strongest thing in this scorecard, resting on confirmed SFC entries for four separate CMBI entities; platform, fees and support all sit well below that, and for platform specifically the drag is the absence of any first-hand look at the tools a client would actually trade on.
Special Offers
We tried to pull CMB International’s own fee, pricing, spreads, terms-and-conditions, client-agreement and account-opening pages directly, along with its platform pages. Every one of those URLs came back with a body of zero bytes on repeated attempts. That means we hold no promotions page, no fee schedule and no account-opening document from the firm’s own site to check for a deposit bonus, a spread discount, a cash-back scheme or any other promotional offer. We are not in a position to say CMBI does or does not run promotions; we are only in a position to say the pages that would carry that detail did not load for us.
What the earlier review reported about CMB International’s account tiers
Our earlier review for this catalogue described four account tiers at CMBI: Individual, Corporate, Prime Brokerage and Wealth Management. It gave the minimum commitment for each as relationship-based for Individual, a higher requirement for Corporate, an institutional-level requirement for Prime Brokerage, and a high requirement again for Wealth Management, with each tier adding research access, leverage terms and the level of relationship-manager coverage rather than a price break. None of that earlier review’s description mentions a promotional credit, a deposit-matching bonus, a rebate period or a fee waiver attached to any tier. We are restating what that prior review reported, not quoting it and not treating it as CMBI’s own published wording, because we have not read the account-opening document it was drawn from.
That same earlier review recorded a restriction worth setting alongside any offer claim: it reported that CMBI states it works only with institutions, companies and wealthy individuals, and does not describe itself as taking on retail or small traders. Deposit-matching or welcome-bonus promotions are a retail-acquisition tool; a firm describing its client base the way that earlier review describes CMBI’s would have little reason to run one, though that is our inference from the client-base description, not a promotions claim the review itself made.
A warning worth carrying into any offer a reader is sent
CMB International’s own Hong Kong homepage that we did load carries repeated fraud warnings in Chinese: one reading, in translation, beware of fraudulent sites impersonating CMBI’s official site and login screens, and a second reading beware of criminals impersonating CMB International to commit fraud, alongside a clarification notice about people illegally using the CMBI name in connection with securities activity. If a reader is approached with a deposit bonus or trading credit offer branded CMB International, that banner on the firm’s own site is a reason to verify the channel it arrived through before treating it as genuine, independently of whether CMBI runs any promotion at all.
We also searched 1,441 warning-list entries mirrored from CYSEC, the FCA and the Mauritius FSC, run against a positive control so an empty result means absence rather than a broken search, and CMB International does not appear on any of them. That is a clean result on the lists we mirror, not a check of promotional practices, and it covers only those three regulators’ lists, not every regulator that publishes one.
Opening an Account
CMB International Securities Limited, CMB International Futures Limited, CMB International Capital Limited and CMB International Asset Management Limited are each licensed by Hong Kong’s Securities and Futures Commission under a different combination of licence types, and our earlier review for this catalogue reports that account opening is split across these same four subsidiaries rather than a single onboarding desk. Which entity actually takes on a new client, and which licence conditions and protections apply, depends on which business line is opening the account: securities dealing and advising sits with CMB International Securities Limited (SFC reference AUZ441, six licensing conditions attached), futures dealing sits with CMB International Futures Limited (SFC reference ACQ651), corporate finance advisory sits with CMB International Capital Limited (SFC reference AVM940, two licensing conditions), and asset management sits with CMB International Asset Management Limited (SFC reference AVA101, three licensing conditions).
The account tiers CMB International offers
The earlier review describes four tiers: an Individual account with relationship-based rather than published minimum deposits, qualified access to leverage and to crypto trading, and a relationship manager; a Corporate account with higher deposit requirements and a dedicated relationship manager; a Prime Brokerage account pitched at institutional clients with enhanced leverage, API access alongside the standard platforms, and team-level relationship coverage; and a Wealth Management account with high deposit requirements, a senior dedicated relationship manager and full crypto access. None of these figures come with a stated dollar minimum in what reached us; the earlier review characterises all four as scaled to the client relationship rather than fixed at account opening.
Who CMB International will and won’t take on
The same earlier review lists CMB International as serving institutional, corporate and high-net-worth clients exclusively, not retail or small traders. On top of that general positioning it records several eligibility conditions: US persons are required to hold accredited investor status before an account can be opened; EU residents may face restrictions connected to MiFID II; clients in countries under UN sanctions or on FATF blacklists face enhanced requirements or an outright prohibition on opening an account; and access for mainland Chinese residents is permitted only within China’s capital control regulations. Cryptocurrency trading (BTC, ETH and USDT, described as running 24/7) is restricted to professional investors, which the earlier review ties to the scope of the SFC’s virtual asset approval it says CMB International received in July 2025.
Funding the account once it’s open
The payment methods the earlier review lists carry conditions of their own rather than a simple list of channels. A bank transfer deposit is treated as same-day only if it lands before 4pm and the sending name matches the account holder; a counter deposit is immediate but requires the client to notify the firm; a bank-securities transfer moves funds immediately but only between accounts that are already linked; an international wire takes one to three business days and may attract SWIFT fees; and withdrawals made online are processed within one business day but require verification through the platform first. None of this touched on a published account-opening form, a document checklist, or a stated KYC procedure.
What we could not check on CMB International’s own site
Every page we attempted to fetch from the firm’s own site that would normally cover this ground, including the client agreement, terms and conditions, account pages and risk disclosure, came back as an empty response on repeated tries. That means the account-opening steps, the verification documents demanded, and the formal eligibility wording above all reached us through the earlier review rather than through a CMB International page we read ourselves, and we have nothing first-hand to set against it. Separately, the firm’s own homepage that we did load carries repeated fraud warnings in Chinese, cautioning visitors against fraudulent sites and logins impersonating CMB International and against criminals using its name to solicit business, alongside a notice about unauthorised use of the CMB International name in securities activity. Anyone starting the account-opening process with this firm is opening it against a background where the firm itself is flagging active impersonation of its channels, which is a reason to confirm the login and application pages in use are genuinely the firm’s own before submitting any verification documents.
Deposits & Withdrawals
CMB International Securities Limited, and the wider group publishing as CMBI (招银国际), gives no first-hand figures for deposits or withdrawals on its own website. We tried the obvious pages directly: fees, pricing, spreads, account terms, client agreement, risk disclosure. Every one of those URLs came back with a body of zero bytes, repeatedly. That means nothing in this section can be sourced to a page we actually read on CMBI’s own site. What follows is either the rail-level detail carried over from the earlier review of this broker, restated in our own words and marked as such, or the absence of anything to cite.
What the earlier review reported about moving money in and out
Our earlier review described five payment rails, none of them carrying a published fee figure. Bank transfer deposits were reported as same-day if submitted before 4pm, with a requirement that the sending account’s name match the CMBI account holder. Counter deposits (paying in over the counter at a branch) were reported as immediate but needing a notification to CMBI first. A bank-securities transfer, moving funds between a linked bank account and the trading account, was reported as immediate but restricted to accounts that are already linked. International wire deposits were reported as taking one to three days, with a note that SWIFT fees may apply, though no amount was given for what those fees actually run to. On the withdrawal side, the earlier review reported only one rail: an online withdrawal processed within one business day once platform verification is complete. It did not report a cost for that withdrawal, a minimum withdrawal size, or a cap on how much can move out in a cycle. None of this reached us from a CMBI page, so treat it as a description of the rails rather than a quote of any published schedule.
Account tiers and what CMB International asks to open one
The earlier review listed four account tiers for CMBI: Individual, Corporate, Prime Brokerage, and Wealth Management. None of the four carries a stated deposit figure. The minimums are reported only as categories: “relationship-based” for Individual, “higher requirements” for Corporate, “institutional” for Prime Brokerage, and “high requirements” for Wealth Management. That vagueness is the earlier review’s characterization, not a number CMBI has published anywhere we could check, and it lines up with the firm positioning itself around a relationship manager rather than a self-serve sign-up flow. The same review noted that CMBI does not advertise blanket negative-balance protection in the way a retail broker typically does, relying instead on client assessment and real-time risk monitoring; again, that is the earlier review’s characterization, not wording found on a CMBI page.
Who the deposit and withdrawal rails are not built for
The earlier review reported that CMBI states it works only with institutions, companies and wealthy individuals, not retail or small traders, which fits with the absence of any published minimum deposit figure a retail applicant could check against their own balance. It also reported restrictions layered on top of that: US persons need accredited-investor status, EU residents may face MiFID II-related restrictions, mainland Chinese residents can only access the firm within China’s capital control rules, and clients from UN-sanctioned or FATF-blacklisted countries meet stricter checks or outright prohibition. Cryptocurrency trading, which CMB International Securities Limited was approved to offer from July 2025 under an SFC virtual asset approval, was reported as limited to professional investors only, so it sits outside the deposit and withdrawal rails a smaller client would ever reach.
Our previous score for this broker was 4 out of 10; this review scores it 5 out of 10. The fees component of that score sits at 2, and the evidence here is why: every fee, pricing and spread page we tried to fetch directly came back empty, so there is no CMBI-sourced cost figure anywhere in this section, and the rail detail that does exist is secondhand and undated. The move from 4 to 5 reflects our current assessment under our criteria, weighted heavily toward the SFC register confirmations set out elsewhere in this review, and is not a claim that CMBI’s deposit or withdrawal terms have changed.
Customer Support
CMB International runs on the same address and phone footprint as China Merchants Bank’s Hong Kong operation, and the contact list is one of the few parts of this review that comes from the firm’s own page rather than our earlier review. The Hong Kong head office is listed at 45, 46 and 39/F, Champion Tower, 3 Garden Road, Central, with a landline at (852) 3900 0888 and a fax at (852) 3761 8788, all per the firm’s about page. The same page lists a Shenzhen office on Shennan Avenue with phone (86755) 8637 8978 and fax (86755) 8637 8959, a Singapore office at 8 Marina View, Asia Square Tower 1, #32-01, with phone (65) 6350 4400 and fax (65) 6244 4374, a Beijing office on Wudinghou Street, and a Shanghai office in the Shanghai Tower on Yincheng Middle Road. The about page also names a dedicated complaints channel, listed there as a complaints channel (投诉渠道), though our evidence does not give a phone number, email or web form for it, only that the link exists.
What we could not verify about CMB International’s support
Every attempted fetch of the firm’s legal, terms, fees, accounts, risk disclosure and platform pages, including client-agreement and contact-style URLs, came back at zero bytes on repeated tries. That means we hold no first-hand account of service level agreements, complaint-handling timelines, response-time commitments or escalation procedures. The account tiers, platform names and support-related claims elsewhere in our evidence, including the relationship-manager structure described below, reached us from our earlier review rather than from a page we fetched ourselves, so treat them as restated, not verified.
Relationship-manager model, as the earlier review described it
The earlier review’s account breakdown describes support as tiered by account type rather than delivered through a single generic help desk. Individual accounts are said to come with a relationship manager, Corporate accounts with a dedicated relationship manager and enhanced research, Prime Brokerage accounts with team coverage and direct research access, and Wealth Management accounts with a senior dedicated relationship manager and premium research. If accurate, that points to a private-banking style of support built around a named contact tied to account tier rather than a shared ticketing queue, but this description is second-hand and we have not read the account documentation ourselves.
Fraud warnings on the firm’s own site
CMB International’s homepage itself carries repeated fraud warnings in Chinese: one reading, in translation, beware of fraudulent sites impersonating CMBI’s official site and login screens, and another warning against criminals impersonating CMBI to commit fraud, alongside a separate clarification notice about people illegally using the CMBI name for securities activities. This is a warning the firm is publishing about its own name being used by scammers, not a statement about the firm’s own conduct, but it is directly relevant to a reader trying to confirm they have reached a genuine CMBI support channel rather than an impersonator.
Regulatory standing behind the contact points
The Hong Kong SFC register confirms four entities under the CMB International name. CMB International Securities Limited holds CE reference AUZ441, licensed for Type 1 and Type 4, Dealing in Securities and Advising on Securities, both shown active, with 6 licensing conditions attached and no public disciplinary action on record. CMB International Futures Limited holds CE reference ACQ651, licensed for Type 2, Dealing in Futures Contracts, active, with no public disciplinary action recorded. CMB International Capital Limited holds CE reference AVM940, licensed for Type 1 and Type 6, Dealing in Securities and Advising on Corporate Finance, active, with 2 licensing conditions and no disciplinary action recorded. CMB International Asset Management Limited holds CE reference AVA101, licensed for Type 1, Type 4 and Type 9, Dealing in Securities, Advising on Securities and Asset Management, active, with 3 licensing conditions and no disciplinary action recorded. A client’s actual point of contact for a dispute would depend on which of these four licensed entities they were onboarded through, since the licences and conditions differ by entity, and our evidence does not identify which support line or office serves which entity specifically. We also searched 1441 warning list entries mirrored from CYSEC, the FCA and the FSC Mauritius, and CMB International appears on none of them, though that check covers only the lists we mirror, not every regulator.
Score
Our previous review scored CMB International 4 out of 10 overall. This review scores it 5 out of 10, on the support criterion specifically 5.3 out of 10. The move is our assessment being restated from current evidence rather than any change in the firm, and the evidence here is mixed in a way that criterion reflects: named offices, phone numbers and a complaints link confirmed direct from the firm’s own about page pull the figure up from the zero-byte state of every other firm document we tried to fetch, while the absence of any verifiable complaint-handling timeline, response commitment or single support contact, combined with relying on the earlier review for the tiered relationship-manager structure, keeps it in the middle of the range rather than higher.
Prohibited Countries
Our previous score for this broker was 4/10. This review scores 5/10. The move reflects our current assessment against the evidence below, including a confirmed SFC entity structure and a clean warning list check, not any change on the firm’s part.
Who CMB International says it will not serve
The evidence we hold for this section comes from our earlier review not from pages we fetched ourselves; every attempted retrieval of CMB International’s own legal, terms, risk disclosure and account pages returned an empty response, so none of the exclusions below could be checked against the firm’s own documentation.
That earlier review reported that CMB International states it works only with institutions, companies and wealthy individuals, which as reported would put retail traders and small individual accounts outside the client base the firm says it targets.
The same earlier review reported restrictions tied to specific jurisdictions and statuses. It described a requirement that US persons hold accredited investor status to access the firm’s services. It described MiFID II related restrictions that may apply to EU residents, without specifying which product lines or under what conditions. It described enhanced requirements or outright prohibitions for countries under UN sanctions or FATF blacklists, again without naming which countries or listing the specific requirements. And it described access for mainland Chinese residents as permitted only within capital control regulations, without specifying what those regulations require in practice.
Cryptocurrency access is narrower than the general client base
Separately from the country and status restrictions above, the earlier review reported that cryptocurrency trading, covering BTC, ETH and USDT on a 24/7 basis, is limited to professional investors, consistent with the scope of the SFC virtual asset approval the review associated with a July 2025 launch. That is a product level restriction on top of whatever country or client type exclusions apply elsewhere.
What we could not verify
None of the exclusions above carries a document name, a clause number or a list of named countries in the material available to us. We searched the SFC’s Public Register of Licensed Persons and Registered Institutions directly and confirmed active licences for four CMB International entities: CMB International Securities Limited (CE reference AUZ441, Type 1 and Type 4), CMB International Futures Limited (CE reference ACQ651, Type 2), CMB International Capital Limited (CE reference AVM940, Type 1 and Type 6) and CMB International Asset Management Limited (CE reference AVA101, Type 1, Type 4 and Type 9), each shown as active with no public disciplinary action recorded. That register confirms who is licensed to deal and advise, but it does not publish a list of excluded countries or client categories, so it cannot corroborate or contradict what the earlier review reported here. We also searched 1,441 warning list entries mirrored from CYSEC, the FCA and FSC Mauritius, and CMB International appears on none of them, which is a clean result on the lists we mirror but says nothing about which countries the firm will or will not onboard.
We note, separately, that CMB International’s own homepage carries repeated fraud warning banners telling visitors to be alert to fraudulent sites impersonating its official site and login, and to criminals using the CMB International name to commit fraud. That is a warning the firm itself is publishing about impersonation, not a statement about who the firm will serve, but readers checking country or eligibility claims against what looks like a CMB International channel should be aware it exists.
Conclusion
CMB International scores 5 out of 10 overall, up from the 4 out of 10 this catalogue previously gave it. The move follows from a fuller regulatory check, not from any change at the firm. The SFC register confirms four separate CMBI entities under active licences, CMB International Securities Limited on CE reference AUZ441 for Type 1 and Type 4, CMB International Futures Limited on ACQ651 for Type 2, CMB International Capital Limited on AVM940 for Type 1 and Type 6, and CMB International Asset Management Limited on AVA101 for Type 1, Type 4 and Type 9, each carrying licensing conditions and none showing public disciplinary action. That confirmed, multi-entity SFC record is what pulls the regulation score to 7.8. It is also, on its own, the strongest part of this review.
Where CMB International falls down
The fees score of 2 and the platform score of 4.5 both trace back to the same problem: we could not read the firm’s own terms. Every attempted fetch of a legal, terms, client agreement, fee, pricing, spread, risk disclosure or platform page on CMBI’s site came back as zero bytes. That means no fee schedule, no contract terms and no platform specification could be verified first hand. Everything on pricing, accounts and platforms in this review comes from our earlier review restated in our own words rather than quoted, because we never read the documents it describes.
On the basis of our earlier review, CMBI offers four account tiers, Individual, Corporate, Prime Brokerage and Wealth Management, each described as relationship based rather than priced on a published schedule, and three platforms, the Yat Lung Global mobile app, SP Trader for professional and algorithmic use, and Multicharts for quantitative strategy work. None of that is checkable against a CMBI page, because no such page loaded. A reader who wants an actual cost figure or a platform specification will not find one in what we could retrieve.
Licence claims that could not be checked
Beyond the four confirmed SFC entities, the material from our earlier review also names a Money Lenders License, an HKMA registration, a CSRC RQFII qualification and Stock Connect programme access, plus a claim of SFC authorisation with no entity or licence number attached. None of these carry a register entry we hold or a licence number to look up, so each is marked not checked rather than confirmed or false. That is a gap in what was published or in what we read, not a finding about the firm one way or the other.
Support channels and the warning list
The firm’s about page lists phone, fax and street addresses for Hong Kong, Shenzhen, Singapore, Beijing and Shanghai, along with a named complaints channel, which is a wider footprint than many brokers in this catalogue publish. That breadth of contact points is reflected in the support score of 5.3. Separately, we searched 1,441 warning list entries mirrored from CySEC, the FCA and the FSC Mauritius, running a positive control against a known listed firm first so an empty result means absence rather than a broken search, and CMB International matched none of them. That covers only the three lists we mirror, not every regulator worldwide, so it rules out those three lists and nothing more.
One thing worth flagging directly: CMBI’s own homepage carries active fraud warning banners telling visitors to watch for sites and login screens impersonating CMBI, and a separate notice about people illegally using the CMBI name for securities activity. That is the firm warning about impersonation of itself, not a finding against it, but anyone contacting CMBI should confirm they are on a genuine CMBI channel before doing so.
CMB International holds confirmed, active SFC licences across four Hong Kong entities and a clean result on the three warning lists we checked, but its own site returned no readable terms, fees or platform pages, leaving the pricing and platform detail unverified. TrueBroker scores CMB International 5 out of 10.
What we saw
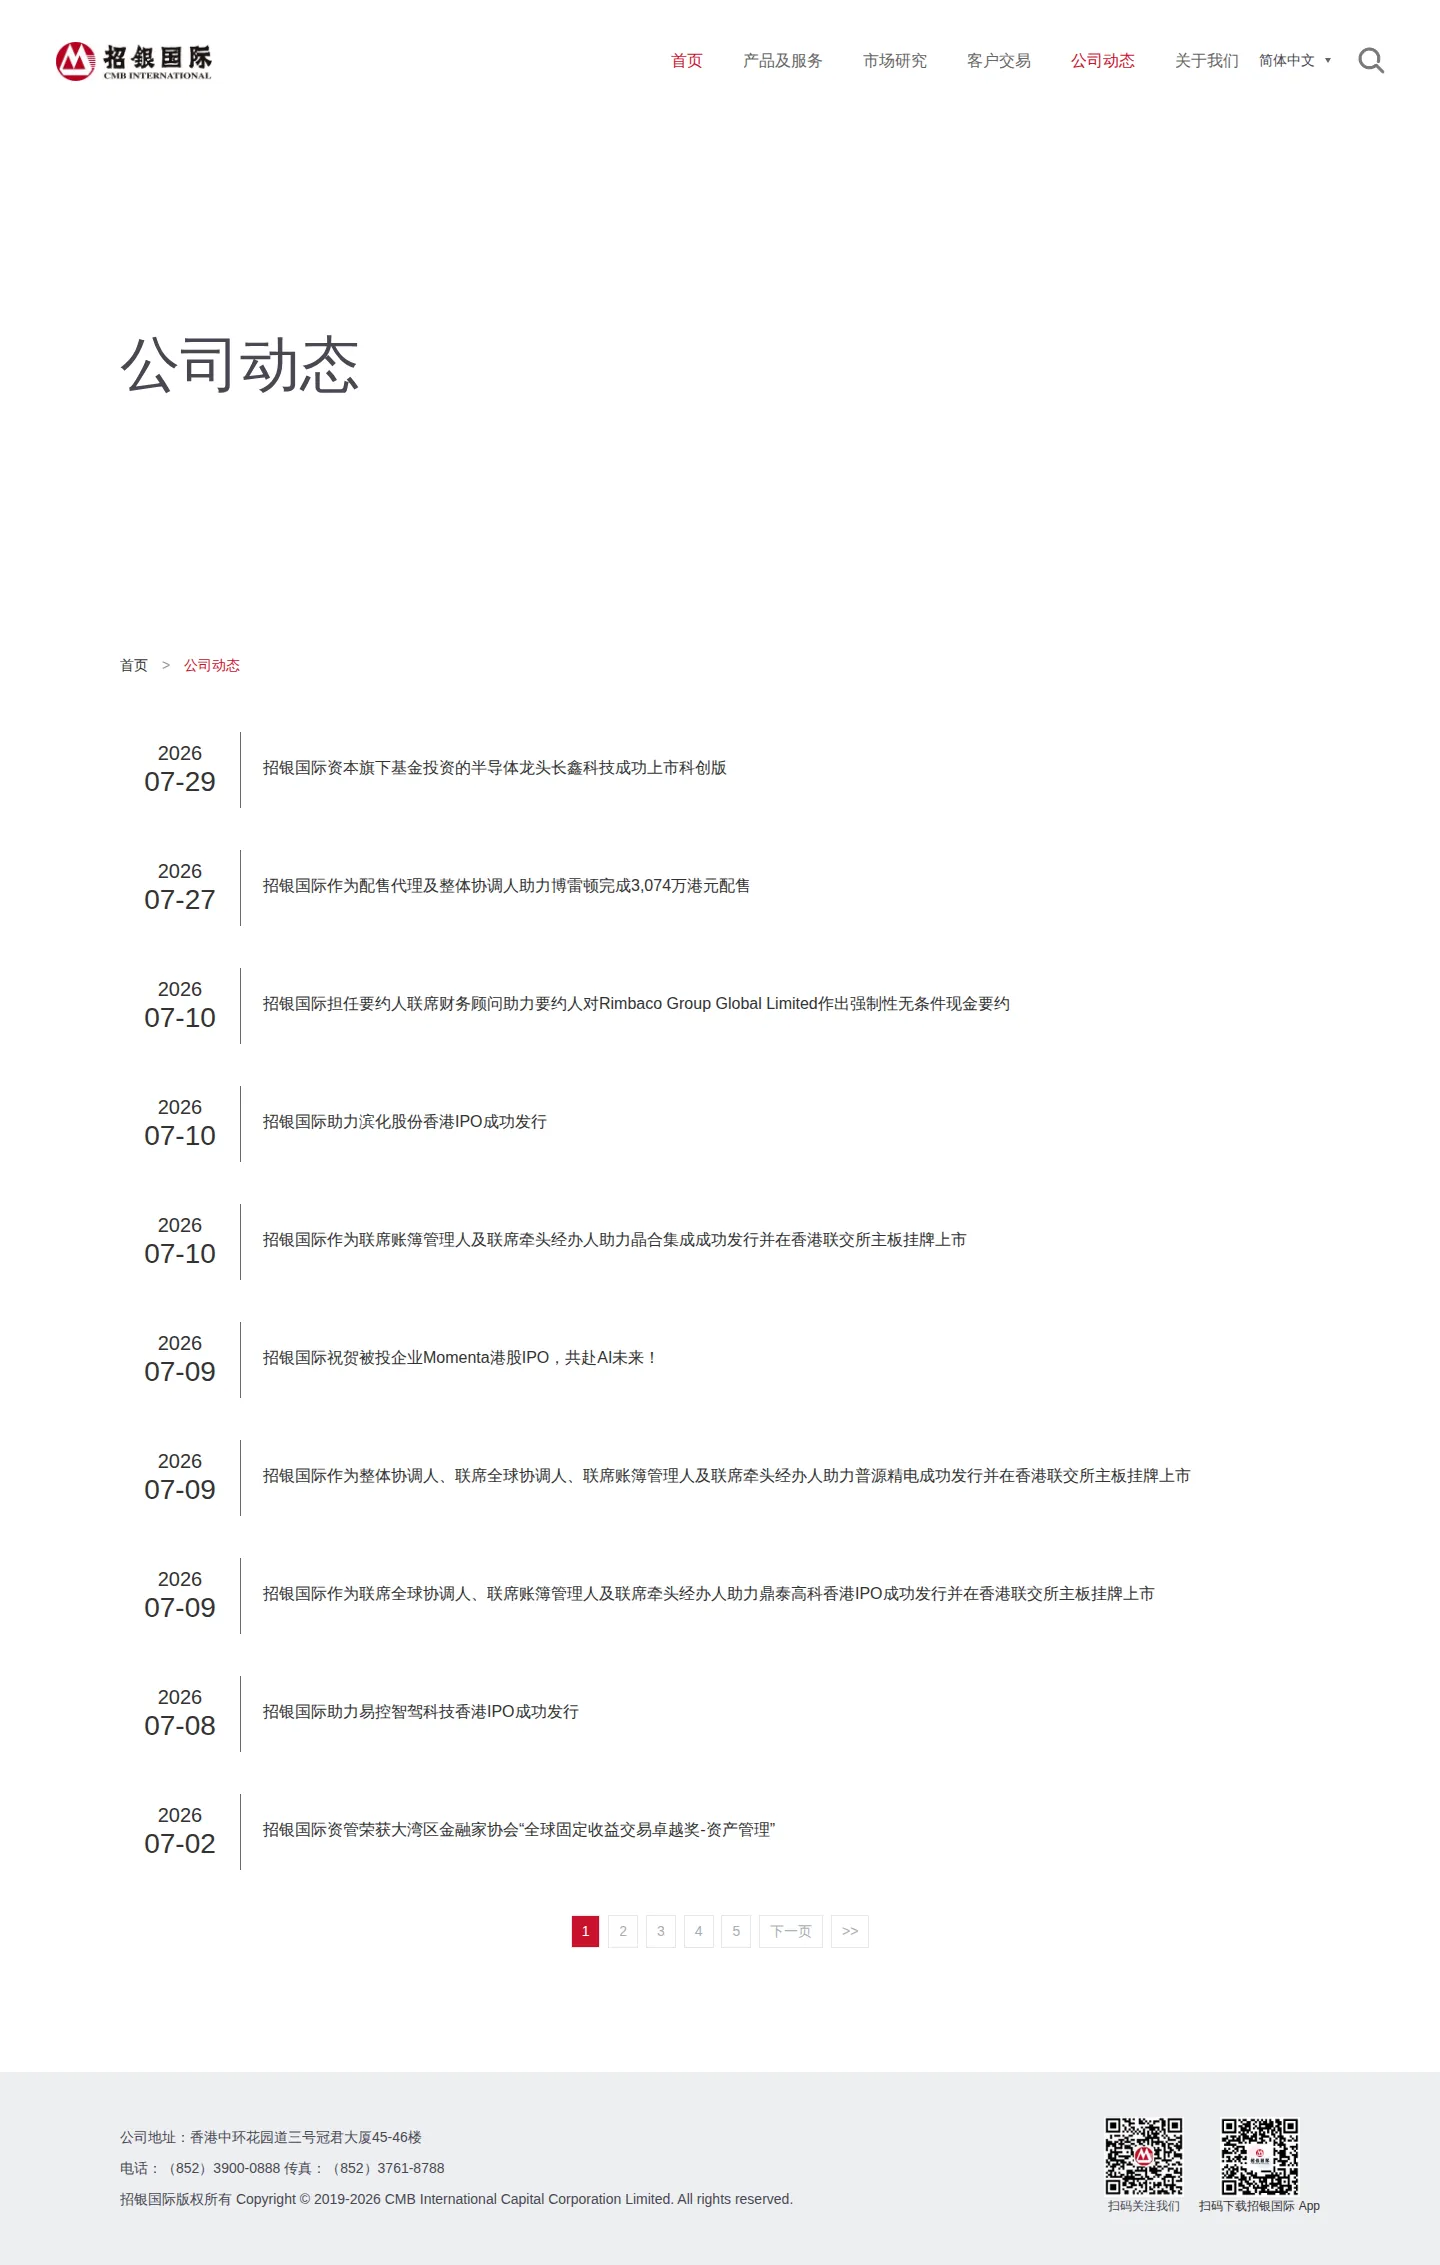
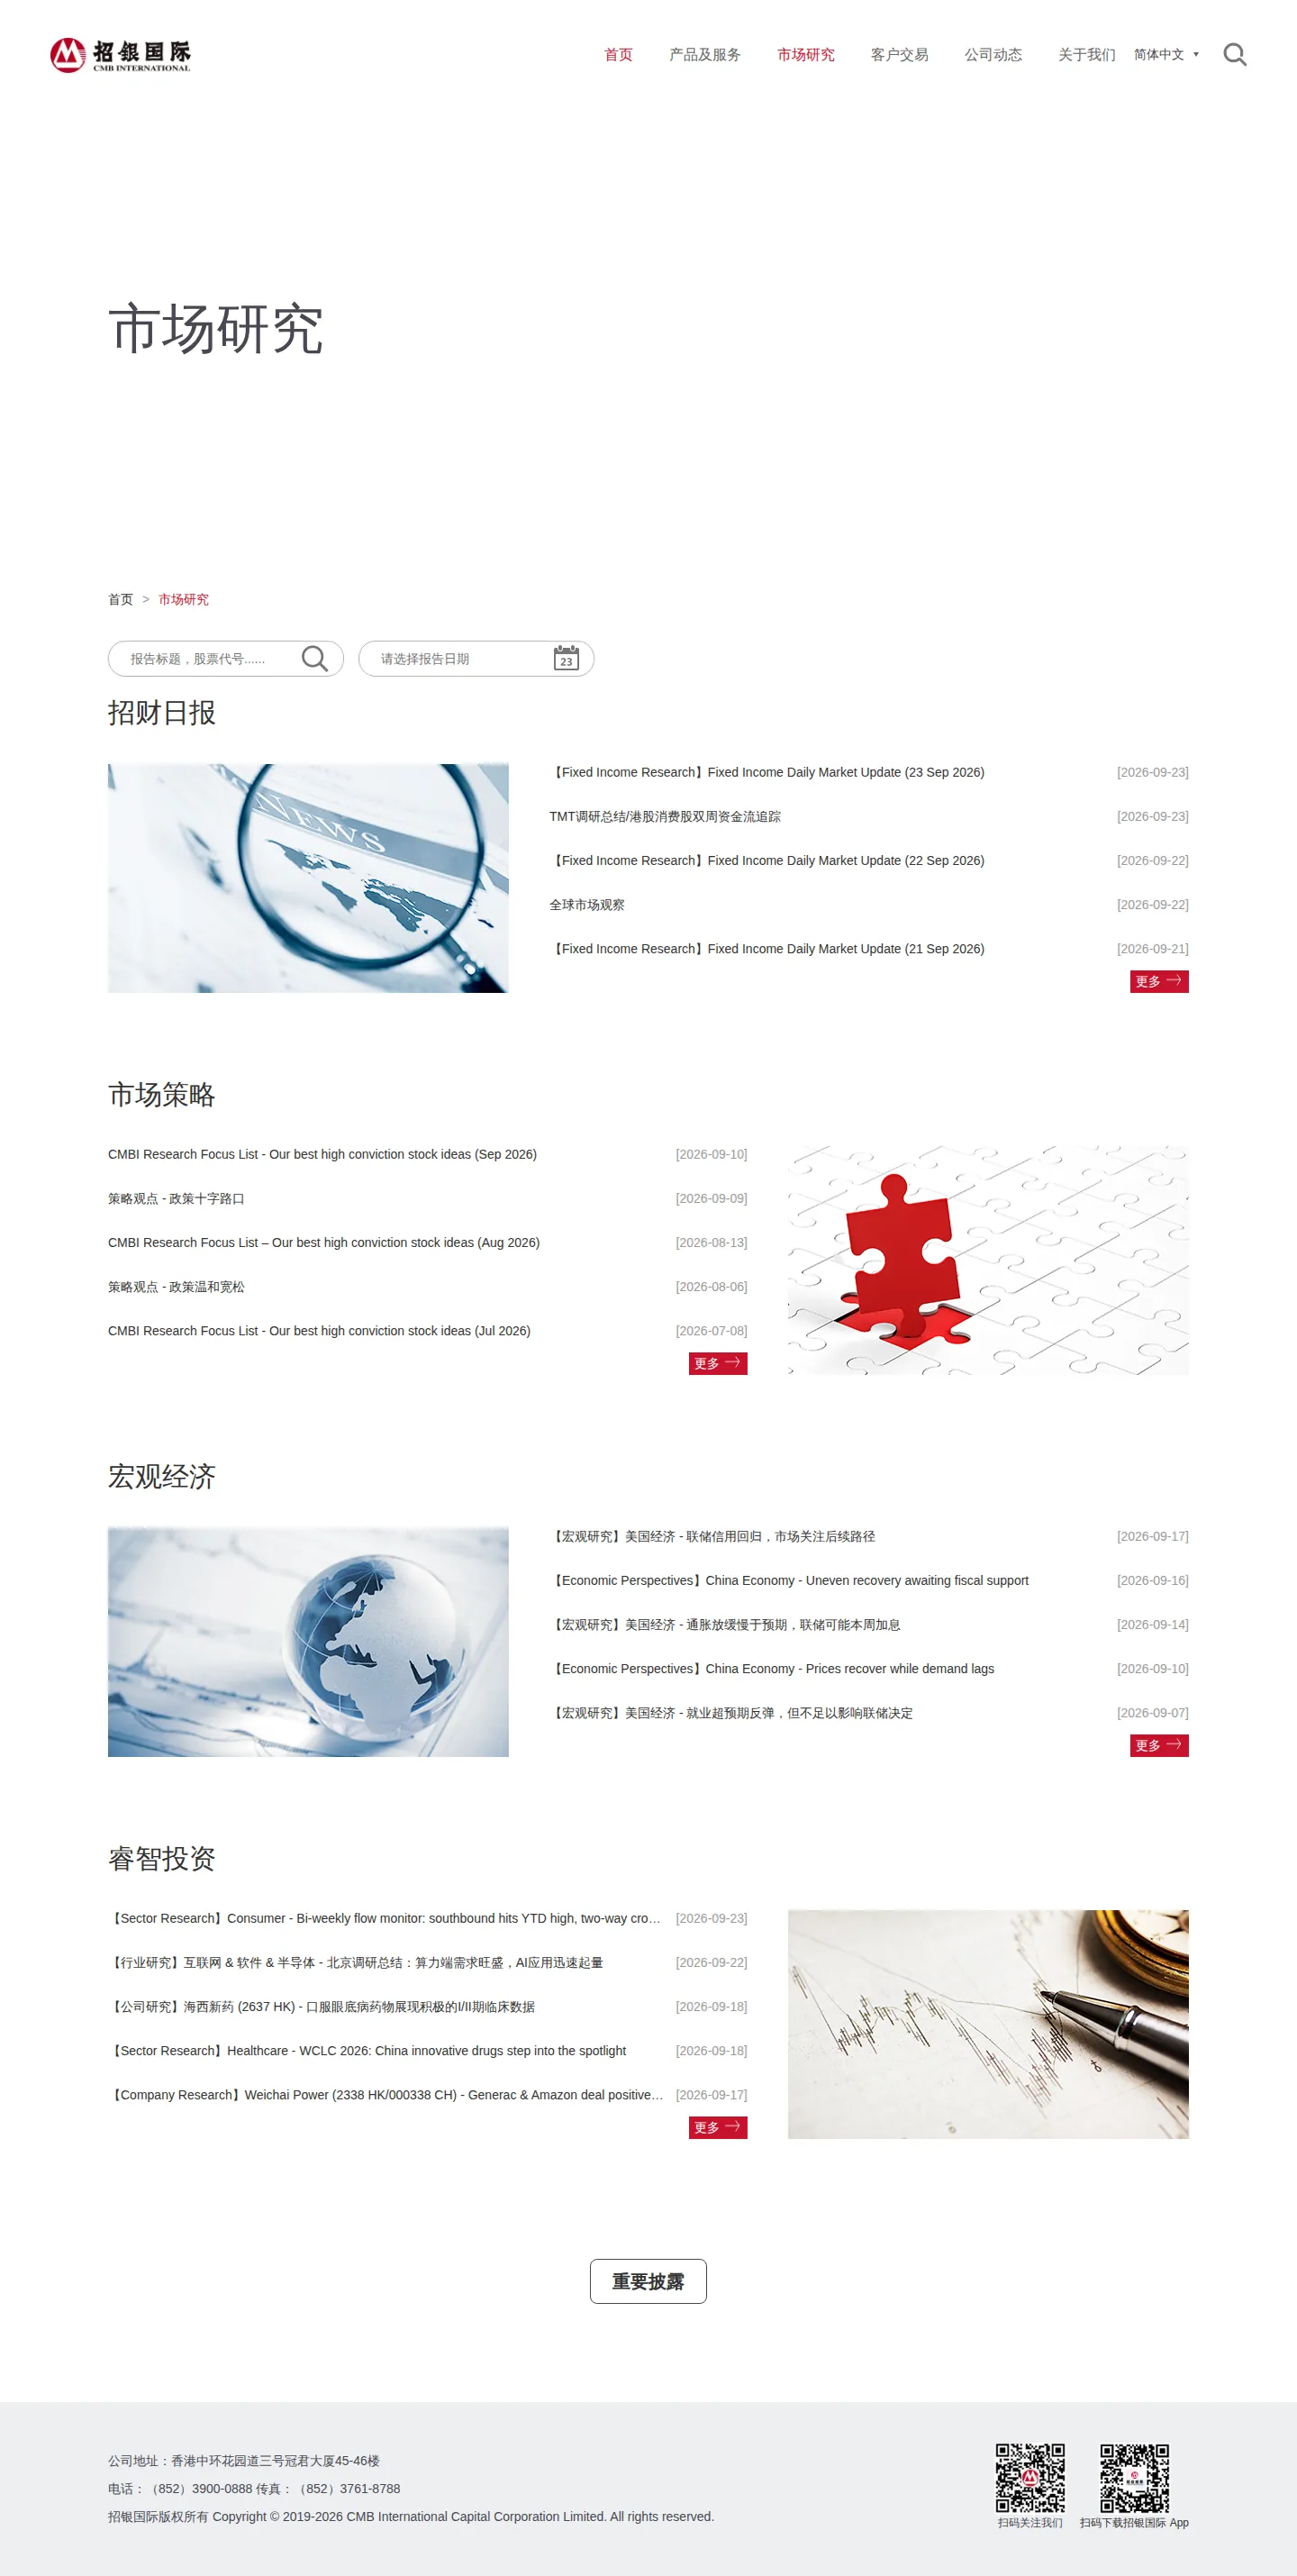
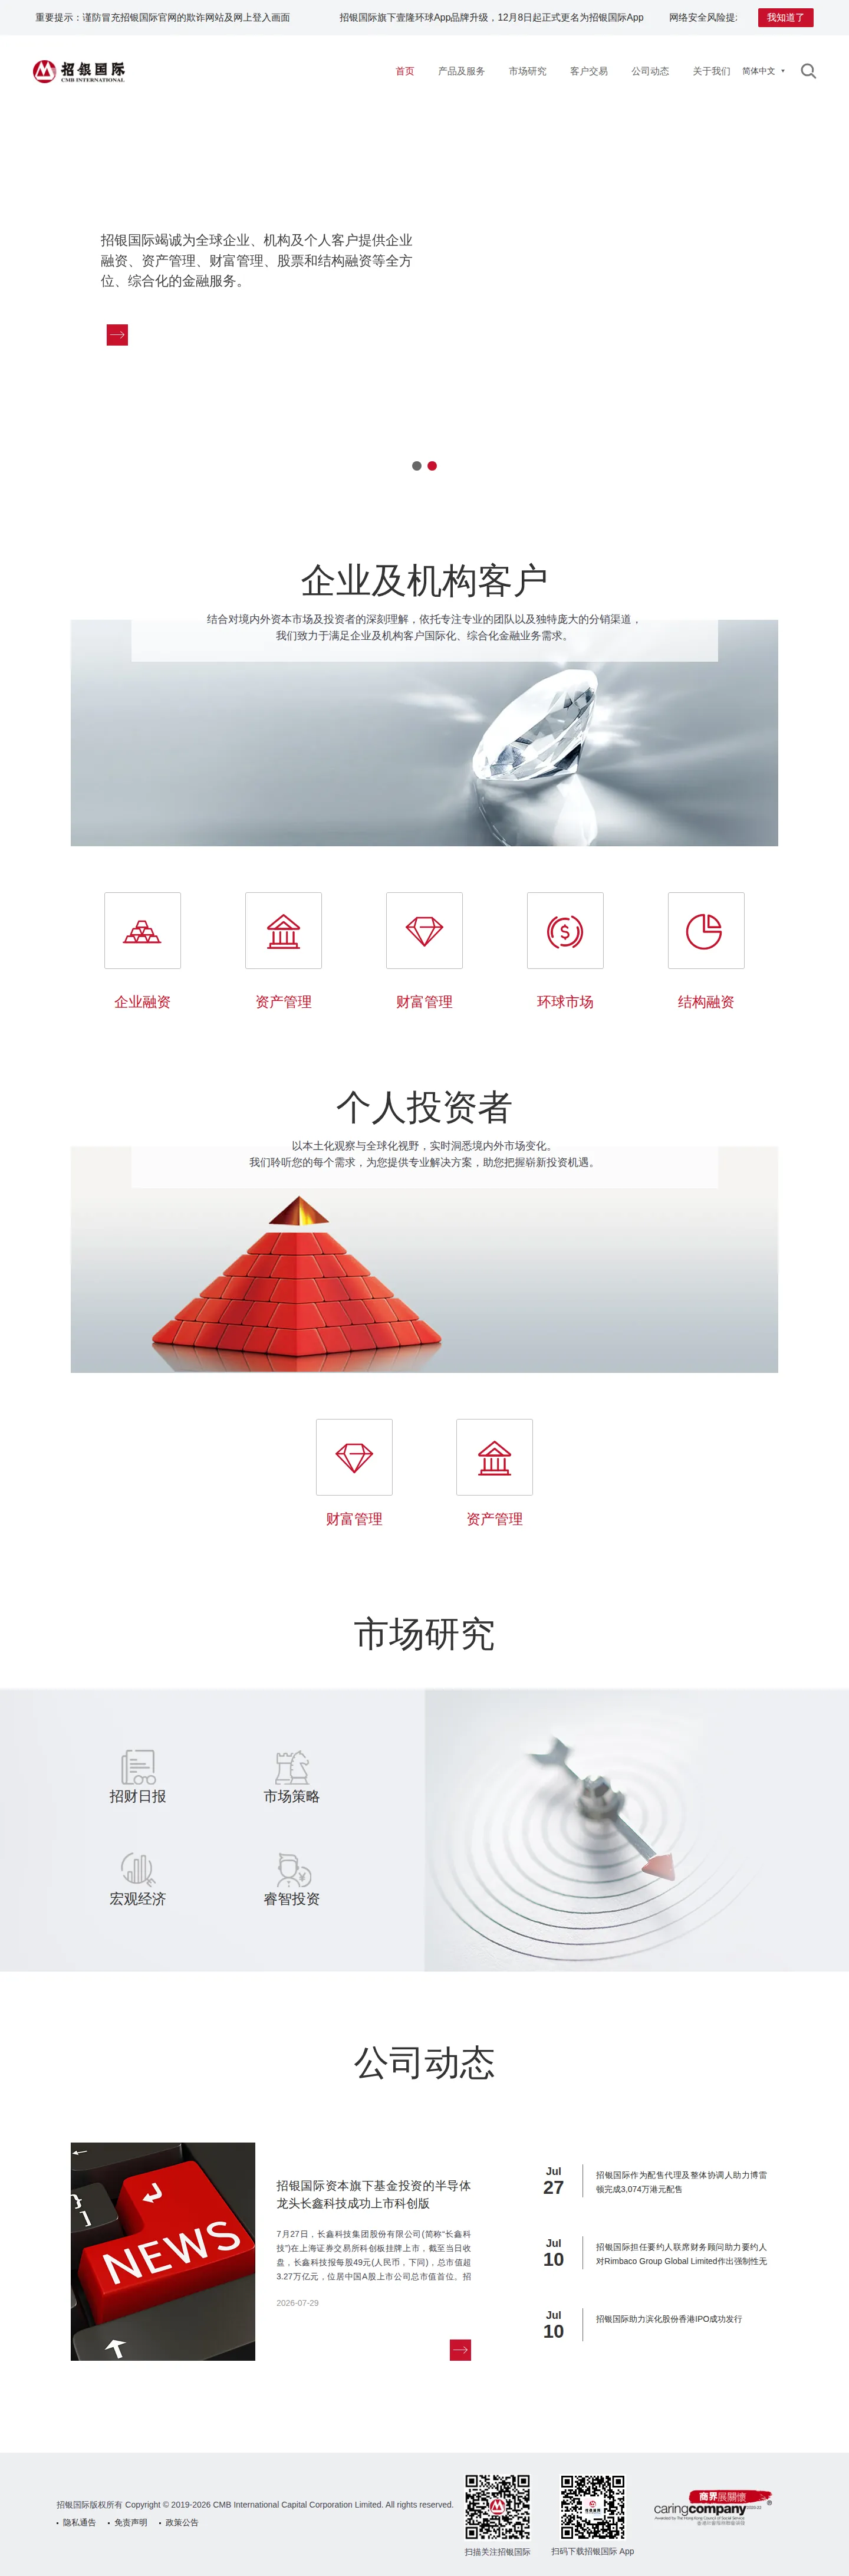
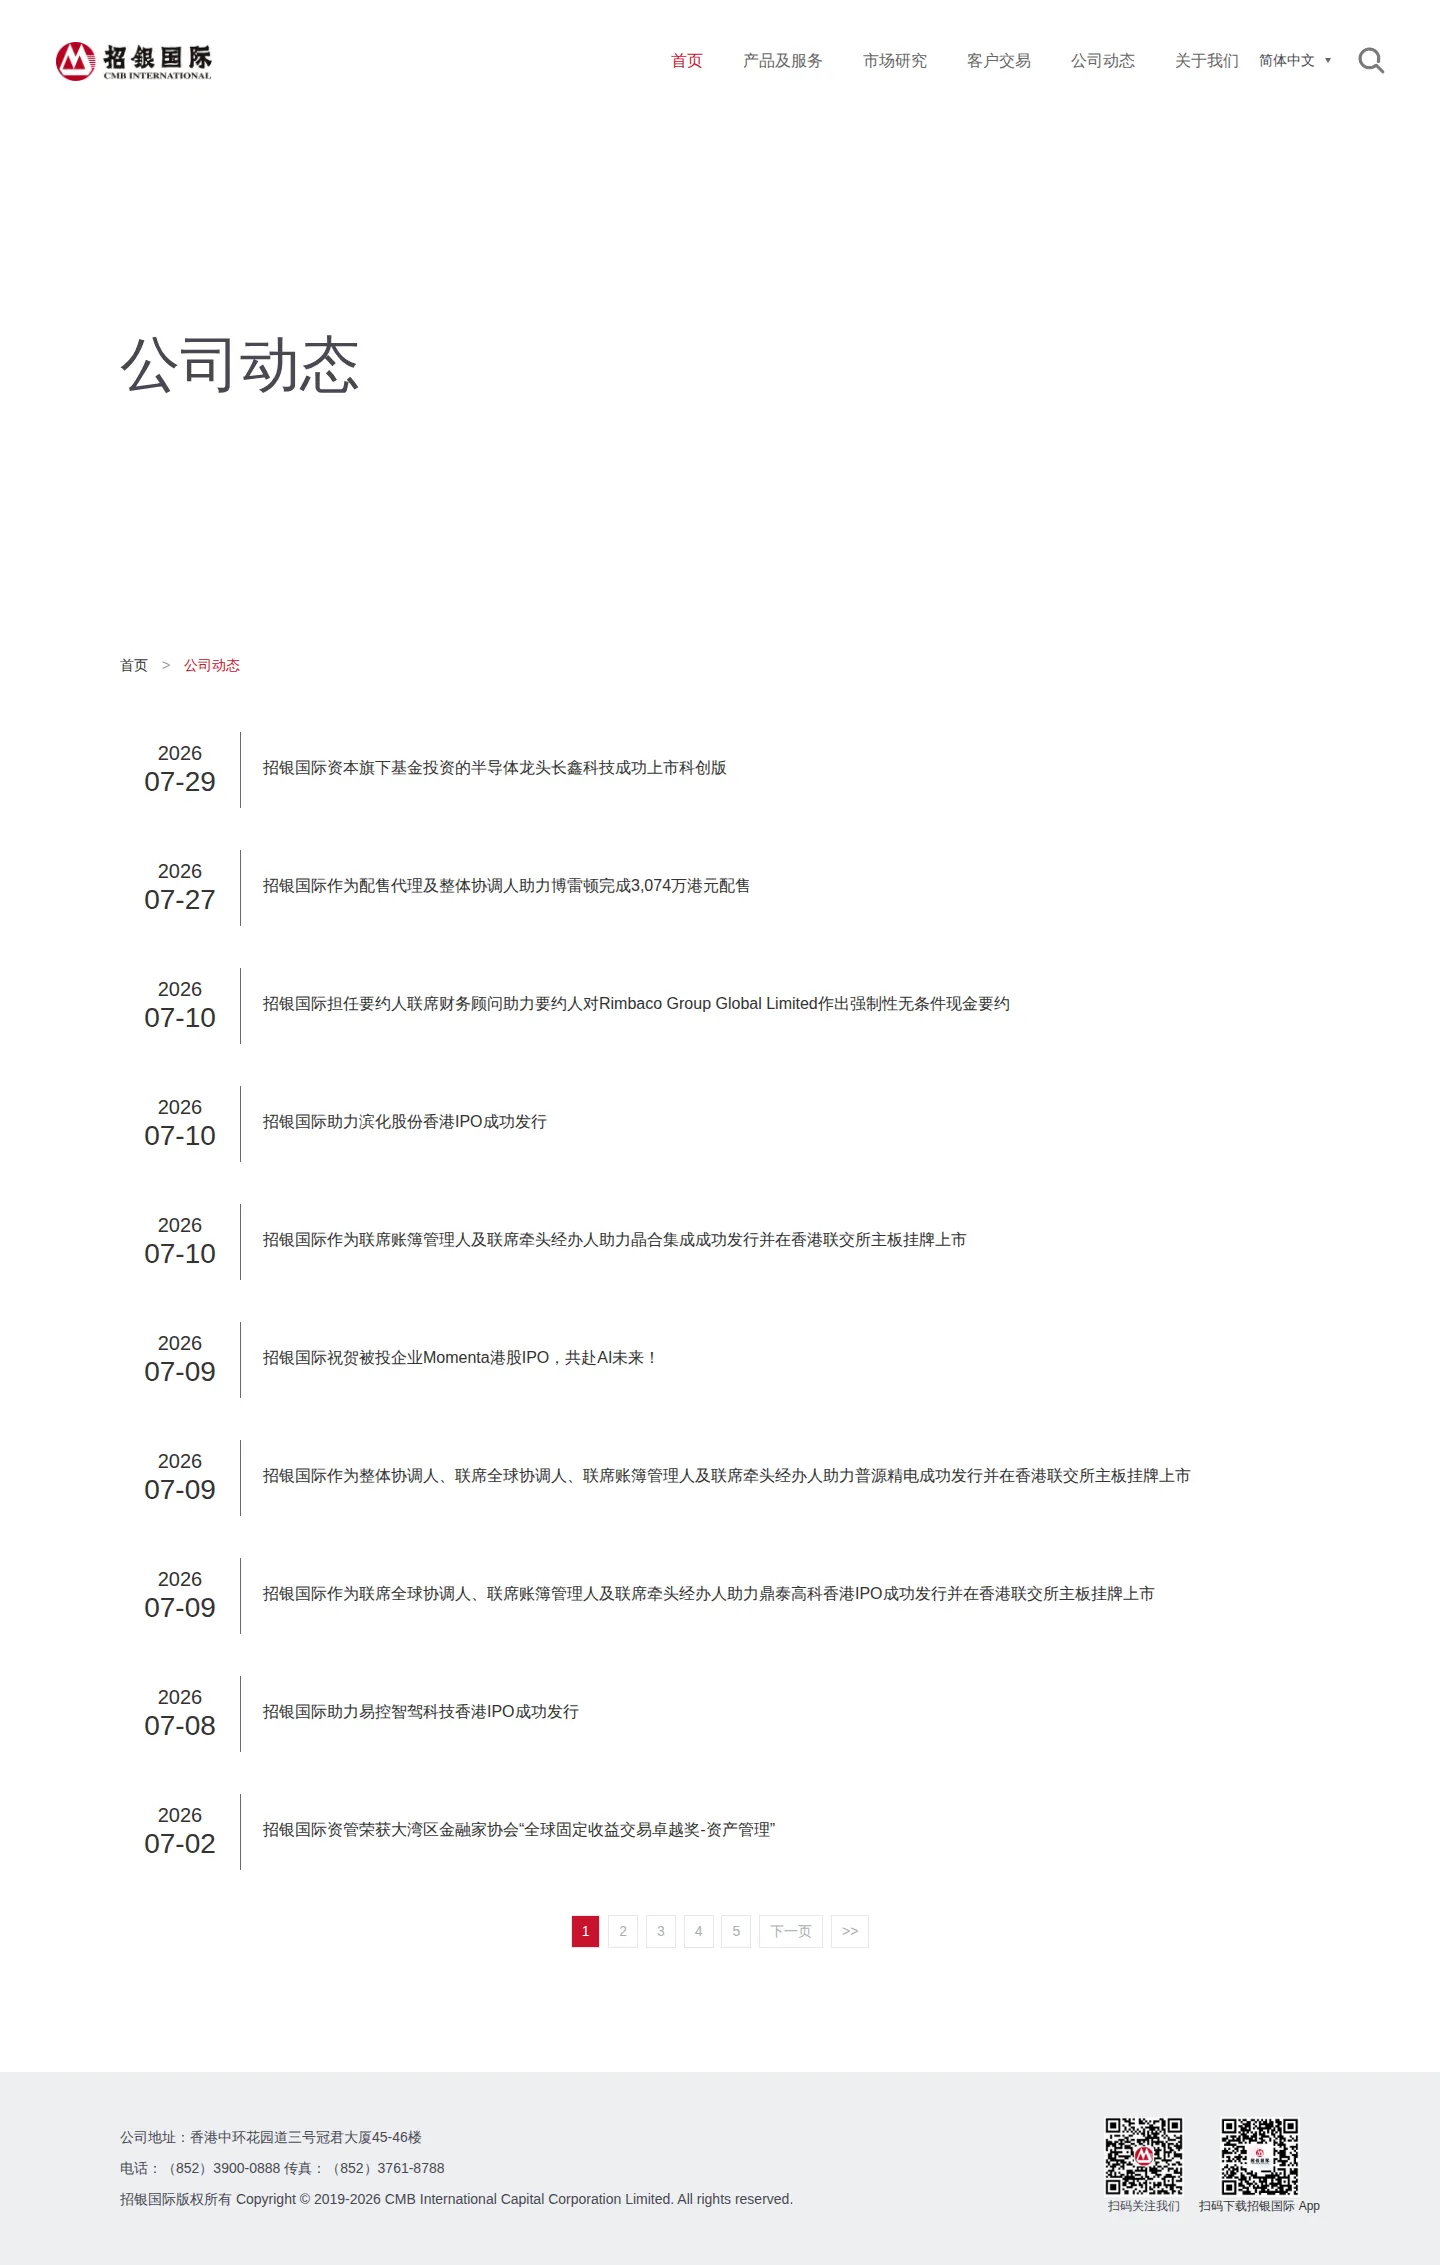
Pages captured from CMB International’s own site when this review was written. Brokers change their terms; these are what we read.
Score history
Recomputed daily; every move is on the record. The current score is always the latest row.
| Date | Score | Move |
|---|---|---|
| 2026-10-10 | 5.0 | ▲ |
| 2026-07-25 | 4.0 | ▲ |
| 2026-07-18 | 3.9 | ▼ |
| 2026-07-11 | 4.0 | · |
FAQ
Is CMB International regulated?
Yes. Four operating entities, Securities, Futures, Capital and Asset Management, each hold an active Hong Kong SFC licence, and none carries public disciplinary action.
Who owns CMB International?
Its ownership chain runs cleanly up to China Merchants Bank, a listed parent company.
What does CMB International charge in fees?
No published cost of trading was found on the broker’s own pages or documents.
What platforms does CMB International offer?
It offers professional connectivity through SP Trader and Multicharts.
How can I contact CMB International?
A published phone number is confirmed, though no other support channel is listed.
What do reviews say about CMB International?
It has a blended rating of 3.51 stars across 47 ratings.
How this review works
Track CMB International live: score moves and red notices, in your pocket.