STOCK · CHECKED 10 OCT 2026
CGSI review.
Hong Kong futures dealer with a confirmed SFC licence and multiple own trading platforms
RISKY
OUT OF 10
CGSI operates as China Galaxy International Futures (Hong Kong) Co., Limited, holding SFC licence AYH772 for dealing in futures, confirmed active with no disciplinary record. It runs several own-brand trading platforms, including the institutional Galaxy Global Trading Terminals. The main gap is on cost transparency: no EURUSD spread is published for a retail-accessible account, so trading costs can't be verified.
Each criterion is scored 1 to 10 from primary sources. The overall score is their unweighted mean. How scoring works.
| Founded | 2011 |
|---|---|
| Headquarters | HK |
| Minimum deposit | Not stated |
| Account opening | 1-3 |
- SFC licence AYH772 confirmed active for China Galaxy International Futures (Hong Kong)
- Runs its own web platform, mobile app, and desktop client alongside a futures APK
- Offers Galaxy Global Trading Terminals, a flagship institutional desktop platform
- Reachable by both email and a published phone number
- No EURUSD spread published for a retail-accessible account, so no round-turn cost
- Blended review score of 3.33 stars from only 10 ratings
- Claims Type 1,4,6,9 licences for the holding company but gives no CE reference
- SFC compensation cap is 500,000 HKD and leverage capped at 20:1 on major FX
- AAStocks app is mainly market information, not a primary execution platform
- SFC adjudicator binds the firm but charges the claimant to use it
Overview
TrueBroker is a free broker safety checker, and this page is our review of CGSI, scored 5.1 out of 10 across regulation, fees, platform, support and reviews. Our previous review of this broker scored it 4 out of 10; this rewrite moves the score to 5.1, an assessment we are making now against current evidence, not a claim that the firm itself has changed. The move is driven mainly by two things we found this time: a confirmed Hong Kong SFC licence for one of the group’s subsidiaries, and a clean result on our own warning list search, both described below.
CGSI trades under a group structure headed by China Galaxy Securities Co., Ltd. in China. According to the firm’s UAE about page, its Chinese name is China Galaxy Securities Co., Ltd. (中國銀河證券股份有限公司). It was formed by merging the securities arms of several trust investment companies, entities that had each previously been wholly owned by the Industrial and Commercial Bank of China, China Agricultural Bank, Bank of China, China Construction Bank and China Life Insurance. Its first wholly owned subsidiary outside mainland China, CGS International Holdings Limited (中國銀河國際控股有限公司), was registered in Hong Kong in February 2011. The subsidiaries below that Hong Kong arm, including China Galaxy International Futures (Hong Kong) Co., Limited and China Galaxy International Securities (Hong Kong) Co., Limited, are the focus of this review.
Overview Table
| Headquarters | No street address is given. The firm’s UAE about page notes that its international holding arm, CGS International Holdings Limited, was registered in Hong Kong in February 2011. |
| Established | Parent company China Galaxy Securities Co., Ltd. has no publicly listed founding date; its Hong Kong holding arm, however, was registered in February 2011 |
| Countries Served | Not stated |
| Regulated By | Securities and Futures Commission (Hong Kong); only one subsidiary is confirmed on the register, covered in more detail in the Regulation section below |
| Minimum Deposit | None of the firm’s five published account pages lists a minimum deposit figure |
| Maximum Leverage | Not stated |
| Total Instruments | No aggregate total is given; the instrument categories on offer span Hong Kong and China A-share stocks, 140+ futures and options products, bonds, mutual funds, structured products, and an insurance category listed in the site’s navigation menu |
| Platforms | SPTrader Pro, Galaxy Global Trading Terminals, Soft Token, AAStocks |
| Customer Support | Phone support, email support and a complaints hotline are listed on the firm’s contact page; the Support section below goes into more detail |
| Languages | Not stated |
Facts List
- This review gives CGSI a score of 5.1 out of 10, up from the 4 out of 10 our previous review gave it; that shift reflects newly gathered evidence rather than any change on the firm’s part.
- China Galaxy International Futures (Hong Kong) Co., Limited holds CE reference AYH772 on the Hong Kong SFC Public Register of Licensed Persons and Registered Institutions, licensed for Type 2 (Dealing in Futures Contracts), shown as active, with no public disciplinary action recorded against it.
- Four other SFC licence claims tied to “CGS International Holdings Limited” (Types 1, 4, 6 and 9) could not be checked against the register because the claims quote no CE reference and a name search for that exact corporate name returned no single match; that is a gap in the claim or in our matching, not a finding about the firm.
- We searched 1,441 warning list entries mirrored from CYSEC, the FCA and FSC Mauritius, and this firm appears on none of them, a clean result that covers only the lists we mirror rather than every regulator worldwide.
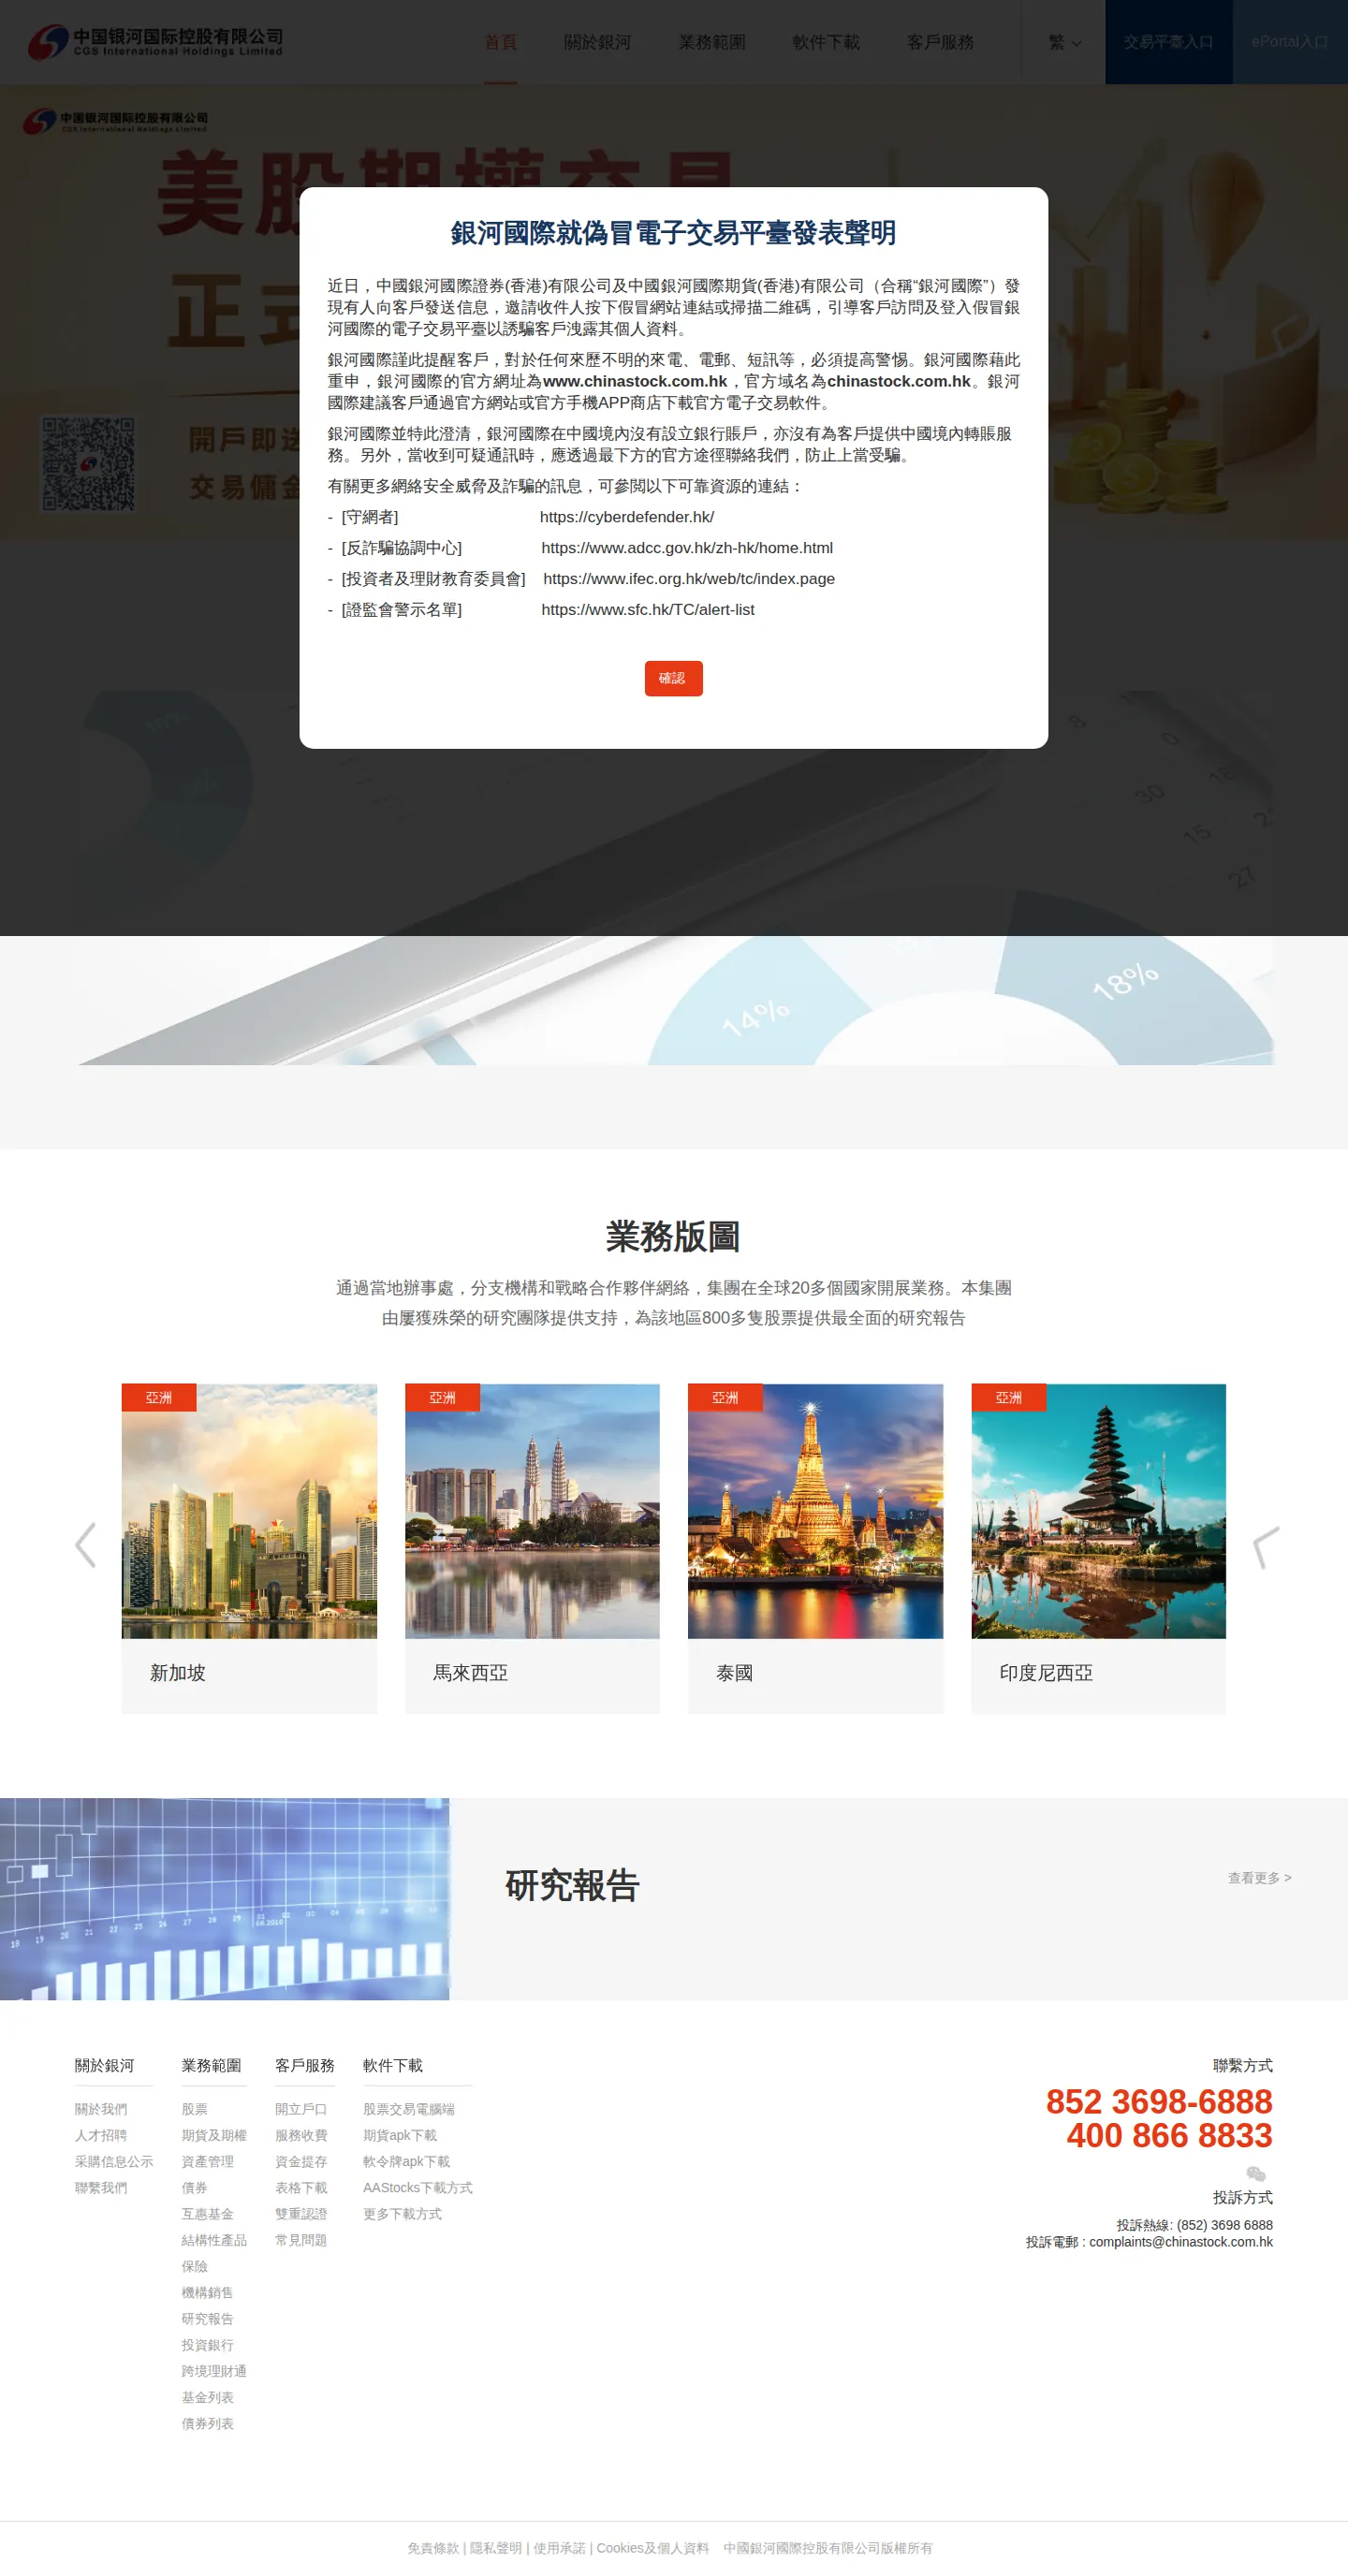
- The firm’s own root page, fetched identically across ten country exits, carries an active warning that fraudsters send messages with fake links or QR codes leading to counterfeit versions of its trading platform, and states the firm holds no bank accounts within mainland China and provides no mainland China transfer service.
- The firm publishes dedicated fee schedule pages for securities, global stock, Hong Kong futures and options, global futures, and stock options fees, but none of the pages we fetched carried specific spread, commission or per lot figures.
- The one specific fee we did find on the firm’s own fee page is a bank confirmation retrieval charge of HKD 100 (港幣一百元正), billed when the firm has to request deposit confirmation records from a client’s bank, a process the page says takes about 1 to 7 business days.
- China Galaxy Securities Co., Ltd. trades on the Hong Kong Stock Exchange under code 06881.HK, a listing code rather than a financial services licence; we hold no register entry for the Hong Kong Stock Exchange, so this has not been checked against a public register.
- None of the five account types described, Securities Cash, Securities Margin, Futures, Stock Options and Electronic Trading, states a minimum deposit figure.
- The firm does not offer MetaTrader 4 or MetaTrader 5, relying instead on its four proprietary platforms, and our earlier review it draws on describes the firm as offering no forex, cryptocurrency or Western commodity trading, focused instead on Hong Kong and China securities, Asian derivatives and fixed income.
What CGSI actually is
The name covers a layered group rather than one licensed entity. China Galaxy Securities Co., Ltd., the mainland Chinese parent, carries listing code 06881.HK on the Hong Kong Stock Exchange. Its Hong Kong holding arm, CGS International Holdings Limited, was registered in Hong Kong in February 2011 and itself sits above a further set of subsidiaries: China Galaxy International Futures (Hong Kong) Co., Limited, China Galaxy International Securities (Hong Kong) Co., Limited, an asset management subsidiary, an investment subsidiary, a financial products subsidiary, and securities subsidiaries in Singapore and Malaysia, all named in the firm’s UAE about page. Of that whole structure, the one entity we could confirm on a public regulator record is China Galaxy International Futures (Hong Kong) Co., Limited, licensed by the Hong Kong SFC under CE reference AYH772 for Type 2, dealing in futures contracts. The broader claim that CGS International Holdings Limited itself holds Types 1, 4, 6 and 9 could not be checked, because the claim carries no CE reference and the register’s name search did not return a single matching corporation for that name.
The single most important thing to know before using CGSI
The firm’s own root page carries a standing fraud warning, fetched the same way across ten different country exits: it tells visitors that scammers are circulating fake links and QR codes that lead to counterfeit copies of its trading platform to steal personal data, and it states plainly that the firm holds no bank accounts within mainland China and offers no mainland China transfer service. Anyone contacted about a China Galaxy or CGSI account through an unsolicited message, especially one asking for a mainland China bank transfer, should treat that as inconsistent with what the firm itself publishes.
Where the evidence runs out
The firm’s fee schedule pages exist under several separate titles, securities fees, global stock fees, Hong Kong futures and options fees, global futures fees, and stock options fees, but none of the pages fetched for this review carried a spread, commission or per lot figure for any account. The one concrete charge we found was a HKD 100 fee for retrieving bank deposit confirmation records when a client cannot supply valid proof of deposit themselves, described on the firm’s own fee page as taking about 1 to 7 business days. That gap in published trading cost figures is reflected in the fees score of 3 out of 10.
Key Takeaways
Our previous review of CGSI scored it 4/10; this review scores it 5.1/10. That is a change in our own assessment, not a claim that the firm has gotten better or worse. The criteria and the evidence base both changed: this pass rests on a direct SFC register check and a warning-list search that the earlier score did not have, and those checks land unevenly, pulling regulation to 5.6, support to 5.3 and platform to 6.6 while fees sits at 3 and reviews at 4.8, for the 5.1 overall.
What the SFC register actually confirms for CGSI
- The Hong Kong SFC Public Register of Licensed Persons and Registered Institutions confirms one specific licence: China Galaxy International Futures (Hong Kong) Co., Limited holds CE reference AYH772 for Type 2 (Dealing in Futures Contracts), shown as active, with no public disciplinary action recorded against it.
- The broader claim that “CGS International Holdings Limited” is “Fully Regulated and Compliant” across Types 1, 2, 4, 6 and 9, and the parallel claim naming a licensed entity in Chinese as holding those same licence types, could not be checked: neither claim quotes a CE reference, and the SFC register’s name search returned no single corporation matching either name. That is a gap in the claim or in our matching, not a finding that the licences do not exist.
- The Hong Kong Stock Exchange listing code 06881.HK, cited for both the parent China Galaxy Securities Co., Ltd. and for China Galaxy International Holdings Limited (中國銀河國際控股有限公司), is a stock-market listing code rather than a financial-services licence, and we hold no register entry for the Hong Kong Stock Exchange, so this number is also unchecked.
- We searched 1,441 warning-list entries mirrored from CYSEC, the FCA and the FSC Mauritius, and CGSI matches none of them. That covers only the three regulators we mirror, not a global sweep, but it is a clean result we can actually stand behind.
What CGSI charges, and what we could not find
- CGSI publishes separate fee-schedule pages for securities, global stocks, Hong Kong futures and options, global futures, and stock options, but none of the fetched pages gave a spread, commission or per-lot figure for any of them. That is silence in the pages we fetched, not a claim that CGSI charges nothing to trade.
- The one figure we could confirm is a HKD 100 bank confirmation retrieval fee, charged when a client cannot supply valid deposit proof and the firm has to request the confirmation from the client’s bank itself, a process the firm’s own fee page says takes about one to seven business days.
- The firm’s eDDA direct debit service is described as free, with 24/7 availability and about five minutes to credit, but it is limited to securities accounts.
- Deposit by FPS (Faster Payment System) is restricted to securities and stock-options accounts and is not accepted for futures accounts, per the firm’s own fee page.
- None of the five account types listed, Securities Cash, Securities Margin, Futures, Stock Options and Electronic Trading, carries a stated minimum deposit in the material we reviewed.
Platform and product scope
- CGSI runs four proprietary tools rather than MetaTrader 4 or MetaTrader 5: SPTrader Pro as the mobile app, Galaxy Global Trading Terminals as the institutional-grade desktop platform, a Soft Token app for two-factor authentication with basic trading built in, and AAStocks as a view-only market-data feed.
- Coverage runs to Hong Kong and China A-share equities, more than 140 futures and options contracts, Hong Kong and China government and corporate bonds, mutual funds and structured products. Forex, cryptocurrency and Western commodities are not part of the offering.
What the firm’s own site says to watch for
- CGSI’s root page carries a standing warning that fraudsters send messages inviting people to click fake links or scan QR codes leading to counterfeit versions of its trading platform to steal personal data, and states the firm holds no bank accounts within mainland China and offers no mainland China transfer service.
- Support channels confirmed on that page include a customer service line at (852) 3698 6750 / 400 866 8833, a general contact line at 852 3698-6888 / 400 866 8833, a complaints hotline at (852) 3698 6888, and separate emails for customer service (cs@chinastock.com.hk) and complaints (complaints@chinastock.com.hk). A WhatsApp number, (852) 9092-1328, is stated to be for deposit-notification follow-up only, not general support.
- A restricted-country list could not be found on the homepage, legal, terms or legal-documents pages when checked via an Indonesian exit, and an earlier version of this material had circulated a prohibited-country list that could not be traced to anything CGSI publishes; that list should not be relied on for eligibility.
Licenses & Regulation
CGS International’s Hong Kong operation sits inside a long ownership chain rather than a single company. The ultimate parent, China Galaxy Securities Co., Ltd. (中國銀河證券股份有限公司), trades in Shanghai and lists on the Hong Kong Stock Exchange under code 06881.HK; the firm’s own about page describes it as formed through the merger of trust-investment companies’ securities departments previously owned by the Industrial and Commercial Bank of China, China Agricultural Bank, Bank of China, China Construction Bank and China Life Insurance. Its first wholly-owned overseas subsidiary, CGS International Holdings Limited (中國銀河國際控股有限公司), was registered in Hong Kong in February 2011 and sits above a cluster of operating subsidiaries: a futures dealing arm, a securities trading arm that holds client deposit accounts, an asset management arm, an investment arm and a financial products arm in Hong Kong, plus separate securities subsidiaries in Singapore and Malaysia. A listing code on the Hong Kong Stock Exchange is a stock-market ticker, not a financial-services licence, and we hold no register entry for the Hong Kong Stock Exchange itself, so 06881.HK is not checked here.
What the SFC register confirms for China Galaxy International
We searched the Hong Kong Securities and Futures Commission’s Public Register of Licensed Persons and Registered Institutions directly, running a positive control against a firm known to be listed first so an empty result would mean absence rather than a broken search. China Galaxy International Futures (Hong Kong) Co., Limited (中國銀河期貨(香港)有限公司) holds CE reference AYH772 on that register, licensed for Type 2, Dealing in Futures Contracts, shown as active. The register records no public disciplinary action against it. This is the one licence in the group’s regulatory claims that we were able to look up and confirm on the primary source.
Licences claimed for the group that the register could not match
The material we reviewed also claims Type 1, Type 4, Type 6 and Type 9 licences (dealing in securities, advising on securities, advising on corporate finance, and asset management) for “CGS International Holdings Limited” and, separately, for CGS International Holdings Limited (中國銀河國際控股有限公司) acting through its wholly-owned subsidiaries. None of these claims carries a CE reference number, and when we searched the SFC register by name, no single corporation called “CGS International Holdings Limited” or by the Chinese name came back. That is a gap in the claim or in our name-matching against the register, not a finding that the licences do not exist; a holding company sitting above several licensed operating subsidiaries is a structure the SFC register may simply record under the subsidiaries’ own names rather than the group’s. We could not verify these four licence types on the primary source and are not treating the unverified claim as confirmed.
Warning lists and the wider group
We searched 1441 warning-list entries mirrored from CySEC, the FCA and the FSC Mauritius, and CGS International’s names do not appear on any of them. That is a genuinely clean result, though it only covers the three regulators we mirror and says nothing about lists we do not hold. Separately, the firm’s own root page, fetched identically across ten country exits, carries an active fraud warning stating that scammers have been sending messages with fake links or QR codes leading to counterfeit versions of its trading platform, and stating that the firm holds no bank accounts within mainland China and provides no mainland China transfer service. That warning is the firm’s own published notice, not a register finding, but it is worth a reader’s attention alongside the licence picture above.
Our previous review scored regulation for this broker at a level that rolled up to 4 out of 10 overall; this review scores regulation 5.6 out of 10 and 5.1 overall. That move is our assessment being restated against register checks our review process actually ran, not a claim that the firm’s regulatory standing has changed. The evidence behind it is mixed in a way the number reflects: one entity in the group, China Galaxy International Futures (Hong Kong) Co., Limited, is confirmed active on the SFC register under CE reference AYH772 with no disciplinary record, and the group’s names return clean across three warning-list registers we checked. Set against that, the broader set of licences claimed for the holding company across Types 1, 4, 6 and 9 could not be matched to any single corporation on the SFC register by name, and the Hong Kong Stock Exchange listing code is a market listing rather than a regulatory permission and sits outside any register we hold. A group with one directly confirmed operating licence, several unmatched claims, and a clean but limited warning-list search lands in the middle of the scale rather than at either end.
How to Trade
CGSI runs trading through five separate account structures rather than one blended account: a Securities Cash Account, a Securities Margin Account, a Futures Account, a Stock Options Account and an Electronic Trading Account. Our earlier review lists no minimum deposit for any of the five, and describes them as built for different jobs rather than different tiers of the same product.
What each CGSI account actually does
- There is no leverage on the Securities Cash Account; it settles cash trades in stocks, bonds and mutual funds. According to the earlier review, that account further extends to Hong Kong and China A-shares market access, comes with real-time pricing and research, and covers dividend and corporate-action processing.
- The Securities Margin Account builds in leverage and the ability to short eligible securities, along with portfolio margining; per the earlier review, the margin needed shifts depending on the security type and prevailing market conditions, though no specific number is given.
- The Futures Account gives access to what the earlier review counts as 140+ futures and options contracts, covering commodity, index and currency futures plus options on futures, with initial margin said to vary by contract.
- On the Stock Options Account, covered and naked options writing require approval, and the account also allows multi-leg options strategies and portfolio-level hedging. The level of approval granted depends on the experience and financial capacity a client has declared.
- The Electronic Trading Account is aimed at active traders and institutions, offering direct market access, algorithmic order types and API connectivity, according to the same review.
Instruments on offer
Per the earlier review, the product range centers on Hong Kong Stock Exchange equities, China A-shares reached through Stock Connect, and a selection of international equities; futures and options across Asian index, commodity and currency contracts; China and Hong Kong government bonds alongside investment-grade corporate and dim sum (offshore RMB) bonds; mutual funds across equity, money market, bond and balanced mandates; and structured products including equity-linked notes and capital-protected structures. The same review reports that CGSI does not offer forex, cryptocurrency or Western commodity trading, so traders looking for those markets in one account will not find them here. Separately, CGSI’s own site lists “insurance” as a distinct business-scope category in its navigation, but the page we fetched gives no product detail behind that heading, so we can say the category exists on the firm’s own site and nothing more.
The platforms CGS International trades run on
Rather than MetaTrader, the earlier review points to four in-house tools: SPTrader Pro, the primary app built for mobile use, supplying live Hong Kong/China quotes, charting and fast order entry; Galaxy Global Trading Terminals, the flagship desktop platform, pitched as institutional-grade with reach across multiple markets, algorithmic order types and built-in research; a Soft Token mobile app that handles two-factor authentication and offers limited trading capability; and AAStocks, a source of market data, news and fundamentals that the review notes is for viewing only, not for placing orders. The same review is explicit that CGSI offers neither MetaTrader 4 nor MetaTrader 5, so traders expecting to run existing MT4/MT5 expert advisors or use standard retail charting tools built for those platforms will need to work through the proprietary apps instead.
Margin, liquidation and the rules that bind a position
Margin and futures accounts here carry the standard mechanics of leveraged trading: margin calls, forced liquidation and daily mark-to-market, according to the earlier review. That review also flags something worth sitting on: it reports that CGSI’s risk-management approach is not marketed as “negative balance protection” in the sense used by European-regulated brokers, and that the firm’s terms describe a client’s liability for margin maintenance as extending to extraordinary circumstances. Restated plainly, that means the earlier review found no guarantee that a client’s losses stop at their account balance if the market gaps against a leveraged position. We have not independently read CGSI’s client agreement to confirm the exact clause behind that claim, so treat it as what the earlier review reported rather than a term we have verified ourselves.
What we could and could not confirm on cost
We read CGSI’s own published fee-schedule pages directly, covering securities fees, global stock fees, Hong Kong futures and options fees, global futures fees and stock options fees. None of the fetched pages carried an actual spread, commission or per-lot figure, so we cannot quote a trading cost for any of the five account types from what CGSI itself publishes. The one dealing entity we could check independently on a public register is China Galaxy International Futures (Hong Kong) Co., Limited, the futures-dealing subsidiary named in the account material above: the Hong Kong SFC’s Public Register of Licensed Persons and Registered Institutions shows it holding an active Type 2 (Dealing in Futures Contracts) licence under CE reference AYH772, with no public disciplinary action recorded against it. The broader holding company’s claimed Type 1, 4, 6 and 9 licences did not match any single corporation on that same register under the names supplied, so those remain unconfirmed rather than disproven.
Who can actually open an account
The earlier review reports checking CGSI’s homepage, legal, terms and legal-documents pages via an Indonesian exit on 2026-07-27 and finding no published list of restricted or prohibited countries on any of them. It also notes that an earlier version of the material it was drawing on had circulated such a list, that the list could not be traced to anything CGSI itself publishes, and that it was removed. Practically, that means country eligibility for these accounts cannot be confirmed from CGSI’s own public pages, and a previously circulated restricted-country list should not be relied on.
Account Types
CGSI sells access to its parent group’s Hong Kong brokerage through five separate account types, each tied to a different product line rather than a tiered pricing ladder. According to the earlier review of this firm the Securities Cash Account carries no stated minimum deposit. It suits unleveraged cash trading covering stocks, bonds and mutual funds, opens up the Hong Kong market along with China A shares, and comes with real time data and research plus dividend collection and corporate action processing.
The same earlier review describes a Securities Margin Account, also with no stated minimum deposit, adding leveraged trading, short selling for eligible securities, and portfolio margining, with margin requirements said to vary by security type and market conditions. A Futures Account is described as giving access to more than 140 futures and options contracts across commodity, index and currency futures and options on futures, with initial margin varying by contract. The Stock Options Account, once approval is granted, permits option writing in both covered and uncovered form, use of multi-leg strategies, and hedging across a portfolio; the level of approval a client receives is said to reflect their trading experience and financial resources. An Electronic Trading Account is aimed at active traders and institutions, offering direct market access, algorithmic trading and API connectivity. None of these five accounts is described in the material from our earlier review as carrying a minimum deposit figure.
What CGSI actually charges to open and fund these accounts
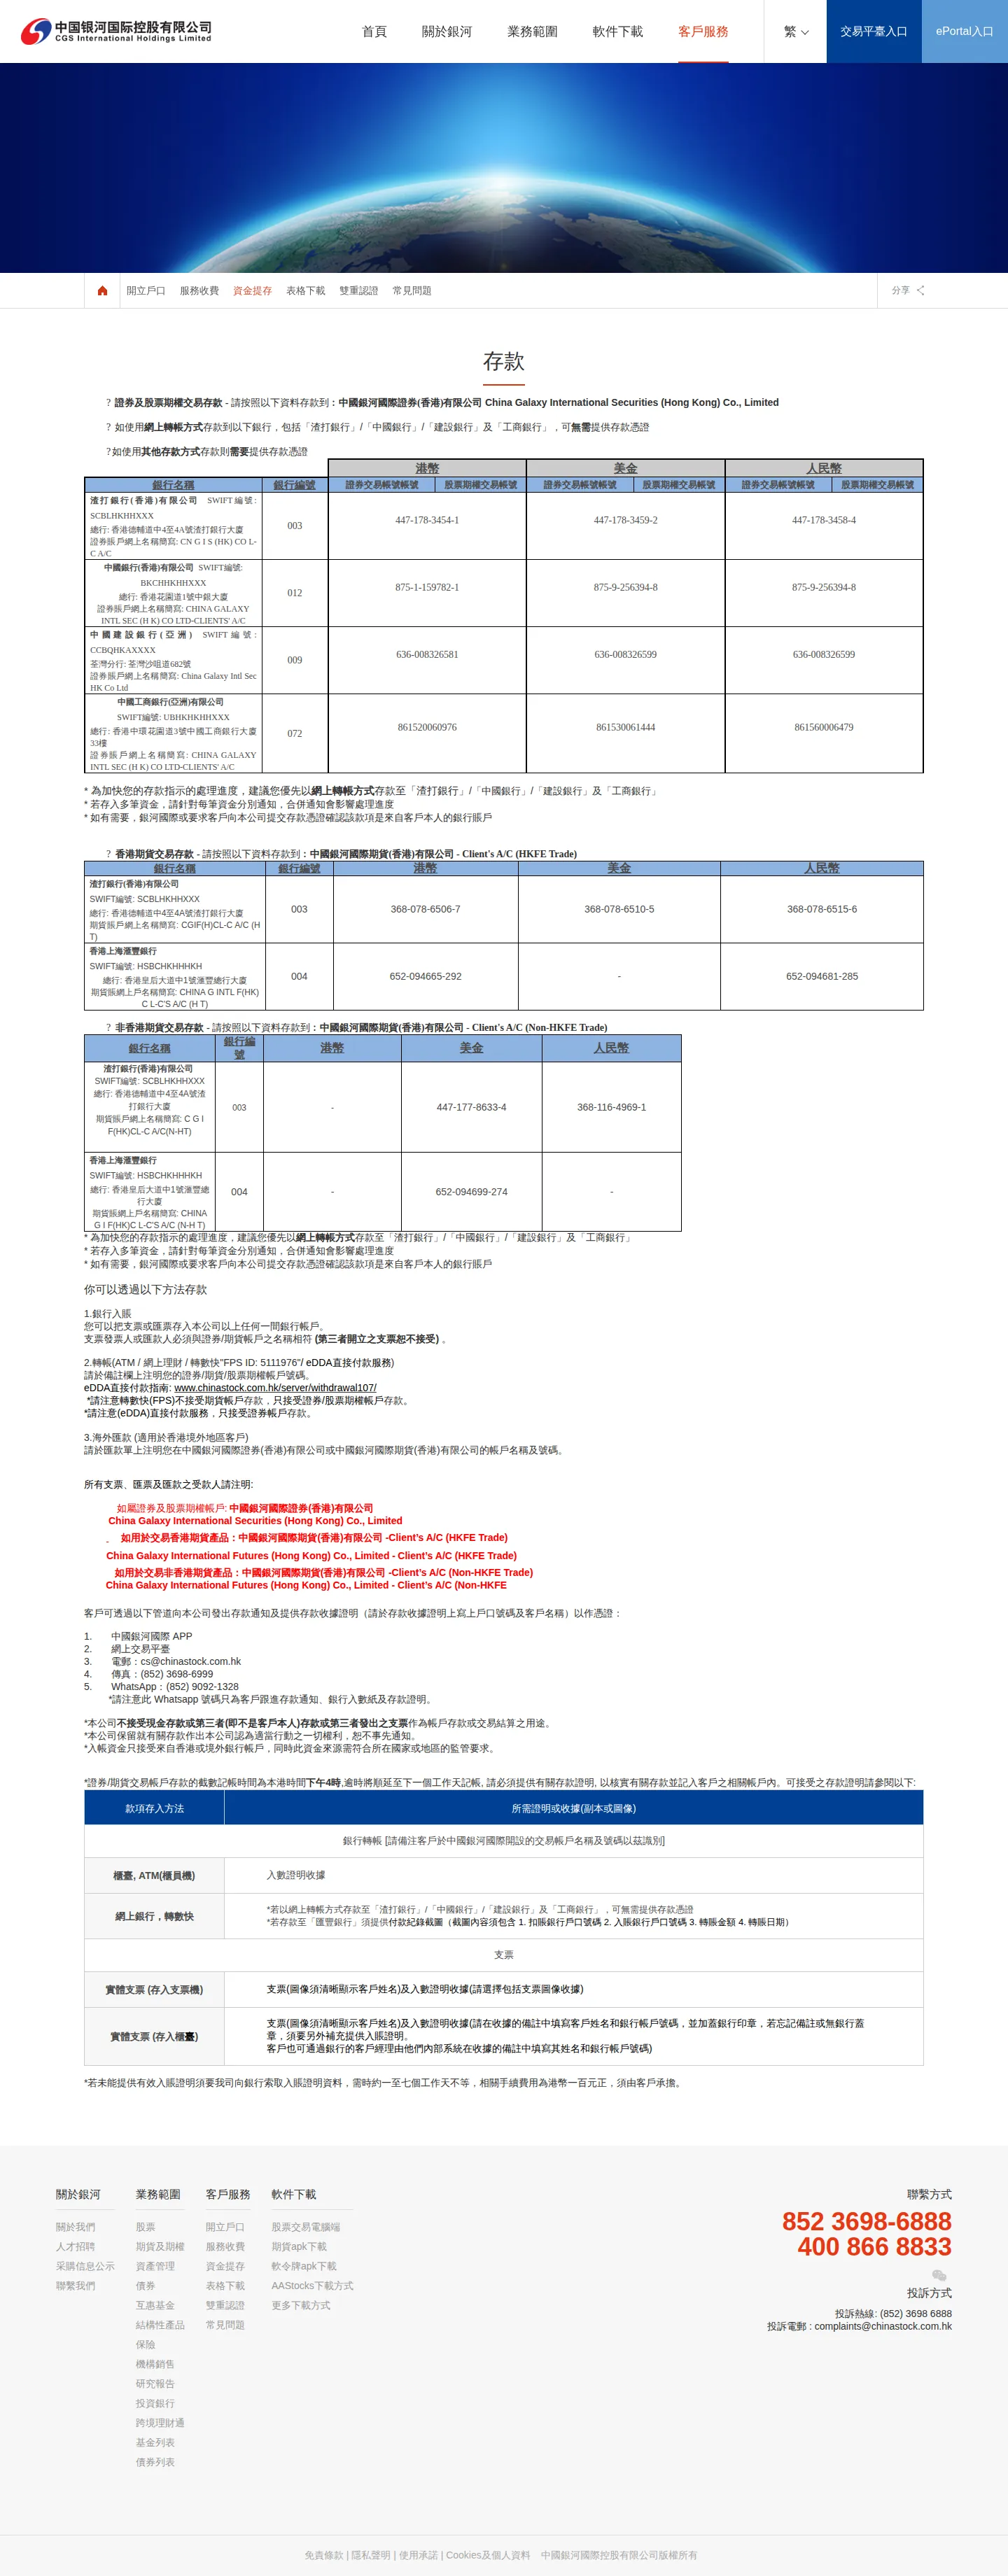
The firm’s own fee page, fetched directly, does not set out spread, commission or per lot pricing for any of the five accounts. What it does specify are the mechanics and costs of getting money into them. Bank wire transfers by SWIFT go to designated accounts at Standard Chartered, Bank of China, China Construction Bank (Asia) and ICBC (Asia), in HKD, USD or RMB, with a deposit cut off of 4:00pm Hong Kong time and late deposits credited the next business day. The cheque or draft payer’s name must match the securities or futures account name, and third party cheques are not accepted. FPS transfers, under FPS ID 5111976, are accepted in HKD but only for securities and stock options accounts, not futures accounts. A separate page on the firm’s site describes an eDDA direct debit service as free, available 24 hours a day every day of the week, crediting in about five minutes, and again limited to securities accounts, with Hang Seng, HSBC, Bank of China and Standard Chartered listed among the supported banks, registered through the firm’s own ePortal.
The fee page also names one specific charge: a bank confirmation retrieval fee of HKD 100, levied when a client cannot supply valid proof of deposit and the firm has to request the confirmation from the client’s bank directly, a process it says takes about one to seven business days and is charged to the client. Beyond that figure, the earlier review’s account of transfer costs, no standard fee for HKD bank transfer withdrawals processed in one to two business days, no standard fee for foreign currency withdrawals processed in two to three business days, and no broker side fee on wire deposits (the sending bank may still charge), was not something we could confirm against the firm’s own fetched pages.
What the evidence does not cover is any spread, commission or per lot figure for trading itself on any of these five accounts, despite the firm publishing dedicated fee schedule pages for securities, global stocks, Hong Kong futures and options, global futures, and stock options. The pages we fetched describe the account structure and the deposit and withdrawal mechanics in detail; they say nothing about what a trade on any of these accounts actually costs to execute.
Our previous score for this broker’s account offering sat at 4 out of 10; this review scores it 5.1 out of 10 overall, with fees specifically scored at 3 out of 10. The fees figure reflects what the evidence above shows: a firm that documents its deposit channels and a specific ancillary charge (the HKD 100 confirmation fee) in some detail, but for which no spread, commission or per lot trading cost could be found on any of its own fee pages. That gap, not a change in what the firm charges, is what this review’s criteria are measuring.
Negative Balance Protection
CGSI runs five account types side by side, and only one of them removes the risk this section is about. The Securities Cash Account trades stocks, bonds and mutual funds with no leverage, per the account-type description in the evidence gathered for this review; a cash account cannot go negative because nothing is borrowed against it. The other four can. The Securities Margin Account adds leveraged trading and short selling with margin requirements that vary by security and market conditions; the Futures Account gives access to more than 140 futures and options contracts with initial margin that varies by contract; the Stock Options Account allows covered and, subject to approval, naked options writing. Naked options writing in particular carries loss potential that is not capped by the premium paid, which is why it needs separate approval.
What CGSI’s own pages say about margin calls and liquidation
The CGSI pages fetched for this review, its Hong Kong deposit and fee pages and its “about” page describing the China Galaxy Securities group structure, do not set out a margin-call process, a forced-liquidation procedure, or a negative-balance protection policy. That is a gap in what we found on those pages, not a finding that no such policy exists; a firm running a leveraged margin account and a futures account with 140-plus contracts necessarily has some mechanism for handling under-margined positions, we simply did not find it published on the pages this review drew from.
What the earlier review reported
An earlier review of CGSI described the firm’s approach as margin calls, forced liquidation and daily mark-to-market, and said this was not marketed as negative balance protection in the sense used by European retail regulation. It also reported that the firm’s terms make a client liable for maintaining margin in circumstances it called extraordinary. We have not read the document that claim would come from, so we can only pass it on as something the earlier review stated, not as CGSI’s own wording, and it should be read with that limit in mind rather than treated as a verified quote from a client agreement.
The futures account sits under a confirmed licence
The futures dealing entity named for this account, China Galaxy International Futures (Hong Kong) Co., Limited, holds an active Type 2 (Dealing in Futures Contracts) licence on the Hong Kong SFC Public Register of Licensed Persons and Registered Institutions under CE reference AYH772, which we checked directly, with no public disciplinary action recorded against it. That confirms the entity running leveraged futures trading is a licensed dealer in that market, though the register entry itself says nothing about margin-call thresholds or how far a client’s liability can run if a position is liquidated late or in a fast-moving market.
Put together, a trader opening the Securities Cash Account here is not exposed to negative-balance risk at all, since there is no leverage to create it. A trader opening the Margin, Futures or Stock Options accounts is trading on margin against contracts and securities where CGSI’s own published pages do not spell out a loss-limit or negative-balance policy, leaving only the earlier review’s second-hand description of margin calls and mark-to-market liquidation, and its unverified claim about liability in extraordinary circumstances, to go on.
Trading Instruments
Our earlier review for CGSI (China Galaxy International, trading as CGSI/China Galaxy Securities) describes a five-way asset lineup: stocks on the Hong Kong Stock Exchange plus China A-shares accessed through Stock Connect and a selection of international equities; futures and options, put at more than 140 products spanning index futures on Asian benchmarks, commodity futures in agriculture and energy, and stock and index options; bonds covering China and Hong Kong government debt, investment-grade corporate paper and dim sum (offshore RMB) bonds; mutual funds across equity, money market, bond and balanced/multi-asset strategies; and structured products including equity-linked notes, capital-protected products and yield-enhancement structures. None of this list comes from a page we fetched ourselves, so treat it as what the earlier review found rather than something CGSI’s own site confirmed to us. Separately, the firm’s own root page, fetched directly, lists “insurance” as its own line in the site’s business-scope navigation, with no product detail behind it in what we pulled.
Account types on offer
Five account types appear in our earlier review, and none of them come with a stated minimum deposit. The Securities Cash Account covers unleveraged trading in stocks, bonds and mutual funds, with access to HK and China A-shares included. Building on that, the Securities Margin Account adds leveraged trading, short selling on eligible securities and portfolio margining, though the review says requirements vary by security and market conditions. A separate Futures Account covers the 140-plus futures and options contracts, with initial margin that varies by contract. Approval-based writing of both covered and naked options sits under the Stock Options Account, alongside support for multi-leg strategies. Rounding out the list, an Electronic Trading Account gives active traders and institutions direct market access, algorithmic trading and API connectivity. On the margin and futures side, the same review reported that CGSI’s risk-management approach, relying on margin calls, forced liquidation and daily mark-to-market, is not marketed as negative balance protection in the sense used by European regulators, and that the firm’s terms describe client liability for margin maintenance “in extraordinary circumstances.” We have not read that clause ourselves, so we’re restating what the earlier review said rather than quoting a document of CGSI’s.
Platforms, and what CGSI doesn’t offer
The same review names four proprietary tools: SPTrader Pro as the mobile-focused execution app for real-time HK and China quotes; Galaxy Global Trading Terminals as the flagship multi-market desktop platform with algorithmic order types and integrated research; a Soft Token mobile app for two-factor authentication with basic trading built in; and AAStocks as a view-only market-data feed rather than an execution platform. That review also flagged that CGSI does not offer MetaTrader 4 or MetaTrader 5, which matters for anyone expecting the order types, expert advisors or third-party tooling that standard retail MT4/MT5 brokers support. The same source put forex, cryptocurrency and Western commodity trading outside CGSI’s scope entirely, describing the firm’s focus as Hong Kong and China securities, Asian derivatives and fixed income rather than global multi-asset trading.
What CGSI’s fee pages actually show
We read the fee material CGSI itself publishes rather than relying on a summary of it. CGSI maintains separate fee schedules for securities, global stocks, Hong Kong futures and options, global futures, and stock options, but the pages we fetched contain no spread, commission or per-lot figures for any of these instrument categories. That means the actual cost of trading any of the asset classes listed above, cash equities, margin positions, futures, options or funds, could not be confirmed or quoted from what we gathered; a trader would need to get pricing from CGSI directly before assuming any figure quoted elsewhere applies.
Education & Analysis
Everything we can say about CGSI’s trading software comes from our earlier review, not from a platforms or features page of the firm’s own that we fetched ourselves. That review described four separate proprietary systems and no MetaTrader 4 or MetaTrader 5 support at all, which sets CGSI apart from the Western retail brokers whose platform sections default to MT4/MT5 compatibility, expert advisors and a shared library of third-party indicators. A trader arriving with an MT4 toolkit built up over years will not find anywhere to plug it in here.
SPTrader Pro and the Galaxy Global Trading Terminals
The earlier review described SPTrader Pro as the mobile-focused app most retail clients would use day to day, with real-time Hong Kong and China quotes, charting and quick order entry. Sitting above it, the same review named Galaxy Global Trading Terminals as CGSI’s flagship desktop system, pitched at an institutional grade with multi-market access, algorithmic order types and research built into the same window. Between the two, the picture that review paints is a firm that separates casual mobile access from a heavier desktop terminal aimed at active and professional traders, rather than offering one platform that scales for both.
AAStocks and the Soft Token app
Two more pieces round out the set the earlier review listed. AAStocks was described as a market information platform, carrying financial data, news and fundamentals, but explicitly view-only rather than a place to place an order. Soft Token was described as a mobile app for two-factor authentication that also carries basic trading functions. Neither is a charting or analysis platform in its own right; AAStocks supplies information a trader would then act on elsewhere, and Soft Token exists primarily to secure the login rather than to trade from.
What CGSI’s own pages add and where they stay silent
The fee-schedule pages we fetched directly from CGSI’s site do not name a Securities fees page, a Global stock fees page, a Hong Kong futures and options fees page, a Global futures fees page or a stock options fees page, so we cannot say the account types the earlier review lists are backed by real published fee material. None of the pages we pulled carried spread, commission or per-lot figures either, so we cannot connect a specific platform to a specific cost of using it, and the accounts themselves (Securities Cash, Securities Margin, Futures, Stock Options, Electronic Trading) are described only in terms of what they permit, not what they charge to trade on any given platform. We also did not fetch a features page in CGSI’s own words describing order types, charting depth, algorithmic tools or API documentation for the Electronic Trading Account the earlier review mentions, so those specifics rest entirely on that second-hand description and cannot be confirmed further here.
One first-hand item is worth flagging on its own: the root page CGSI publishes across the country exits we checked carries an active fraud warning, telling visitors that scammers have been sending messages with fake links or QR codes that lead to counterfeit versions of its trading platform in order to steal personal data, and stating the firm holds no bank accounts in mainland China and runs no mainland China transfer service. That is a warning about impersonation of the platform, not a claim about the platform’s own functionality, but anyone contacted about a “CGSI app” outside the channels named on its own site should weigh it against that notice.
Our previous score for this criterion put platform at the center of a 4/10 overall; this review scores platform at 6.6/10 and moves the overall figure to 5.1/10. That change reflects our current assessment against the evidence above, not any change at CGSI’s end: a spread of four distinct tools covering mobile execution, an institutional desktop terminal, a standalone data feed and a dedicated authenticator app is a wider platform footprint than a single generic app, even without MT4/MT5 and even with the underlying fee and feature detail still unconfirmed from the firm’s own pages.
Special Offers
We didn’t find a promotions or special-offers page anywhere in the CGSI material we fetched. What we did read were the firm’s dedicated fee-schedule pages and its account-types listing, and neither describes deposit bonuses, cashback, discounted commission tiers or any other promotional credit.
What CGSI’s fee pages actually cover
The firm’s deposit-and-fees page lists several ways to fund an account, and some carry no cost: FPS transfers are free for Hong Kong bank account holders, and the eDDA direct-payment service is described on that page as free (免費), available around the clock, with deposits credited in about five minutes for securities accounts. Bank wire deposits carry no fee from the broker, though the sending bank may charge its own. These read as standard fee waivers tied to specific payment rails rather than time-limited offers, and the fee pages don’t frame any of them as promotional.
The same fee page sets a HKD 100 charge for retrieving bank confirmation records when a client can’t supply valid proof of deposit, which is a cost rather than a discount of any kind.
Account minimums, as reported by the earlier review
Our earlier review reported that CGSI’s five account types, Securities Cash, Securities Margin, Futures, Stock Options and Electronic Trading, all carry no minimum deposit. We haven’t checked that figure against the firm’s own pages, so it should be read as what the earlier review found rather than something confirmed first-hand here. Even taken at face value, a waived minimum isn’t presented anywhere as a promotional term, just as the account’s baseline requirement.
A warning worth reading alongside any offer claiming to be from CGSI
CGSI’s own root page carries an active notice, unchanged across the ten country exits we checked, warning that fraudsters have been sending messages that invite recipients to click fake links or scan QR codes leading to counterfeit versions of its trading platform to steal personal data. The same notice states the firm holds no bank accounts within mainland China and provides no mainland China transfer service. Anyone approached with a discount, bonus or account offer that asks for a QR-code scan or a mainland China transfer is being contacted by someone other than CGSI, going by the firm’s own description of what these scams look like.
Opening an Account
CGSI does not publish a single “how to open an account” walkthrough in the material we fetched, but the account types it lists, taken together with its fee and payment pages, set out what a new client is choosing between and what the firm asks for to move money in.
Which account to open
Our earlier review lists five account types on offer: a Securities Cash Account for unleveraged trading in stocks, bonds and mutual funds; a Securities Margin Account adding leverage, short selling on eligible securities and portfolio margining; a Futures Account giving access to more than 140 futures and options contracts; a Stock Options Account for covered and naked options writing “subject to approval,” with approval levels said to depend on the client’s experience and financial capacity; and an Electronic Trading Account offering direct market access, algorithmic order types and API connectivity aimed at active traders and institutions. For all five, the same earlier review reports no stated minimum deposit. None of this comes from a page we fetched ourselves, so treat the account descriptions as reported rather than confirmed.
Funding the account with CGSI
CGSI’s own fee page, fetched directly, sets out several funding routes rather than a single one. Bank wire (SWIFT) goes to designated accounts at Standard Chartered, Bank of China, China Construction Bank (Asia) or ICBC (Asia), and the payer or remitter name on any cheque or draft must match the name on the securities or futures account; third-party cheques are not accepted. Deposits have a 4:00pm Hong Kong time cut-off, with anything later credited the next business day. FPS transfers (轉數快, FPS ID 5111976) are accepted in HKD but only into securities or stock-options accounts, not futures accounts. A separate fee page describes eDDA direct debit registration and deposits as free, available around the clock, crediting in about five minutes, and again limited to securities accounts, with Hang Seng, HSBC, Bank of China and Standard Chartered named as supported banks, registered through CGSI’s own ePortal. Clients outside Hong Kong funding by overseas remittance must state the correct receiving entity, China Galaxy International Securities (Hong Kong) or China Galaxy International Futures (Hong Kong), by name and account number on the remittance form.
Verification of a deposit is not automatic in every case: the same fee page sets a charge of HKD 100 for the firm to retrieve bank confirmation records directly from a client’s bank when the client cannot supply valid proof of deposit themselves, a process it says takes one to seven business days and is billed to the client. A WhatsApp line, (852) 9092-1328, is listed on that page for following up on deposit notifications, pay-in slips and proof of deposit specifically, separate from general customer service.
Who can open one
We found no published restricted-country list on CGSI’s homepage, legal or terms pages when the site was checked via an Indonesian exit on 2026-07-27, and note that an earlier version of this material had circulated a list of prohibited countries that could not be traced back to anything CGSI itself publishes; that list should not be relied on. In practice this means eligibility by country of residence cannot be confirmed from CGSI’s own public pages with the evidence we hold. Separately, CGSI’s root page carries a standing anti-fraud notice, repeated identically across ten country exits, warning that fraudsters send messages inviting recipients to click fake links or scan QR codes leading to counterfeit versions of its trading platform, and states plainly that the firm holds no bank accounts inside mainland China and provides no mainland China transfer service. Anyone contacted about opening an account through a mainland China bank transfer, or through a link outside CGSI’s own channels, is being contacted by someone other than CGSI.
On regulatory standing, the only claim we could independently verify was China Galaxy International Futures (Hong Kong) Co., Limited’s CE reference AYH772 on the Hong Kong SFC Public Register, active for Type 2 (Dealing in Futures Contracts), with no public disciplinary action recorded against it. Claims that CGS International Holdings Limited itself holds Types 1, 2, 4, 6 and 9 licences quoted no CE reference we could look up, and the SFC register’s name search returned no single corporate entity by that name, so those particular licence claims sit unchecked rather than confirmed or denied. A prospective client relying on regulatory status to decide whether to open an account should check the CE number of the specific CGSI entity they would be contracting with, not the group name.
This review scores CGSI 5.1 out of 10 overall, up from our previous 4 out of 10. The move is ours, from applying updated criteria and evidence, not a claim that CGSI itself has changed. Regulation lands at 5.6, held down by how many of the group’s licence claims we could not match to a register entry even as the futures subsidiary’s Type 2 licence checked out clean; fees score 3, reflecting that we could locate no spread, commission or per-lot figures on CGSI’s own published fee-schedule pages despite reading them directly.
Deposits & Withdrawals
CGSI runs deposit and withdrawal rails through Hong Kong bank accounts rather than through a single global cashier. The firm’s own fee page lists designated accounts at Standard Chartered, Bank of China, China Construction Bank (Asia) and ICBC (Asia) for SWIFT wire transfers, in HKD, USD and RMB.
Funding CGSI: what the fee page actually covers
Beyond wire transfer, the firm’s fee page lists FPS (轉數快, FPS ID 5111976) for HKD deposits, but only into securities or stock options accounts, not futures accounts. A separate page on the firm’s site describes eDDA direct debit registration and deposits as free, available 7 days a week and around the clock, crediting in about 5 minutes, and again limited to securities accounts; supported banks named there include Hang Seng, HSBC, Bank of China and Standard Chartered, with registration through the firm’s ePortal. The fee page also allows cheque deposits by ATM or bank counter, in HKD or USD, and requires that the cheque or draft clearly show the client’s name; third party cheques are not accepted, and counter deposits require the account name and number noted with a bank stamp on the receipt. Clients outside Hong Kong sending an overseas remittance must state the receiving entity’s account name and number, either China Galaxy International Securities (Hong Kong) or China Galaxy International Futures (Hong Kong) depending on the account. The fee page sets a deposit cut off of 4:00pm Hong Kong time, with anything later credited the next business day.
The fee page also names a specific charge tied to funding: a bank confirmation retrieval fee of HKD 100 (港幣一百元正), charged when a client cannot provide valid deposit proof and the firm has to request confirmation records from the client’s bank. That request takes about 1 to 7 business days, and the fee page states it is borne by the client.
Withdrawals
The evidence gathered for this review does not include a withdrawal-specific page from the firm with its own fee schedule; what is available on withdrawals comes from the earlier published review being rewritten here, not from a page our review process fetched. Restated in our own words, that earlier review reported bank transfer withdrawals in HKD to registered Hong Kong bank accounts with no standard fee and a processing time of 1 to 2 business days, and withdrawals in foreign currencies with no standard fee and a processing time of 2 to 3 business days. Those figures should be read as second hand rather than as confirmed from the firm’s own published material.
What’s missing from the published pages
The pages fetched for this review describe funding channels, cut off times and the bank confirmation fee, but say nothing about a minimum deposit, a minimum withdrawal amount, or a cap on how much can move in a single transaction. Each of the five account types, Securities Cash, Securities Margin, Futures, Stock Options and Electronic Trading, is missing a stated minimum deposit, and the fee material gathered for this review likewise says nothing about a currency conversion charge, an inactivity fee, or any fee specific to withdrawing by cheque or FPS.
One detail from the firm’s own root page is worth carrying into this section rather than the support section alone: the page carries an active fraud warning stating that the firm holds no bank accounts within mainland China and provides no mainland China transfer service, and that fraudsters have been sending messages with fake links or QR codes leading to counterfeit versions of its trading platform. Anyone funding an account through a channel other than the ones named on the firm’s own fee page, particularly anything claiming to be a mainland China transfer route, is outside what the firm itself describes as legitimate.
This review’s fees score is 3 out of 10. The evidence supporting it is thin on the specific figures that usually drive a fees score up or down, no spread or commission figures were present in the fee pages fetched, and what is confirmed is mostly process (cut off times, accepted payment rails, the HKD 100 confirmation charge) rather than a full published cost schedule.
Customer Support
Our previous entry for this broker scored it 4 out of 10 overall. This review scores it 5.1 out of 10 overall, with the support and service criterion specifically at 5.3 out of 10. That move is this review’s own assessment against the evidence below, not a claim that the firm’s service has changed: it reflects named, working contact channels found on the firm’s own site, a complaints line kept separate from general customer service, and a clean result when we checked this firm’s name against the warning lists we searched. The firm is licensed and trades under the China Galaxy / CGS International group name; the pages we cite below appear under the “chinastock.com.hk” domain and use “China Galaxy International” for the account-holding entities.
How to reach CGSI
The firm’s own root page lists two phone numbers for two different purposes. Under its official anti-fraud notice it gives (852) 3698 6750 / 400 866 8833 as the customer service line. In the page footer it separately gives 852 3698-6888 / 400 866 8833 as its general contact number. The two numbers differ in the Hong Kong segment (6750 against 6888); we report both as published rather than picking one, since the evidence gives no indication which a caller should prefer for a given purpose. The same page gives a general customer service email, cs@chinastock.com.hk, and the firm’s website address, firm’s website.
Complaints handling at CGSI
The firm’s root page lists a complaints hotline, (852) 3698 6888, and a separate complaints email, complaints@chinastock.com.hk, distinct from the general customer service address. The complaints hotline number matches the general footer contact number rather than the anti-fraud-notice number, which at least puts a complaint on the same line as general enquiries rather than a third, unpublished one.
Deposit support and the fee attached to it
The firm’s fee page sets out a narrower channel for deposit-related queries: a fax line, (852) 3698-6999, and a WhatsApp number, (852) 9092-1328, which the page states is for following up on deposit notifications, bank pay-in slips and proof of deposit only, not for general support. The same page sets a fee for what happens when that proof is missing: if a client cannot provide valid deposit confirmation, the firm charges HKD 100 (港幣一百元正) to retrieve confirmation records from the client’s bank directly, a process the page says takes about one to seven business days, with the cost borne by the client. Deposit instructions on the same page are exacting on the client’s side too: a cheque or draft’s payer name must match the securities or futures account name, third-party cheques are not accepted, and the deposit cut-off is 4:00pm Hong Kong time, with anything after that credited the next business day. Read together, this is a firm whose deposit-support process is built around paperwork matching and bank-side verification rather than same-day resolution by phone.
The firm’s own scam warning
The same root page that carries the customer service numbers also carries an active anti-fraud notice, warning that fraudsters are sending messages inviting recipients to click fake links or scan QR codes that lead to counterfeit versions of its trading platform to steal personal data. The same notice states the firm holds no bank accounts within mainland China and provides no mainland China transfer service. For anyone contacting this firm about their account, that notice is the firm’s own baseline for which numbers and links are genuine, and it is worth checking a contact detail against it before acting on an unsolicited message claiming to be CGSI.
What the warning-list check found
We searched 1,441 warning-list entries mirrored from CySEC, the FCA and the FSC Mauritius, and this firm’s name matched none of them. Before relying on that, we ran a positive control against a firm known to be listed on each of the six registers we searched directly, so an empty result reflects absence on the lists we hold rather than a search that simply found nothing. That result covers only the regulators we mirror, not every warning list in existence, and it is not itself a support-channel finding, but it is a relevant data point when weighing whether the contact details above are worth trusting.
Where the record is quiet
The pages we fetched for this firm give phone numbers, two email addresses, a fax line and a restricted-use WhatsApp channel. They say nothing about live chat, stated support hours, or a published service-level target for how quickly a complaint gets a response. An earlier third-party review of this firm that we are otherwise rewriting also listed three Hong Kong office addresses and a separate set of phone numbers, but that document ends with unrelated third-party promotional content pointing readers to other brokers, which told us it is our earlier review rather than the firm’s own material; we have not used its contact details here because we could not corroborate them against any page the firm itself publishes.
Prohibited Countries
We found no published restricted-country list on this firm’s homepage, legal, terms or legal documents pages when we checked via an Indonesian exit on 2026-07-27. An earlier version of this material carried a list of prohibited countries that could not be traced to anything the broker publishes, and that list has been removed rather than replaced. What that leaves us with is silence: we hold no page from this firm naming countries it will or will not accept, and that silence is ours, not the firm’s. It means eligibility by country cannot be confirmed from public pages alone, not that the firm accepts clients everywhere or restricts none.
What CGSI’s own site does say
The root page we fetched, identical across the ten country exits we pulled it from, carries an active fraud warning rather than a client eligibility notice. It states that fraudsters have been sending messages inviting recipients to click fake links or scan QR codes leading to counterfeit versions of the firm’s trading platform to steal personal data. The same notice states the firm holds no bank accounts within mainland China and provides no mainland China transfer service. That is a statement about banking and fraud, not about which countries may open an account, and we are not extending it into one.
What the account and payment pages imply without stating
The five account types described in our evidence, the Securities Cash Account, Securities Margin Account, Futures Account, Stock Options Account and Electronic Trading Account, carry no minimum deposit and no stated nationality or residency condition in the material we hold. The fee page we read sets out deposit mechanics that point toward a Hong Kong client base without saying so directly: FPS transfers are restricted to Hong Kong bank account holders, the eDDA direct debit service lists supported banks that are all Hong Kong institutions (Hang Seng, HSBC, Bank of China, Standard Chartered), and a separate “overseas remittance” method exists specifically for clients located outside Hong Kong, requiring the remittance form to state the relevant China Galaxy International Securities (Hong Kong) or China Galaxy International Futures (Hong Kong) account name and number. A dedicated overseas remittance channel existing at all tells us the firm expects and processes deposits from outside Hong Kong; it does not tell us which countries are excluded from that channel, because no page in our evidence lists any.
The licensing picture behind China Galaxy International Futures
The Hong Kong SFC Public Register of Licensed Persons and Registered Institutions confirms that China Galaxy International Futures (Hong Kong) Co., Limited holds CE reference AYH772, licensed for Type 2, dealing in futures contracts, shown as active, with no public disciplinary action recorded against it. That confirms one operating subsidiary’s standing with its regulator. It says nothing about country eligibility for clients, since SFC licensing governs what the firm is permitted to do in Hong Kong, not who it may onboard from abroad. Four other licence claims carried by the earlier review, covering Types 1, 4, 6 and 9 attributed to “CGS International Holdings Limited,” could not be checked: the claims quote no CE reference, and the SFC register’s name search returned no single corporation matching that name, so there was nothing for us to look up. That is a gap in the claim or in our matching, not a finding that those licences do or do not exist, and it has no bearing on which countries can or cannot use the firm.
What we are not going to claim
Our earlier review reported that the firm offers no forex, cryptocurrency or Western commodity trading, and focuses instead on Hong Kong and China securities, Asian derivatives and fixed income. That is a product-scope limit, not a country restriction, and product availability is not the same question as who may open an account. We are also not treating the previously circulated prohibited-country list as reliable: it could not be traced to any page this firm publishes, and using it here would mean reporting a fact with no attributable source behind it, which is the one thing this section cannot do. Until we fetch a page from CGSI that names excluded jurisdictions, the honest position is the one stated above: the pages we hold say nothing on the question, and that gap sits with our evidence, not with the firm’s client base.
Conclusion
This review scores CGS International 5.1 out of 10, up from the 4/10 our previous review gave it. The move is our assessment, not a change in the firm: this pass ran the group’s names against the Hong Kong Securities and Futures Commission register directly, ran a positive control first so an empty result would mean something, and checked the warning-list mirrors, and what came back is a mixed picture rather than a clean pass or fail.
What the SFC register actually shows for CGS International
The Hong Kong SFC Public Register of Licensed Persons and Registered Institutions confirms one entity by CE reference: China Galaxy International Futures (Hong Kong) Co., Limited holds AYH772 for Type 2, dealing in futures contracts, shown as active, with no public disciplinary action recorded against it. That is a real, checkable licence sitting inside the same group as CGS International, and it is the strongest single fact behind the regulation score of 5.6.
The wider claim that CGS International Holdings Limited itself holds Types 1, 2, 4, 6 and 9 could not be run down the same way. None of those four licence entries quotes a CE reference, and the SFC’s name search returned no single corporation called “CGS International Holdings Limited” to check them against. That is a gap in the claim or in our matching against the register, not a finding that the licences do not exist, and we have written it that way rather than asserting an absence the register never gave us. The same applies to the Hong Kong Stock Exchange listing code 06881.HK carried in the evidence: we hold no register entry for that exchange, so it stands unchecked rather than confirmed. Against the mirrored warning lists we searched, 1,441 entries pulled from CYSEC, the FCA and FSC Mauritius, CGS International matched none of them.
Why fees pull the score down
Fees score 3 out of 10, and the fee pages we actually read explain why. CGS International’s Hong Kong site sets out deposit and withdrawal mechanics in detail: eDDA direct debit registration and deposits are free, FPS transfers in HKD carry no fee, bank wire deposits carry none from the broker’s side, and a bank confirmation retrieval fee of HKD 100 applies only if a client cannot supply valid deposit proof and the firm has to chase the client’s bank for it. What those pages do not carry is any spread, commission or per-lot figure for the securities, futures, options or margin accounts on offer. CGSI publishes dedicated fee-schedule pages for securities, global stocks, Hong Kong futures and options, global futures, and stock options, and none of the content we fetched from them states what a trade actually costs.
Platform and support
Platform scores 6.6. CGS International runs four of its own systems rather than MetaTrader: SPTrader Pro as the mobile app, Galaxy Global Trading Terminals as the institutional-grade desktop platform, a Soft Token app for two-factor authentication, and AAStocks as a view-only market data feed. There is no MT4 or MT5 here, so traders relying on Expert Advisors or standard retail charting tools built for those platforms will not find them.
Support scores 5.3. CGSI lists a customer service line, a separate complaints hotline and email, a fax line for deposit paperwork, and a WhatsApp number the firm itself states is only for following up on deposit notifications and proof-of-payment, not general enquiries. The same root page also carries an active warning, in the firm’s own words, that fraudsters have been sending messages with fake links or QR codes leading to counterfeit versions of its trading platform, and states the firm holds no bank accounts in mainland China and offers no mainland China transfer service. That notice is worth reading before responding to any unsolicited message claiming to be CGS International.
CGS International holds a confirmed, active Hong Kong SFC futures-dealing licence through one subsidiary and a clean result against 1,441 mirrored warning-list entries, but its own fee pages never state what a trade costs. TrueBroker scores CGS International 5.1 out of 10.
What we saw
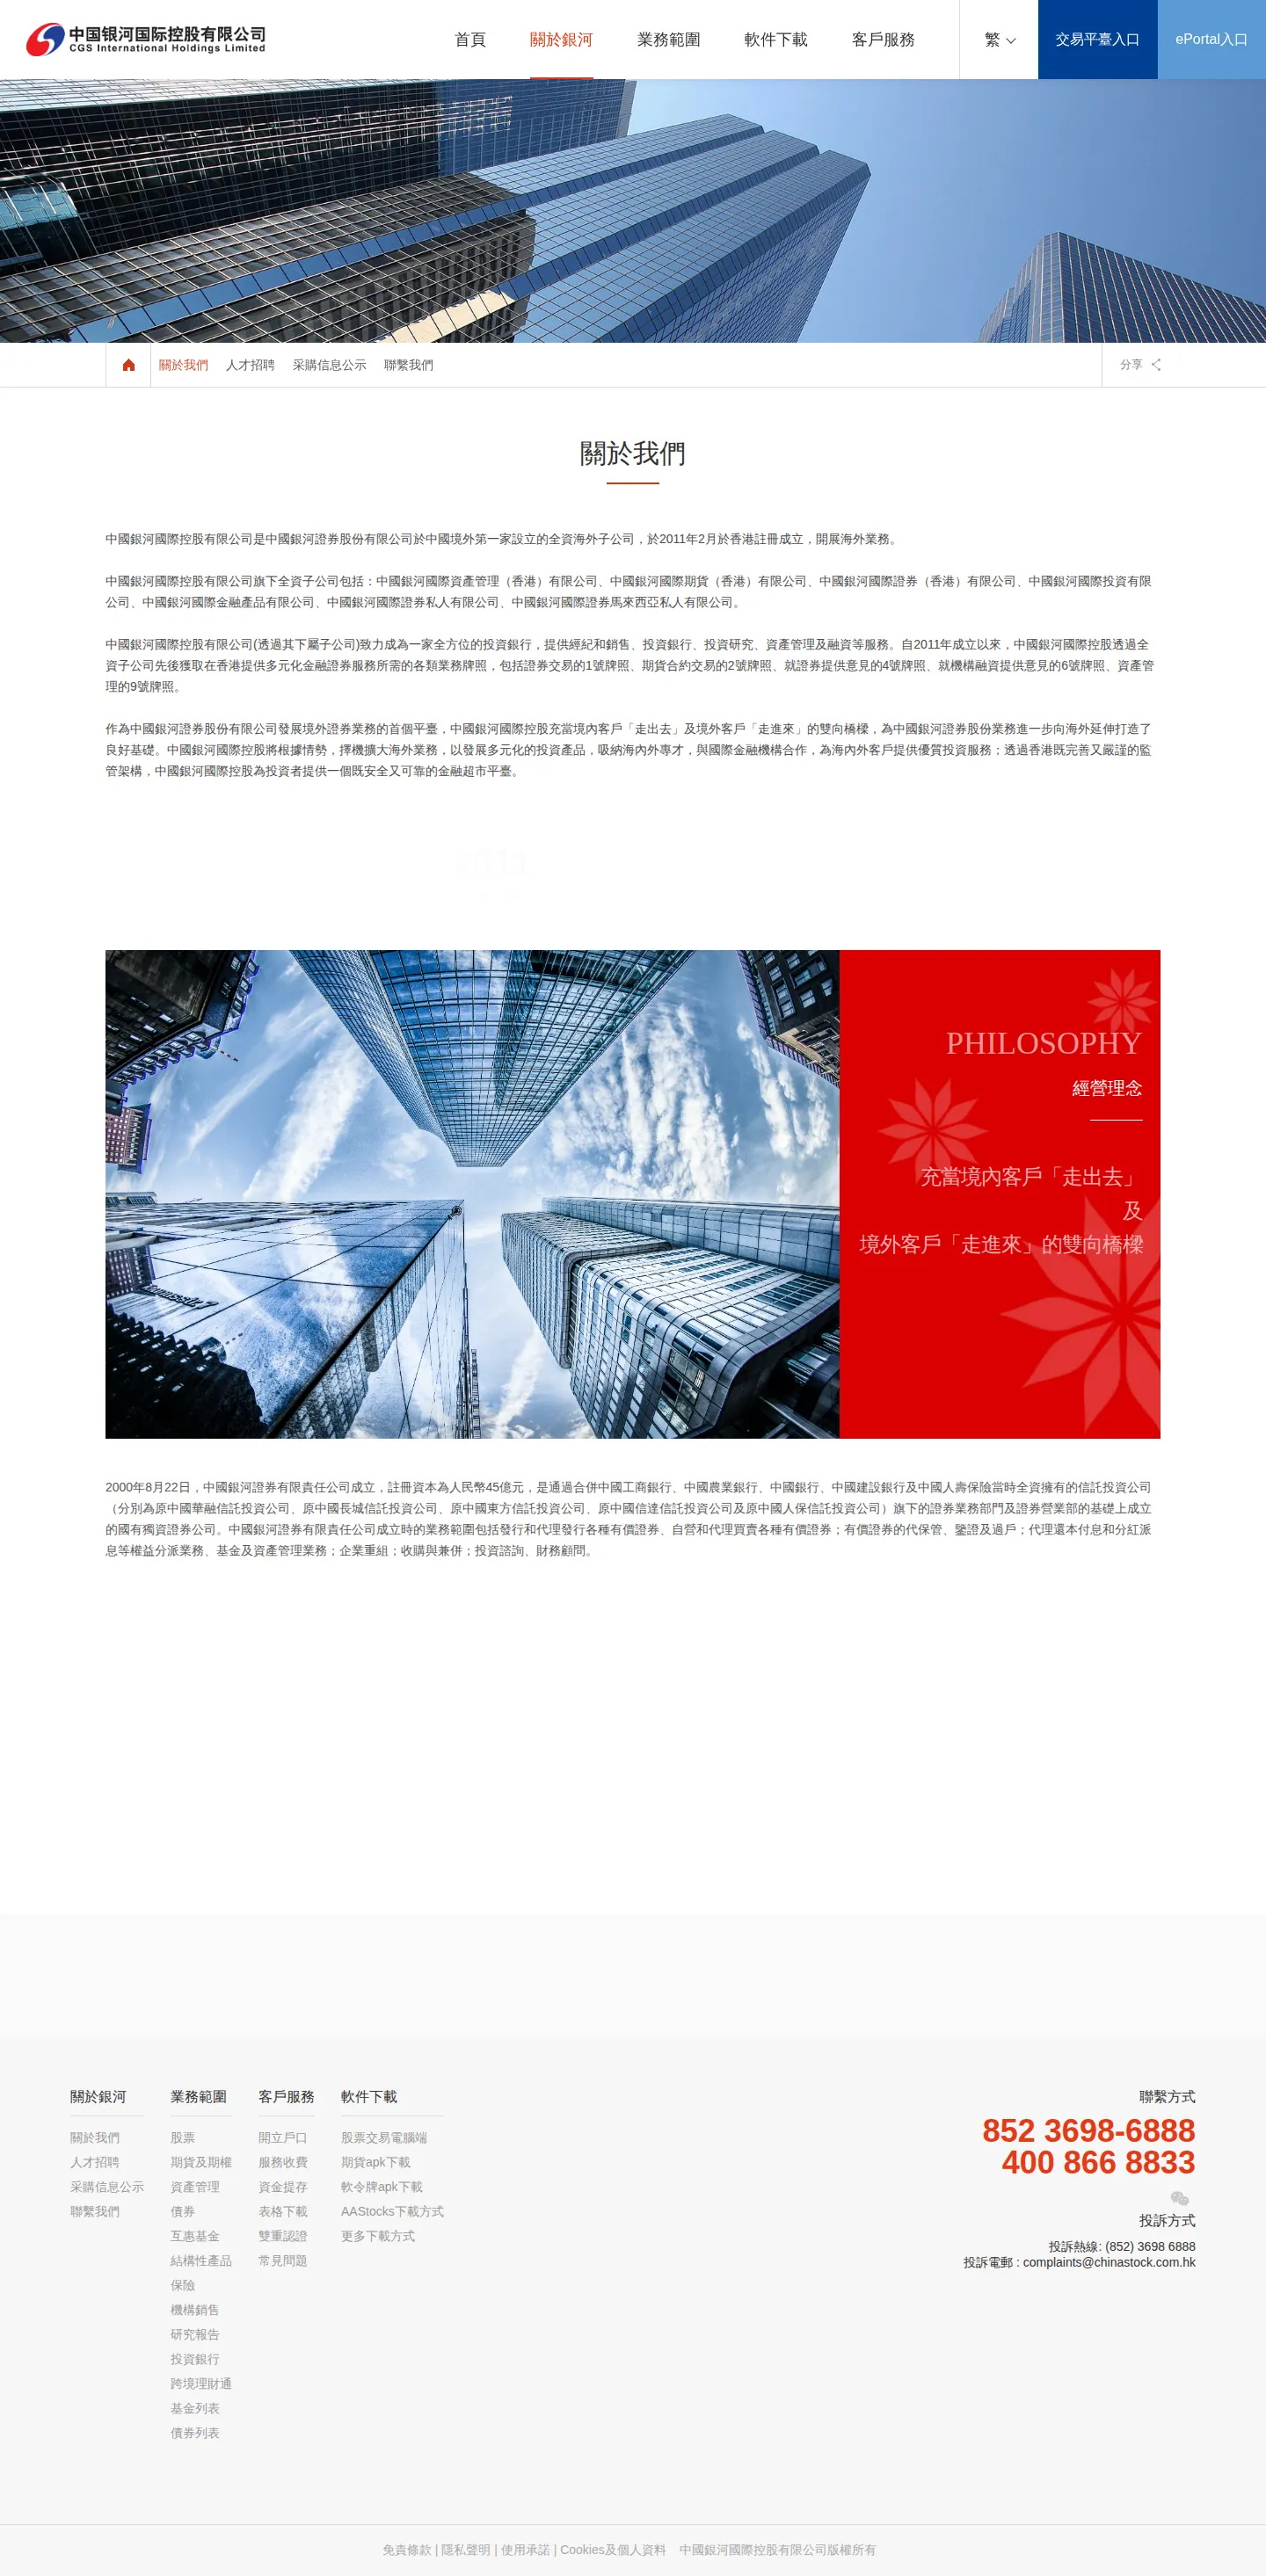
Pages captured from CGSI’s own site when this review was written. Brokers change their terms; these are what we read.
Score history
Recomputed daily; every move is on the record. The current score is always the latest row.
| Date | Score | Move |
|---|---|---|
| 2026-09-29 | 5.1 | ▲ |
| 2026-07-25 | 4.0 | = |
| 2026-07-18 | 4.0 | ▲ |
| 2026-07-11 | 3.9 | · |
FAQ
Is CGSI regulated?
Yes, its China Galaxy International Futures (Hong Kong) entity holds SFC licence AYH772 for dealing in futures, confirmed active with no disciplinary record.
What trading platforms does CGSI offer?
Its own web platform, mobile app, desktop client, a futures APK, and the institutional Galaxy Global Trading Terminals; it also offers AAStocks, which is mainly for market information.
What does CGSI charge in fees?
Some fees are published, but no EURUSD spread is given for a retail-accessible account, so a full cost picture isn’t available.
How can I contact CGSI support?
By email and a published phone number.
What do reviews say about CGSI?
It has a blended score of 3.33 stars, based on only 10 ratings.
Is client money protected if CGSI fails?
Under the SFC framework, compensation is capped at 500,000 HKD, and leverage on major FX is capped at 20:1.
How this review works
Track CGSI live: score moves and red notices, in your pocket.