STOCK · CHECKED 10 OCT 2026
CMS review.
Hong Kong-linked stock broker with licensing confirmed for a subsidiary, not the entity itself
RISKY
OUT OF 10
CMS is a stock broker linked to the China Merchants Securities group. Hong Kong's SFC confirms active Types 1, 2, 4, 6 and 9 licences, but only for a same-named subsidiary, not verified for the reviewed entity itself. No trading costs are published, and reviews are thin: 3.31 stars from just 14 ratings.
Each criterion is scored 1 to 10 from primary sources. The overall score is their unweighted mean. How scoring works.
| Founded | 1999 |
|---|---|
| Headquarters | HK |
| Minimum deposit | Not stated |
| Account opening | 1-3 |
- SFC Hong Kong confirms Types 1, 2, 4, 6 and 9 active for a same-named subsidiary
- Compensation scheme covers up to 500,000 HKD under SFC Hong Kong
- Offers its own web platform, mobile app, and Windows and Mac clients
- Support reachable by email and phone, staffed in client's own language
- No published cost of trading found on the broker's own pages or documents
- Confirmed licences belong to a same-named subsidiary, not the reviewed entity
- No negative balance protection requirement under the SFC Hong Kong regime
- SFC adjudicator process binds the firm but charges the claimant to use it
- Korea FSS licence claim not checked, a directory gap
- Support entity and escalation path depend on which one onboarded the client
Overview
TrueBroker is a free broker safety checker, and this page is our review of CMS, scored 5.1 out of 10 across regulation, fees, platform, support and reviews. The website operates under China Merchants Securities International Company Limited (招商證券國際有限公司), a Hong Kong subsidiary of China Merchants Securities Co., Ltd. (6099.HK / 600999.SH), which is itself part of China Merchants Group, described in our earlier review as a Fortune 500 conglomerate. The group runs the brand through several separately licensed operating companies rather than one legal entity, and which one a client actually contracts with changes what protections apply.
Overview Table
| Headquarters | Central, Hong Kong (Exchange Square Tower One, 32/F), per CMS’s contact page |
| Established | Not stated |
| Countries Served | Not stated |
| Regulated By | Securities and Futures Commission (Hong Kong), via subsidiary China Merchants Securities (HK) Co., Limited, CE AAI650; FCA (UK) FRN 610534 held by China Merchants Securities (UK) Limited but recorded as no longer authorised |
| Minimum Deposit | Not stated |
| Maximum Leverage | Not stated |
| Total Instruments | Not stated |
| Platforms | CMS International trading software for Windows and Mac, iPhone and Android apps, and a web trading login, per CMS’s software download page |
| Customer Support | Phone, email and physical offices in Central and Kwun Tong, Hong Kong, and Seoul, South Korea; a separate complaints hotline and email |
| Languages | Not stated |
Facts List
- The reviewed site is run by China Merchants Securities International Company Limited, described on its own about page as the group’s Hong Kong international investment banking subsidiary.
- The Hong Kong SFC Public Register of Licensed Persons and Registered Institutions shows the licence itself sits with a related company, China Merchants Securities (HK) Co., Limited, under CE reference AAI650.
- That SFC licence covers Type 1 (Dealing in Securities), Type 2 (Dealing in Futures Contracts), Type 4 (Advising on Securities), Type 6 (Advising on Corporate Finance) and Type 9 (Asset Management), each shown as active, with one licensing condition attached and no public disciplinary action recorded.
- A Type 5 (Advising on Futures Contracts) licence claimed by the earlier review is held by the group’s futures arm, China Merchants Futures (HK) Co., Limited, SFC CE AGO928, active since 7 March 2005 alongside Type 2.
- The FCA register lists FRN 610534 against China Merchants Securities (UK) Limited, but its status there is “No longer authorised”, not the authorised status our earlier review had assumed (effective 12/11/2025).
- The Korea subsidiary, China Merchants Securities (Korea) Co., Ltd., appears in the Financial Supervisory Service (FSS) directory of supervised financial institutions, which we checked on 30 September 2026; the directory does not show licence types, so the Multi-Securities Business License our earlier review names is not itself shown there. CMS’s own about page states its Korea subsidiary is regulated by the FSS and focused on multi-securities business.
- Our search of 1,441 warning-list entries mirrored from CySEC, the FCA and the FSC Mauritius found no match for this firm; that covers only the lists we mirror, not every regulator worldwide, and we ran a positive control on each of the 7 registers we searched directly before relying on any empty result.
- The firm operates separate account types for cash, margin, futures and the Wealth Management Connect schemes, according to its accounts page.
- Its accounts page states the firm has the right to re-pledge or otherwise dispose of securities held as collateral in margin accounts.
- Its Hong Kong asset-management arm’s terms of use disclaim liability for consequential, incidental, special, punitive or exemplary damages arising from use of the website.
- The firm’s client-announcements page carries repeated notices warning of websites impersonating the company and of fraud and pump-and-dump scams using its name.
Who regulates CMS, and where that gets complicated
The name “CMS” on this page covers a group of separately licensed companies, not one regulated entity. The website itself is run by China Merchants Securities International Company Limited, but the Hong Kong SFC Public Register of Licensed Persons and Registered Institutions shows the actual Type 1, 2, 4, 6 and 9 licences sitting with a related company, China Merchants Securities (HK) Co., Limited, under CE reference AAI650, active, with one licensing condition and no public disciplinary action on record. A separate accounts page names yet another entity, China Merchants Securities (Hong Kong) Limited, as the counterparty referred to on that page as the Company (本公司), for cash, margin and futures accounts, and the firm’s asset-management terms are published in the name of China Merchants Securities Asset Management (Hong Kong) Limited. A reader opening an account needs to check which of these names is actually on their account agreement.
Outside Hong Kong, the picture is thinner. The FCA register confirms FRN 610534 belongs to China Merchants Securities (UK) Limited, but its current status there is “No longer authorised” rather than the authorised status the earlier review had assumed. China Merchants Securities (Korea) Co., Ltd. is listed in the Financial Supervisory Service directory of supervised institutions, which matches the firm’s own statement that its Korea subsidiary is regulated by the FSS; the directory does not show which licence it holds.
What China Merchants Securities’ own account terms say about client assets
The Hong Kong accounts page distinguishes a cash account, where a client pays the full amount for purchased securities with no collateral borrowing, from a margin account, where the client borrows against securities held as collateral. For the margin account, the same page states the company has the right to re-pledge or otherwise dispose of the securities held in that account. Separately, the asset-management arm’s terms of use reserve the right to amend the site and its terms at any time without notice, and disclaim liability for consequential, incidental, special, punitive or exemplary damages from any use of the site. None of the pages in our evidence state a minimum deposit, a leverage cap, or a negative balance protection policy for retail clients.
Key Takeaways
What the Hong Kong SFC register confirms about CMS
- We searched the Securities and Futures Commission (SFC) Hong Kong register directly. It shows CE reference AAI650, China Merchants Securities (HK) Co., Limited, holding Type 1 (Dealing in Securities), Type 2 (Dealing in Futures Contracts), Type 4 (Advising on Securities), Type 6 (Advising on Corporate Finance) and Type 9 (Asset Management), each marked active, under a subsidiary of the same name as the entity the claim attributed the licences to.
- The SFC register records no public disciplinary action against that CE reference, and the licence carries one licensing condition; the register does not spell out what that condition is in what we pulled.
- The claimed Type 5 licence (Advising on Futures Contracts) sits with China Merchants Futures (HK) Co., Limited, CE AGO928, not with the securities company. That is a gap in the claim, not a finding either way about whether CMS holds it.
- Before treating any of this as an absence rather than a miss, we ran a positive-control search against a firm known to be listed on the SFC register and on each of the other six registers we queried, so an empty result elsewhere in this review means the firm genuinely was not found, not that the search itself failed.
The FCA licence claim that doesn’t hold up
- The FCA register does hold FRN 610534 under China Merchants Securities (UK) Limited, but its status there is “No longer authorised,” effective 12/11/2025, not the authorised status the claim implied. Anyone dealing with a UK-branded CMS entity on the strength of this number should check the FCA register themselves before relying on it.
- A claimed Financial Supervisory Service (FSS) South Korea licence, covering a Korea subsidiary’s multi-securities business, checks out as far as the FSS directory goes: China Merchants Securities (Korea) Co., Ltd. is listed there as a supervised institution. The directory gives no licence type, so the multi-securities scope rests on the firm’s own wording.
- We searched 1,441 warning-list entries mirrored from CYSEC, the FCA and the FSC Mauritius, and CMS matched none of them. That covers only the regulators we mirror, not a global sweep, but it is a clean result worth recording as far as it goes.
What China Merchants Securities (Hong Kong)’s own account terms allow
- The firm’s account-types page states that in a margin account (保證金賬戶), the company has the right to re-pledge or otherwise dispose of securities a client has posted as collateral. A client who deposits securities against margin borrowing is exposed to what the firm does with those securities afterward, not just to their own trading risk.
- By contrast, the cash account (現金賬戶) terms on the same page require the client to pay the full purchase price with no collateral borrowing permitted, so the rehypothecation exposure sits specifically with margin and futures accounts, not the cash account.
- China Merchants Securities Asset Management (Hong Kong)’s website terms exclude the firm’s liability for consequential, incidental, special, punitive or exemplary damages arising from any use of the site, and reserve the right to amend the site and its terms, or to update, revise, correct or discontinue published information, at any time without notice and without liability. The same terms disclaim responsibility for losses from third-party interception of information or from transmission delay or interruption.
Fees, deposits and payments
- The only fee figures in our evidence come from our earlier review, not from a page we fetched: a bond custody fee of 0.04%, a bond transaction fee of $30, and a bond early redemption fee of $80. We have no first-hand equity, futures or account-opening fee schedule to check these against.
- The firm’s own fees page states that deposit notices or slips for securities settlement must reach the company by 4:00 PM the same day, or the deposit is credited the next business day; futures deposit slips must be emailed to futures@cmschina.com.hk under the same same-day cutoff.
- The same page states the company does not accept cash deposits, and describes a linked-transfer option for clients who have set up a bank-securities link with China Merchants Bank (招商銀行).
Platforms confirmed on the firm’s own site
- The firm’s own software download page offers its CMS International trading software for Windows and Mac, an iPhone app (on the App Store in Hong Kong, Macau and overseas only), and an Android app on Google Play and as an APK, and its site links a web trading login. CQG Trader, SPTrader and Sharp Point, named in the earlier review, do not appear on that page.
- The earlier review’s negative balance protection discussion is described by the reviewer as speculation drawn from general SFC, FCA and FSS regulatory regimes, not from a CMS policy page; no margin call level or stop-out level is confirmed anywhere in our evidence.
- A restricted-country list attributed to the firm in an earlier version of the review could not be tied to anything the broker publishes; a later check of the homepage, legal, terms and legal-documents pages found no published restricted-country statement to confirm it against.
Support channels and site notices
- The firm’s contact page lists separate phone lines for Hong Kong and mainland China general service, HK stock enquiries, asset management enquiries, Wealth Management Connect, day and night securities trading, and futures trading, plus a general email (online@cmschina.com.hk), a complaints hotline ((852) 3189 6191) and complaints email (complaint@cmschina.com.hk), and physical offices in Central and Kwun Tong, Hong Kong, and Seoul, South Korea.
- The firm’s own about/announcements page carries client notices warning about websites impersonating the company and about fraud and pump-and-dump schemes using its name, alongside a separate notice on Japan stock trading restriction measures dated 2025-06-10 whose content our evidence does not detail.
Licenses & Regulation
The site under review is run by China Merchants Securities International Company Limited, described on CMS’s own “about” page as the Hong Kong international investment banking arm of the dual-listed China Merchants Securities Co., Ltd. (6099.HK / 600999.SH), itself part of the China Merchants Group conglomerate. Account opening sits with a related but separately named entity: the firm’s account-types page names China Merchants Securities (Hong Kong) Limited as the operating counterparty (“the Company” (本公司)) for cash, margin and futures securities accounts, while a further related company, China Merchants Securities Asset Management (Hong Kong) Limited, publishes the fund pages and asset-management terms of use. A Korea office and a UK subsidiary, China Merchants Securities (UK) Limited, also appear in the material under review.
What the SFC register shows for China Merchants Securities
We searched the Hong Kong Securities and Futures Commission’s Public Register of Licensed Persons and Registered Institutions directly, running a positive control against a firm known to be listed before treating any empty result as an absence. The claim under review attributed Types 1, 2, 4, 5, 6 and 9 to “China Merchants Securities International Company Limited and/or its subsidiaries,” without naming a specific licensed entity. On the register, five of those licences are held, active, by a subsidiary under a related name, China Merchants Securities (HK) Co., Limited, under CE reference AAI650: Type 1 (Dealing in Securities), Type 2 (Dealing in Futures Contracts), Type 4 (Advising on Securities), Type 6 (Advising on Corporate Finance) and Type 9 (Asset Management). The register records no public disciplinary action against CE AAI650, and the licence carries one licensing condition, which the register entry we pulled does not itself spell out. Type 5, Advising on Futures Contracts, is held by China Merchants Futures (HK) Co., Limited under CE AGO928, which we checked on the SFC register on 29 September 2026. That is a gap in the claim, or in our matching, not a finding that the licence does not exist.
The FCA record for China Merchants Securities (UK) Limited
The material under review cites FRN 610534, held by China Merchants Securities (UK) Limited, as a UK authorisation. We checked that number against the Financial Conduct Authority register and it does not support that reading: the FCA register lists FRN 610534 as “No longer authorised,” with that status effective 12/11/2025. Anyone dealing with the UK entity on the strength of an FCA authorisation should treat that authorisation as lapsed rather than current.
Korea, and where our checking runs out
The firm’s own Hong Kong “about” page states that its Korea subsidiary is regulated by the Financial Supervisory Service (FSS) for multi-securities business, and the material under review separately names an FSS “Multi-Securities Business License” without quoting a licence number. The FSS directory of supervised financial institutions lists China Merchants Securities (Korea) Co., Ltd., which supports the first claim; it shows no licence types, so the second is confirmed only as far as the company.
Warning lists and what the account terms actually grant the firm
We searched 1,441 warning-list entries mirrored from CySEC, the FCA and the FSC Mauritius, and the name does not appear on any of them. That is a clean result across three regulators’ published lists, not a clearance from every regulator worldwide, and it covers only the lists we mirror.
Separate from licensing status, the account terms we read set out what a margin account actually exposes a client to. Under China Merchants Securities (Hong Kong) Limited’s account terms, securities a client deposits as collateral in a margin account can be re-pledged or otherwise dealt with by the firm, a standing right over margin collateral rather than something limited to a single trade. The asset-management entity’s own fund pages, separately, restrict their content to Hong Kong residents and disclaim responsibility for reliance on that material by anyone outside Hong Kong, which lines up with the Type 9 Asset Management licence sitting with the Hong Kong-registered CE AAI650 entity rather than with any separate offshore fund arm.
How to Trade
China Merchants Securities International’s own site lists its brokerage line as covering Hong Kong and overseas securities, Hong Kong futures, bonds, funds, exchange traded funds and stock options, alongside a separate derivative investment products line, according to the firm’s website menu structure. The same page lists commodities as its own business, described as over the counter precious metals and energy derivatives plus precious metals spot margin and physical trade and lease services, and a private equity line investing the firm’s own capital and managed fund capital into Greater China companies in technology, healthcare and consumer sectors.
How CMS Hong Kong structures accounts
The operating entity for cash, margin and futures securities accounts is named on the firm’s accounts page as China Merchants Securities (Hong Kong) Limited. That page sets out five account types. A cash account requires the client to pay the full amount for any securities purchased and does not permit collateral borrowing. A margin account lets the client borrow from the firm against securities purchased or other securities held in the account as collateral. A futures account is for trading futures contracts. The page also lists a Southbound Wealth Connect account, for mainland qualifying investors buying products sold by Hong Kong and Macau banks and securities firms, and a Northbound Wealth Connect account, for Hong Kong and Macau qualifying investors buying products sold by mainland banks and securities firms.
The margin account terms on that same page give CMS a right worth flagging: it states the company has the right to re pledge or otherwise dispose of the securities held in these accounts as collateral. That means securities a client deposits as margin collateral can be rehypothecated or dealt with further by the firm, which puts the client’s collateral at risk if the firm runs into its own counterparty or insolvency problems, not just if the client’s own position goes wrong.
Platforms on CMS’s own software page
CMS’s own software download page, which we read directly, offers its CMS International trading software (招商證券國際版) for Hong Kong, US and China A and B shares in five versions: Mac, Windows, iPhone, Android through Google Play, and an Android APK. The iPhone version is listed for the App Store outside mainland China only, in Hong Kong, Macau and overseas. The site header also links a web trading login at trade.cmschina.com.hk, alongside separate logins for overseas stocks, global futures and the web version of the Cross-boundary Wealth Management Connect platform. The same page lists CQ Key, which it describes as a two factor security code app for overseas stock trading, not a charting tool. The futures software list sits behind a client login, so CQG Trader, SPTrader and Sharp Point, which the earlier review named, are not confirmed on any page we could read.
Funding a CMS account and settlement timing
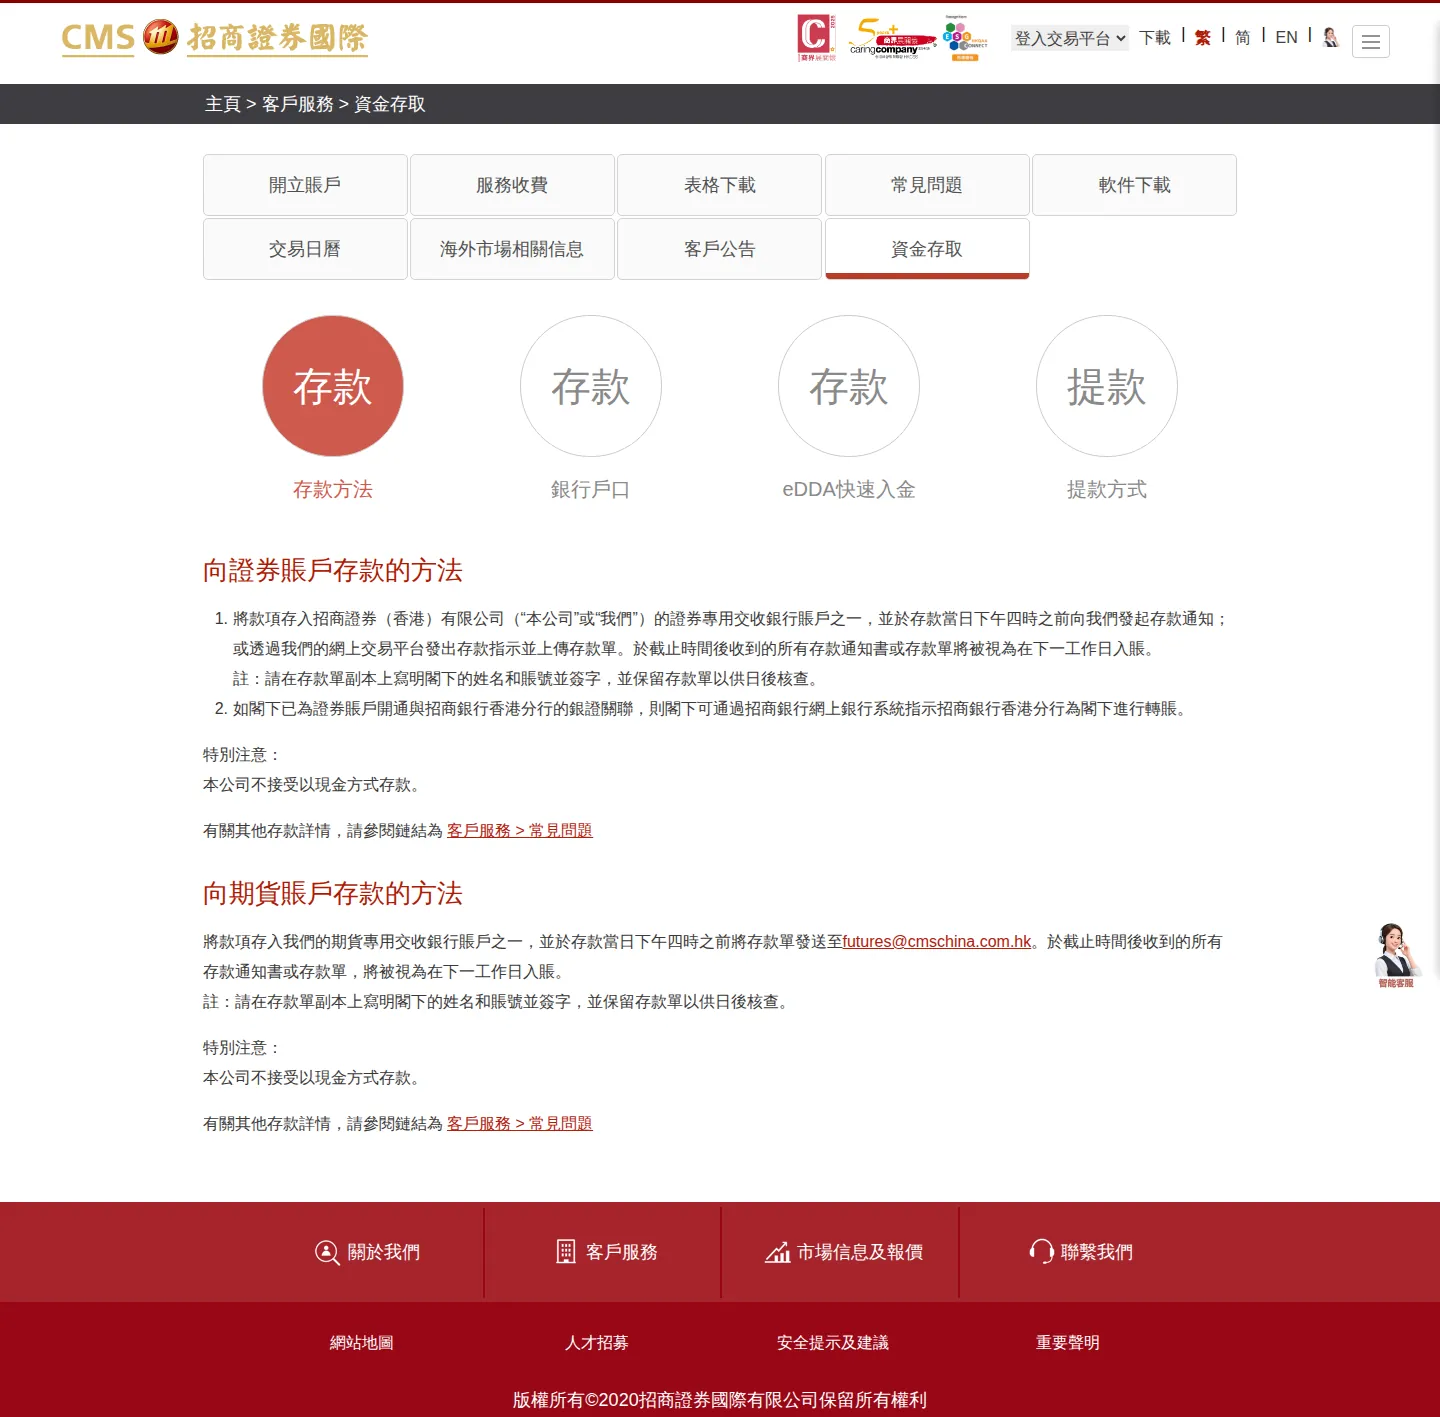
The firm’s fees page sets out how money reaches an account. For securities, a deposit notice or slip must be sent to the company before 4:00 PM on the day of the transfer; anything received after that cutoff is credited on the next business day. For futures, the deposit slip must instead be emailed to futures@cmschina.com.hk, again before the 4:00 PM cutoff. Clients who have linked a China Merchants Bank account can also transfer through CMB’s own online banking system. The same page states plainly that the company does not accept cash deposits.
The earlier review also reports three charges tied to bond trading that we have not verified on the firm’s own pages: a 0.04% bond custody fee on fixed income holdings, a $30 bond transaction fee, and an $80 fee for early redemption of a bond holding. Because these come from the earlier review rather than a page in our evidence, treat the figures as reported rather than confirmed.
Terms that bind a client using the site and its research
The terms of use published for the asset management arm’s fund pages give the firm several one sided rights. Under the Terms of Use section, the firm states it can amend the website and its terms of use at any time without notice, and can update, revise, correct or discontinue site information, content and descriptions at its sole discretion, again without liability or notice. Under the Disclaimer of Warranties and Limited Liability section, the firm excludes liability for consequential, incidental, special, punitive or exemplary damages arising from any use of the website, and separately disclaims responsibility for losses arising from third party interception of information or services, transmission interruption, transmission delay, or incorrect data transmission, which shifts that risk onto the client. Under the Intellectual Property section, content on the site is stated to be for the recipient’s own use only and may not be copied, published, forwarded or otherwise distributed to any other person.
The same fund pages restrict who the material is meant for: they state the content is intended for Hong Kong residents and that CMS disclaims responsibility for use by, or reliance on the material by, persons resident outside Hong Kong. They also state that the funds described are offered only in jurisdictions where authorised for promotion and sale, and that products and services are not necessarily available in every jurisdiction.
Separately, the firm’s own client announcements page lists a notice dated 10 June 2025 on Japan stock trading restriction measures (有關日本股票交易限制措施). The announcements page does not spell out the content of that restriction in the material we fetched, so a client trading Japanese stocks through CMS should check the notice directly rather than assume its scope.
Account Types
China Merchants Securities (Hong Kong) Limited’s own account pages set out five account types, each tied to a different way of holding or trading assets rather than to a tiered pricing ladder. The firm’s account-types page describes them as follows.
The account types CMS Hong Kong offers
- Cash Account (現金賬戶): CMS’s page states the client pays the full amount for any securities purchased and no collateral borrowing is permitted on this account.
- Margin Account (保證金賬戶): the same page states the client can borrow funds from the company against securities purchased, or other securities held in the margin account, as collateral. The page goes further: the company retains the right to re-pledge or otherwise dispose of the securities held in these accounts. That clause means a security a client deposits as margin collateral is not simply held for them; it can be re-pledged or dealt with by the firm, which puts the client’s collateral at risk if CMS itself runs into counterparty or insolvency trouble.
- Futures Account (期貨賬戶): described on the same page simply as the account used for trading futures contracts.
- Southbound Wealth Connect Account (南向通帳戶): for mainland-qualified investors to invest in eligible products sold by Hong Kong and Macau banks and securities firms. The firm’s page lists a mainland second-generation ID card and a bank card in the same name as requirements to open one.
- Northbound Wealth Connect Account (北向通帳戶): the mirror product, for Hong Kong- and Macau-qualified investors to invest in eligible products sold by mainland banks and securities firms. The firm’s page lists a Home Return Permit (回鄉證) as a requirement.
The account pages we fetched describe what each account is for and, for the two Wealth Connect accounts, what identity documents are needed to open one. They give no minimum deposit figure for any of the five account types, and no published commission schedule tied to a specific account tier.
What China Merchants Securities charges, on the figures we have
The figures available to us for this review came from the earlier published review rather than from a CMS fee page we fetched directly, so they are reported here as findings of that earlier review, not as CMS’s own published terms: a bond custody charge of 0.04% on fixed income holdings, a bond transaction fee of $30, and a bond early redemption fee of $80 for closing out a bond position early. None of the account pages in our evidence repeats these figures, so they cannot be verified against the firm’s own wording here.
Funding an account is restricted in a way the firm does state on its own fee page: the company does not accept cash deposits. Money for a securities settlement account has to arrive by bank transfer, with a deposit notice or slip submitted before 4:00 PM the same day or the deposit is credited the next business day; funding a futures settlement account works the same way but the slip goes to futures@cmschina.com.hk before the same 4:00 PM cutoff. Clients with a linked China Merchants Bank account can also transfer in through CMB’s own online banking system.
The wider product range sitting behind these accounts
The firm’s brokerage menu lists Hong Kong and overseas securities, Hong Kong futures, bonds, funds, exchange-traded funds, and stock options as tradable through this account structure, alongside a separate commodities line covering OTC precious metals and energy derivatives, precious metals spot margin, and physical metals trade and leasing services. Private equity is run as its own business line, investing house capital and managed fund capital into Greater China companies in technology, healthcare and consumer sectors, which sits outside the retail account types above entirely.
What is not confirmed here
The account and fee pages in our evidence say nothing about negative balance protection, margin call levels, or stop-out levels for the margin or futures accounts described above; a reader relying on those figures should ask CMS for them directly rather than assume a standard industry setting applies. The site’s own client announcements page separately carries repeated notices warning clients about websites and individuals impersonating the company, which is worth knowing before treating any account-opening channel other than the firm’s listed offices and phone numbers as genuine.
Negative Balance Protection
Our evidence for this review does not contain a CMS page that sets out a margin call level, a stop out level, or a negative balance protection policy. Our earlier review says the same thing in its own words: the reviewer wrote that specific CMS policy details are not provided and that the analysis of loss limits rests on speculation about the general regimes CMS operates under (the SFC, the FCA and the FSS) rather than on anything CMS itself has published. We are restating that finding, not quoting it, because it came to us from the earlier review rather than from a page we fetched.
What the account structure tells us instead
What we can report firsthand comes from CMS’s own account pages, and it points at how losses could be amplified rather than at what caps them. The firm describes two relevant account types. In a cash account, the client pays the full amount for any securities purchased and no collateral borrowing is permitted, which by its nature limits loss to the capital put in. In a margin account, the client can borrow from the firm against securities they have purchased or other securities held in the margin account as collateral, and the terms go further: the company has the right to re-pledge or otherwise dispose of the securities held in these accounts. That clause means collateral a client deposits against a margin loan is not simply held for safekeeping. It can be rehypothecated or otherwise dealt with by the firm, which puts the client’s collateral at risk if CMS runs into its own counterparty or insolvency problems, on top of whatever loss the leveraged position itself produces. None of the account pages in our evidence state a margin call trigger level, a forced liquidation or stop out level, or a cap on how far a margin account can run into deficit.
What China Merchants Securities (HK)’s wider terms say about liability, not about loss limits
The related terms of use we read, published for the asset management arm, China Merchants Securities Asset Management (Hong Kong) Limited, set no margin call level, stop out level or cap on losses. They address a different question, which is what happens if something goes wrong on the firm’s side rather than the client’s. Under the heading of disclaimer of warranties and limited liability, the firm states it will not be liable for any consequential, incidental, special, punitive or exemplary damages arising from use of the website in any way, and separately disclaims responsibility for losses arising from third party interception of information or services, transmission interruption, transmission delay, or incorrect data transmission. Read together, these clauses shift a broad category of loss onto the client whenever the cause is a website fault or a data or communications failure, and they say nothing about how a losing trading position is capped or closed out. The same terms of use also reserve the firm’s right to amend the site and its terms at any time without notice, and to update, revise, correct or discontinue published information at its sole discretion without liability or notice, which means any account or margin information CMS does publish elsewhere could change without a client being told in advance.
What the registers add, and what they do not
The Hong Kong Securities and Futures Commission register confirms that China Merchants Securities (HK) Co., Limited, CE reference AAI650, actively holds Type 1 dealing in securities and Type 2 dealing in futures contracts licences, alongside Type 4, Type 6 and Type 9, with one licensing condition attached and no public disciplinary action recorded. A licence to deal in securities and futures is not the same thing as a published margin policy, and the register check does not state a margin call or stop out rule, so we are not treating the licence as evidence of one. Separately, the FCA register shows FRN 610534, held by China Merchants Securities (UK) Limited, as no longer authorised as of 12 November 2025, which is a change in that UK entity’s status rather than a finding about margin terms at the Hong Kong entity this review otherwise concerns. We also searched 1,441 warning list entries mirrored from CySEC, the FCA and the FSC Mauritius, and CMS appears on none of them, which is a clean result but, like the licences, it has no bearing on whether a stop out level or negative balance protection exists.
Put plainly, the honest statement here is one of absence of evidence rather than an absence of a policy. CMS’s margin account terms establish that a client can borrow against collateral, and that CMS can re-pledge that collateral, but the pages in our evidence do not say at what point a margin account triggers a call, at what point it is closed out, or whether a client can end up owing CMS more than they deposited. A prospective client trading on margin with CMS should ask for that policy in writing before funding an account, rather than assume it matches practices at other brokers.
Trading Instruments
CMS’s own site menus, fetched from its Hong Kong pages, list a broad brokerage lineup under its brokerage business (經紀業務): Hong Kong and overseas securities (香港證券 / 海外證券), futures (香港期貨), bonds (債券), funds (基金), ETFs (交易所買賣基金) and stock options (股票期權), alongside a separate derivative investment products (衍生投資產品) line. A distinct business line, commodities (大宗商品), covers OTC precious metals and energy derivatives, described on the same pages as including precious metals spot margin and physical trade and lease services (貴金屬現貨保證金及實物貿易與租賃服務). A further line, private equity investment (私募股權投資), covers own-capital and managed private equity funds investing in Greater China companies in technology, healthcare and consumer sectors. None of this is a full instrument list with contract specifications, tradable exchanges, or minimum lot sizes; it is a menu of business lines, and a client would need to open an account to see what is actually tradable on it.
Account types and what they permit
CMS’s own account pages, published under the operating entity China Merchants Securities (Hong Kong) Limited, set out five account types with different asset access. A cash account (現金賬戶) requires the client to pay the full amount for securities purchased and does not permit any collateral borrowing. A margin account (保證金賬戶) lets the client borrow against securities they hold as collateral, and the account terms state directly that the firm has the right to re-pledge or otherwise dispose of securities held in these accounts (有權將這類賬戶內的證券進行再行抵押或作其他處置). A futures account (期貨賬戶) covers futures contract trading. Two further accounts, Southbound Wealth Connect (南向通) and Northbound Wealth Connect (北向通), route Mainland and Hong Kong/Macau qualified investors into products sold by banks and securities firms across the border, and each carries its own identity-document requirement: a Mainland second-generation ID card and same-name bank card for the southbound route, a home-return permit for the northbound one.
Where the fee list and the asset menu don’t line up
The only priced figures in our evidence, carried over from the earlier review rather than fetched fresh from CMS’s own pages, cover bonds alone: a 0.04% bond custody fee, a $30 bond transaction fee, and an $80 bond early redemption fee. Nothing in the evidence prices trading in the securities, futures, ETF, stock options, commodities or private equity lines that CMS’s own menu lists, and nothing here confirms minimum lot sizes, available exchanges, or margin requirements for any of them beyond the account-level description above. A reader weighing a specific instrument, a Hong Kong stock, a futures contract, a precious metals position, has no published cost figure to check it against from what we hold.
Rehypothecation risk that sits inside the margin account
The clause on the margin account matters beyond a general risk warning: it applies specifically to securities the client deposits as margin collateral, and it gives the firm the right to re-pledge or otherwise deal with them. A client who opens a margin account to trade on margin is, by that account’s own terms, accepting that the securities backing the position may be re-pledged elsewhere, which adds counterparty and insolvency exposure on top of the ordinary market risk of the position itself.
Country and geographic access
The asset management arm’s terms of use, published separately from the brokerage pages, restrict the fund pages to Hong Kong residents and disclaim responsibility for use by, or reliance on the material by, persons resident outside Hong Kong. The same terms state products and services are not necessarily available in all jurisdictions and that any funds described are offered only where authorised for promotion and sale. An earlier version of this review listed named restricted countries for CMS; a later check of the homepage, legal, terms and legal-documents pages found no published restricted-country statement to support that list, so it has been dropped here. A reader in a jurisdiction not obviously Hong Kong or Mainland China should confirm access in writing with CMS before assuming a given asset class is open to them.
Client warnings on the firm’s own announcements page
CMS’s own client-announcements page carries repeated notices warning of impersonation and fraud, including warnings to beware of suspicious websites impersonating the company (謹防可疑網站假冒我司) and to beware of fraud through impersonation (謹防不法分子假冒他人手段從事詐騙活動), plus a separate notice on pump-and-dump (唱高散貨) schemes. The same page posted a notice dated 2025-06-10 on Japan stock trading restriction measures, whose content is not detailed in the pages we hold; a client trading Japanese equities through CMS should check that notice directly rather than assume normal access continues unchanged.
Education & Analysis
China Merchants Securities International’s own pages describe business lines and account categories, not a trading platform or a charting package. Under the Brokerage (經紀業務) menu the firm lists Hong Kong and overseas securities, Hong Kong futures, bonds, funds, ETFs, stock options and what it calls derivative investment products (衍生投資產品), alongside a separate commodities line covering OTC precious metals and energy derivatives, precious metals spot margin, and physical trade and lease services, and a private equity line investing the firm’s own capital and managed funds in Greater China technology, healthcare and consumer companies. None of that tells a reader what software sits between a client and those markets, what charting is built into it, or what order types and indicators it carries. The pages we fetched simply don’t cover that ground.
What the earlier review reported about China Merchants Securities’ platforms
The pages we read do not describe the charting or analysis tools inside the CMS International software; the software download page links user guides but sets out no feature list. Our earlier review described a CQ Key app with advanced charting, but CMS’s own download page describes CQ Key as a two factor security code app for overseas stock trading, so that description does not hold. It also named CQG Trader and SPTrader as professional platforms for futures and Hong Kong trading, and Sharp Point as a futures desktop package. The futures software list sits behind a client login, so none of the three is confirmed on a page we could read.
What China Merchants Securities’ account pages confirm instead
What we could confirm from China Merchants Securities (Hong Kong) Limited’s own account-types page is the account structure a client trades through, not the software on top of it. There is a cash account (現金賬戶), where the client pays the full price of any security purchased and no collateral borrowing is permitted; a margin account (保證金賬戶), where the client can borrow against securities held as collateral and, under that same section, the firm states it has the right to re-pledge or otherwise dispose of the securities held in margin accounts; a futures account (期貨賬戶) for trading futures contracts; and Southbound and Northbound Wealth Connect accounts for mainland and Hong Kong/Macau investors, each gated on specific identity documents, a mainland second-generation ID card and a same-name bank card for the Southbound account, a home-return permit for the Northbound account. The page stops at account eligibility and collateral treatment. It does not describe an order ticket, a charting window, watchlists, or any analysis tool a client would see after logging in.
The earlier review also recorded that the firm’s website was, at the time it checked, experiencing accessibility issues. That observation came from the earlier review rather than our own fetch, so we can’t say whether it still holds today or what page was affected. Put together, the honest state of the evidence on charts and analysis tooling is thin on the firm’s own side: business lines are documented in detail, five platform names circulate from an earlier review we could not verify against any China Merchants Securities page, and nothing we fetched shows a feature list, screenshot or download link for a trading or charting product under the firm’s name.
Special Offers
We looked for a deposit bonus, a trading credit, a fee rebate, a referral scheme or any other promotional offer on the pages in our evidence, and found none. The pages we fetched, the firm’s UAE accounts page, CMS’s UAE fees page, the firm’s UK accounts page and the firm’s UAE home page, describe CMS’s account types, its fund and asset-management terms of use, and its deposit mechanics. None of them raises the subject of promotions, discounts or introductory offers, in either direction.
What the CMS pages actually cover instead
The accounts page sets out five account types: a cash account, a margin account, a futures account, and two Wealth Connect accounts (Southbound, for mainland investors buying Hong Kong and Macau products, and Northbound, for Hong Kong and Macau investors buying mainland products, gated on a home-return permit). None of the five carries a stated opening incentive, fee waiver or promotional tier; the distinctions drawn are about collateral and borrowing, not price.
The fees page covers deposit mechanics rather than pricing: a bank transfer to the designated securities settlement account must be notified, or the deposit slip uploaded, before 4:00pm the same day or it is credited the next business day; a futures deposit slip has to be emailed to futures@cmschina.com.hk under the same same-day cutoff; clients with a linked China Merchants Bank account can transfer through CMB’s own online banking; and CMS states plainly that it does not accept cash deposits. These are processing rules, not conditions attached to any offer.
The only fee figures on file, and why they aren’t a discount
An earlier review of this firm is the only source in our evidence for any specific charges: a bond custody fee of 0.04%, a bond transaction fee of $30, and a bond early redemption fee of $80. We did not read the document those figures came from, so we can’t confirm them against CMS’s own fee schedule, but as reported they read as standard fixed-income charges rather than as a promotional rate, an introductory discount, or a credit tied to any condition.
The one line CMS itself uses the word “promotion” in
The asset-management terms of use state that the funds described are offered only in jurisdictions where they are authorised for promotion and sale, and that the products and services are not necessarily available in all jurisdictions. That is a legal gate on who CMS is allowed to market a fund to, not an offer extended to a class of new clients, and the same page restricts the content generally to Hong Kong residents and disclaims responsibility for anyone outside Hong Kong who relies on it.
Nothing in the material we searched, including the 7 register lookups and the 1,441-entry warning-list search we ran on this firm, touches promotional conduct one way or the other; those checks were run for licensing status and warning-list presence, not for marketing offers, and we are not extending them to a claim they weren’t built to support.
Opening an Account
China Merchants Securities (Hong Kong) Limited’s account pages describe five distinct account types, and which one a prospective client can open depends on residency and paperwork rather than a single unified sign up flow.
The account types China Merchants Securities offers
- Cash Account (現金賬戶). The firm’s account pages state that the client pays the full amount for any securities purchased and that no collateral borrowing is permitted on this account type.
- Margin Account (保證金賬戶). The same pages state that a client can borrow money from CMS against securities purchased or other securities held in the margin account as collateral. The pages also state that the firm has the right to re-pledge or otherwise dispose of the securities held in these accounts, so a client depositing shares as margin collateral is exposed to what happens to those shares if CMS deals with them further.
- Futures Account (期貨賬戶). Described on the same pages as the account used for trading futures contracts.
- Southbound Wealth Connect Account (南向通帳戶). The account pages describe this as the route for qualified mainland investors to invest in eligible products sold by Hong Kong and Macau banks and securities firms, and list a PRC second generation identity card and a bank card in the same name as requirements.
- Northbound Wealth Connect Account (北向通帳戶). The mirror route for qualified Hong Kong and Macau investors to invest in eligible products sold by mainland banks and securities firms, for which the pages list a Home Return Permit as a requirement.
Funding an account once it is open
The firm’s fee page sets a same day cutoff on deposits: a deposit notice or slip submitted to the designated securities settlement account before 4:00 pm is credited the same day, and anything received after that cutoff is credited the next business day. Deposits to the designated futures settlement account follow the same 4:00 pm cutoff, but the slip has to be emailed to futures@cmschina.com.hk rather than submitted through the securities channel. Clients who already hold a linked China Merchants Bank account can transfer funds through CMB’s own online banking system instead. The same fee page states plainly that the company does not accept cash deposits.
Who the firm will not open an account for
The fund pages published by China Merchants Securities Asset Management (Hong Kong) Limited state that their content is intended for Hong Kong residents and that the firm disclaims responsibility for use of, or reliance on, that material by persons resident outside Hong Kong. The same pages state that the funds described are offered only in jurisdictions where they are authorised for promotion and sale, and that the products and services referred to are not necessarily available in every jurisdiction. An earlier version of this review listed specific countries, including Iran, North Korea, Syria and Cuba, as subject to the firm’s restrictions, but a check of the homepage, legal, terms and legal documents pages found no published restricted country statement to support that list, and it has been dropped here. A prospective client outside Hong Kong should put the question to the firm directly in writing before assuming either way.
Terms a client agrees to on opening
Alongside the re-pledging right on margin accounts noted above, China Merchants Securities Asset Management (Hong Kong) Limited’s terms of use state that the firm will not be liable for any consequential, incidental, special, punitive or exemplary damages arising from use of the website in any way, and separately disclaim responsibility for losses caused by third party interception of information, transmission interruption, transmission delay or incorrect data transmission. The same terms state that CMS may amend the website and its terms of use at any time without notice, and may update, revise, correct or discontinue the site’s information, content and descriptions at its sole discretion, without liability or notice to the client.
Getting help before or during account opening
The firm’s contact page lists a general Hong Kong customer service line at (852) 3189 6368, a mainland China toll free line at 400 1200 368, and a dedicated stock enquiry hotline at 400 8888 199, alongside two physical offices, one in Central, Hong Kong and one in Kwun Tong, Kowloon, both listing office hours of 9:00 am to 6:00 pm, Monday to Friday, and a general customer service email at online@cmschina.com.hk. A separate office in Seoul, South Korea is listed with its own phone number and email. The firm’s own client announcements, which we read on its about page, include repeated warnings to clients to watch out for websites impersonating the company and for fraud schemes using its name, which is worth keeping in mind when searching for the firm’s genuine account opening channels online.
Deposits & Withdrawals
Our evidence we fetched carries one page on how money moves in and out of CMS accounts, cmschina.com.hk’s fees page, and it describes bank transfer only. Two separate settlement rails are set out there, one for securities and one for futures, each tied to its own same-day cutoff.
How money gets into a CMS account
For a securities settlement account, the fees page states that a client must send the company a deposit notice or upload a deposit slip before 4:00 PM on the day of the transfer; a deposit notice or slip received after that cutoff is credited on the next business day rather than the same day. Futures deposits run on a separate rail: the same page states that the deposit slip must be emailed to futures@cmschina.com.hk, also before 4:00 PM the same day. Clients who hold a linked China Merchants Bank (CMB) account get a third route, transferring through CMB’s own online banking system once the bank-securities link has been set up. The page also states plainly that the company does not accept cash deposits, so there is no walk-in cash option regardless of which account type is being funded.
What the fees page does not carry is a deposit minimum, a transfer fee, or a list of accepted currencies for any of these three routes. Nothing in the pages we fetched sets out what a wire costs to send, whether CMS charges an incoming-transfer fee of its own on top of whatever the client’s bank charges, or how many business days a same-day-cutoff deposit actually takes to clear into a tradable balance.
What CMS’s own fee page does not say about withdrawals
The fees page we fetched sets out deposit cutoffs and email addresses in some detail, but it carries no matching section on withdrawals. There is nothing on that page, or in anything else we read, describing a withdrawal request process, a processing timeline, a minimum withdrawal amount, or a fee CMS itself charges to send money out. That silence covers withdrawals specifically; it does not establish that CMS charges nothing to withdraw, only that the withdrawal side of the page we hold not covered the deposit side.
Bond-related charges the fee pages do carry
Three figures reached us from the earlier review being rewritten, not from a page we fetched ourselves, so we report them as figures the prior review recorded rather than as CMS’s own published terms: a bond custody fee described at 0.04%, a bond transaction fee described at $30, and a bond early-redemption fee described at $80. None of the three carries a currency in what reached us, and none is something we can point to on a CMS page ourselves.
The margin account term that changes what “your money” means
The account-types page we read draws a real line between two of CMS’s account structures. The cash account (現金賬戶) requires the client to pay the full amount for any securities purchased and, in the firm’s own wording, does not permit any form of collateral borrowing. The margin account (保證金賬戶) works differently: the client can borrow from the company against securities purchased or otherwise held in the margin account as collateral, and the same page states that the company has the right to re-pledge or otherwise dispose of the securities held in these accounts. That is a rehypothecation right written into the account terms themselves, not a boilerplate risk warning, and it means a client who funds a margin account is not just depositing collateral CMS holds; CMS can pass those securities on or otherwise deal with them, which puts the client’s assets at risk on CMS’s own counterparty exposure, not only on the market.
Regulatory standing behind the transfer
The Hong Kong SFC register shows China Merchants Securities (HK) Co., Limited, CE reference AAI650, holding active Type 1 and Type 2 licences (dealing in securities and dealing in futures contracts) among the five licence types it carries, with no public disciplinary action recorded and one licensing condition attached. That is the entity standing behind the securities and futures settlement accounts described on the fees page. Separately, the FCA register shows a UK-linked entity, China Merchants Securities (UK) Limited, FRN 610534, with a status of “No longer authorised” rather than Authorised as of 12/11/2025; a reader moving money through the UK entity specifically, rather than the Hong Kong one, should check that status directly with the FCA before relying on it. A search of 1,441 warning-list entries mirrored from CYSEC, the FCA and the FSC Mauritius turned up no match for this firm.
Customer Support
China Merchants Securities International’s Hong Kong contact page lists no single support line but a set of department-specific numbers: a general Hong Kong customer service line at (852) 3189 6368, a Mainland China toll-free line at 400 1200 368, a stock enquiry hotline at 400 8888 199, and a separate enquiry line for China Merchants Securities Asset Management (Hong Kong) at (852) 2530 0698. Wealth Management Connect has its own pair of numbers, (852) 3189 6868 for Hong Kong callers and 400 1666 390 toll-free from the mainland. General customer service email is online@cmschina.com.hk, with a fax line at (852) 3101 0063.
How CMS splits support by product
The contact page separates securities trading support from futures support rather than routing everyone through one desk. Securities day trading has three Hong Kong numbers, (852) 3189 6369, 3189 6365 and 3189 6361, mirrored by three mainland toll-free equivalents (400 1200 369, 400 1200 361, 400 1200 365), plus a securities trading fax at (852) 2537 6283. Night trading in securities has its own pair of lines, (852) 3189 6673 and 3189 6672. Futures trading customer service runs on a separate number again, (852) 3189 6222, and the fees page names a dedicated inbox, futures@cmschina.com.hk, for futures deposit slips, which must be emailed before 4:00pm the same day or the deposit is credited the next business day. That page also states plainly that the company does not accept cash deposits.
Beyond phone and email, the firm lists three physical offices with stated hours. The Central, Hong Kong office (Exchange Square, Tower 1, 32nd floor) and the Kwun Tong, Kowloon office (Manulife Financial Centre, Tower B, 17th floor) both give office hours of 9:00am to 6:00pm, Monday to Friday, each with its own phone line, (852) 3189 6888 and (852) 3189 6666 respectively, and both routing general email to the same online@cmschina.com.hk address. A third office in Seoul, South Korea, keeps the same Monday-to-Friday, 9:00am-6:00pm hours, with its own phone number, (82) 02 6292 4031, and its own email address, cmskorea@cmschina.co.kr.
Complaints handling
The contact page names a dedicated complaints channel separate from general customer service: a complaints hotline at (852) 3189 6191 and a complaints email at complaint@cmschina.com.hk. The page does not describe a complaints procedure, an acknowledgement timeframe, or an escalation path beyond that hotline and address, so a client who wants to know how a complaint is actually handled once it is logged has only the contact point, not the process, to go on.
What binds a client who ends up in a dispute with CMS
The asset management terms of use, published by China Merchants Securities Asset Management (Hong Kong) Limited, carry several clauses that shape what a complaining client can actually recover or rely on. Under the heading Disclaimer of Warranties and Limited Liability (保證條款之免責聲明及有限責任), the firm states it will not be liable for any consequential, incidental, special, punitive or exemplary damages arising from use of the website in any way. The same section disclaims responsibility for losses arising from third-party interception of information or services obtained through the site, and for transmission interruption, delay or incorrect data transmission, which puts the risk of connectivity and interception failures onto the client rather than the firm.
Under Terms of Use (參閱條款及細則), the firm reserves the right to amend the site and its terms of use at any time without notice, and to update, revise, correct or discontinue site information, content and descriptions at its sole discretion, without liability or notice. A client relying on published information when raising a complaint has no guarantee that information will still read the same way by the time the complaint is resolved. Separately, under Intellectual Property (知識產權), the terms restrict a recipient of the site’s content from copying, publishing or forwarding it to any other person, which limits how a client can share what the firm has told them, for instance with an adviser or a regulator, without falling foul of the terms themselves.
On the account side, the accounts page describes the operating entity, China Merchants Securities (Hong Kong) Limited, as holding the right to re-pledge or otherwise dispose of securities held in margin accounts as collateral, which matters to a client complaining about what happened to assets they thought were merely pledged rather than handed over for the firm’s own use.
Fraud and impersonation warnings
The firm’s own client announcements page carries repeated warnings rather than a one-off notice: postings titled beware of suspicious websites impersonating the company (謹防可疑網站假冒我司), beware of fraud through impersonation (謹防不法分子假冒他人手段從事詐騙活動), and beware of pump-and-dump scams (有關慎防墮入「唱高散貨」騙局). A separate notice dated 10 June 2025 addresses Japan stock trading restriction measures, though the page in our evidence does not detail what those measures are. The recurrence of impersonation and fraud warnings on the firm’s own announcements page is worth a prospective client’s attention when verifying they are dealing with the genuine CMS contact points listed above rather than a lookalike.
Prohibited Countries
What the pages we fetched describe is restriction written into specific products and account types, not a country list: some CMS accounts are only open to people who can produce a particular residency document, and the asset management arm’s fund pages carry a standard non-solicitation notice rather than naming any jurisdiction.
Wealth Connect accounts tied to a specific ID document
Among the account types China Merchants Securities (Hong Kong) Limited lists for its cash, margin and futures business are two cross-border accounts. The account page describes the Southbound Wealth Connect account (南向通) as for Mainland Chinese qualified investors buying products sold by Hong Kong and Macau banks and securities firms, and states it requires a second-generation Mainland Chinese ID card and a bank card registered in the same name. The Northbound Wealth Connect account (北向通) runs the other way, for Hong Kong and Macau qualified investors buying Mainland bank and securities products, and the same page states it requires a Home Return Permit (回鄉證). As described, neither account can be opened without the matching document, which ties each one to a specific side of the Hong Kong/Macau-Mainland border.
What China Merchants Securities Asset Management (Hong Kong) tells visitors to its fund pages
The terms of use on China Merchants Securities Asset Management (Hong Kong) Limited’s fund pages state that the content is for Hong Kong residents, and that the firm disclaims responsibility for use of, or reliance on, that material by anyone resident outside Hong Kong. The same terms state that the funds described are offered only in jurisdictions where their promotion and sale is authorised, that the products and services are not necessarily available in every jurisdiction, and that the site is not intended for use where doing so would be prohibited by local law. None of this names a country; it puts the burden on the visitor to know whether their own jurisdiction permits them to be reading the page at all.
A country list an earlier review could not stand behind
An earlier version of this review named specific prohibited countries, including Iran, North Korea, Syria and Cuba. Its author later found no page on the firm’s site tying that list to a CMS policy, and removed it after checking the homepage, the legal pages, the terms and the legal-documents pages through an Indonesian connection on 27 July 2026, finding no published restricted-country statement there either. We have not reinstated that list here for the same reason: nothing in the pages we hold ties it to CMS.
The UK entity behind one of the licence numbers
One entity in the group, China Merchants Securities (UK) Limited, is licensed by the Financial Conduct Authority under reference 610534. We checked the FCA register directly, and as of 12 November 2025 it lists that entity’s status as “No longer authorised” rather than authorised. A client pointed toward that UK entity on the strength of its FCA number is being pointed at a licence the FCA’s own register does not currently show as active.
A trading restriction, separate from client eligibility
The firm’s own client announcements page carries a notice dated 10 June 2025 on Japan stock trading restriction measures (有關日本股票交易限制措施), alongside repeated warnings to clients about websites impersonating the company and about pump-and-dump schemes. That notice concerns restrictions on trading particular Japanese stocks, not which clients or countries can open an account, and the page we hold does not set out what the restriction measures themselves are.
Conclusion
China Merchants Securities International scores 5.1 out of 10 overall, built from regulation at 6.3, fees at 2, platform at 7, support at 5.3 and reviews at 4.8. The regulation figure sits in the middle because the Hong Kong licensing is real and active, but our earlier review also carried a UK licence claim that the FCA register now contradicts, and a Korean subsidiary the FSS directory lists as supervised but without naming its licence.
What the SFC register actually shows for China Merchants Securities
The claim we inherited attributed six SFC licence types to “China Merchants Securities International Company Limited and/or its subsidiaries”, which is not how a regulator’s register works. We searched the Hong Kong SFC Public Register of Licensed Persons and Registered Institutions directly and found the licences sit with one named subsidiary, China Merchants Securities (HK) Co., Limited, under CE reference AAI650. That entity holds Type 1 (Dealing in Securities), Type 2 (Dealing in Futures Contracts), Type 4 (Advising on Securities), Type 6 (Advising on Corporate Finance) and Type 9 (Asset Management), each shown as active, and the register records no public disciplinary action against it. The licence carries one licensing condition, which the register does not spell out further in what we pulled. Type 5, Advising on Futures Contracts, belongs to the futures subsidiary, China Merchants Futures (HK) Co., Limited (CE AGO928), active since 7 March 2005. That is a gap in the claim, not a finding either way about the firm.
The FCA licence our earlier review got wrong
The same earlier review listed FRN 610534, held by China Merchants Securities (UK) Limited, as an active FCA authorisation. We checked the FCA register directly and it shows the opposite: that firm’s status is “No longer authorised”, effective 12 November 2025. Anyone relying on the earlier write-up for UK coverage would be relying on a status that has since lapsed. The Korea subsidiary is listed by the Financial Supervisory Service as a supervised institution, though the directory does not confirm the multi-securities licence type.
Fees and platforms we could not verify firsthand
The three fee figures in our evidence, a 0.04% bond custody fee, a $30 bond transaction fee and an $80 bond early redemption fee, all reached us from the earlier published review rather than from a China Merchants Securities fee schedule we fetched ourselves. Platforms are different: the firm’s own software download page confirms its trading software for Windows and Mac, iPhone and Android apps and a web login, though CQG Trader, SPTrader and Sharp Point from the earlier review are not confirmed. A reader weighing the fee score should treat those fee specifics as secondhand until they see the firm’s current fee schedule directly.
Terms that bind a client
What we did read firsthand were the account and terms-of-use pages. Under the account-types section, a margin account clause gives the firm the right to re-pledge or otherwise dispose of securities a client has deposited as margin collateral, meaning those assets can end up rehypothecated rather than simply held. Separately, the asset-management terms of use disclaim liability for any consequential, incidental, special, punitive or exemplary damages arising from site use, disclaim responsibility for losses from third-party interception or transmission delay, and reserve the right to amend the site and its terms, or to update, revise, correct or discontinue published content, at the firm’s sole discretion and without notice. A separate clause restricts clients from forwarding fund and research content to third parties. None of these are unusual for a securities house, but they are worth reading before signing rather than after a margin call.
Support and the clean warning-list result
Support is where the firsthand material is strongest: separate phone lines for Hong Kong and Mainland China general service, stock enquiries, asset management, Wealth Management Connect, day and night trading desks, plus offices in Central and Kwun Tong, Hong Kong and in Seoul, and a named complaints hotline and email. We also searched 1,441 warning-list entries mirrored from CYSEC, the FCA and the FSC Mauritius, running a positive control first so an empty result means absence rather than a broken search, and China Merchants Securities appears on none of them. That check only covers the lists we mirror, not every regulator worldwide, but it is a clean result our earlier review never ran.
China Merchants Securities International holds active Hong Kong SFC licences under a named subsidiary with no recorded disciplinary action, but its UK FCA licence has lapsed and its fee details in this review are unverified secondhand claims: TrueBroker scores it 5.1 out of 10.
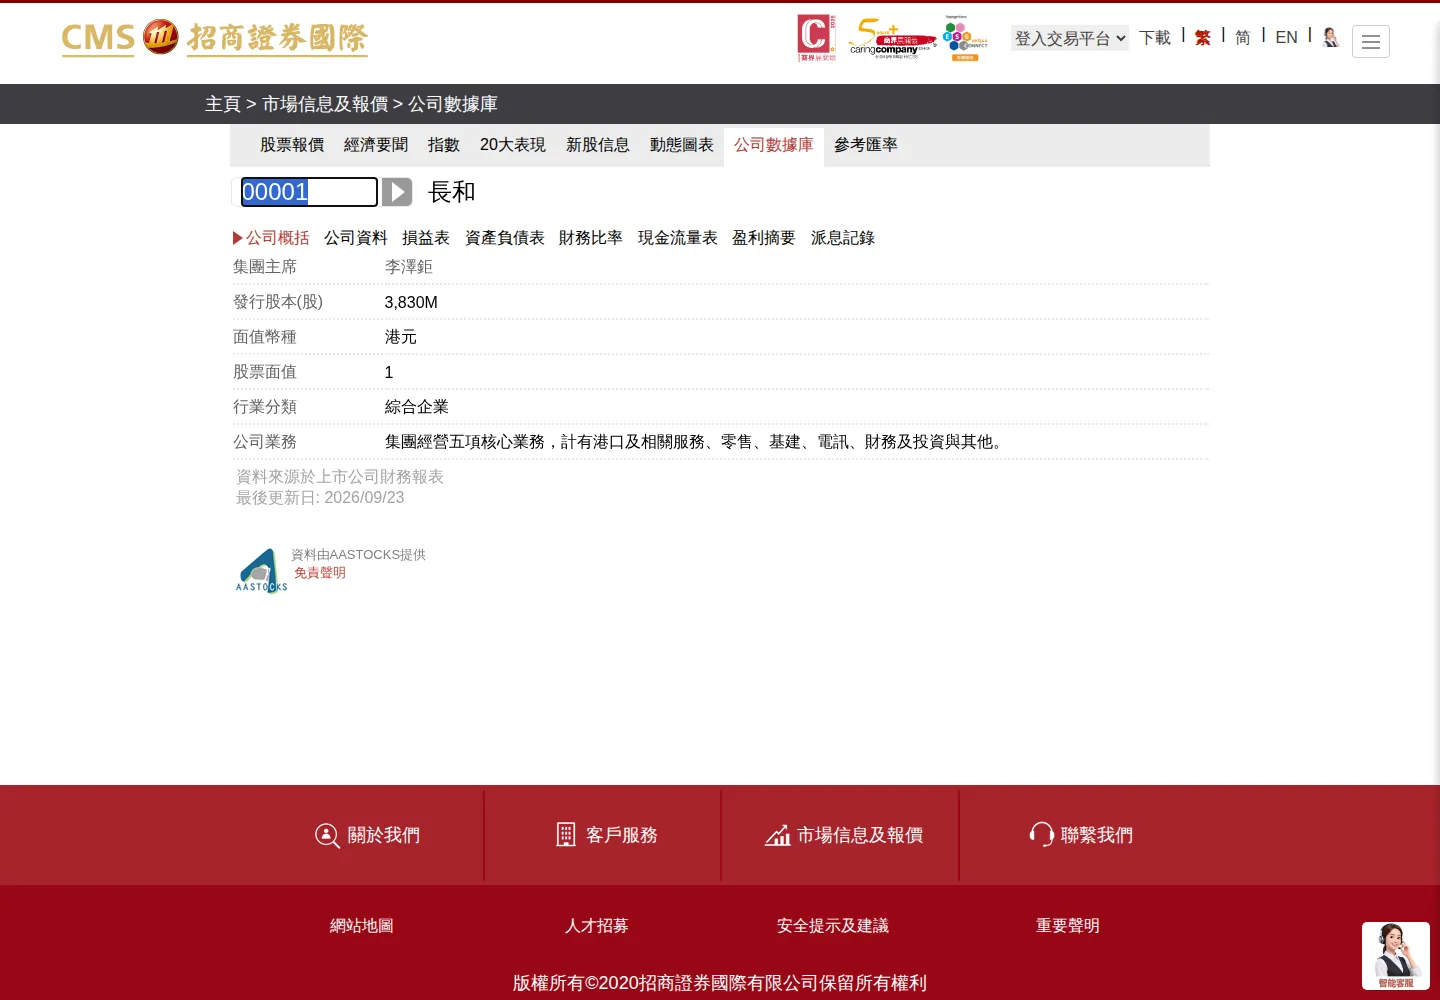
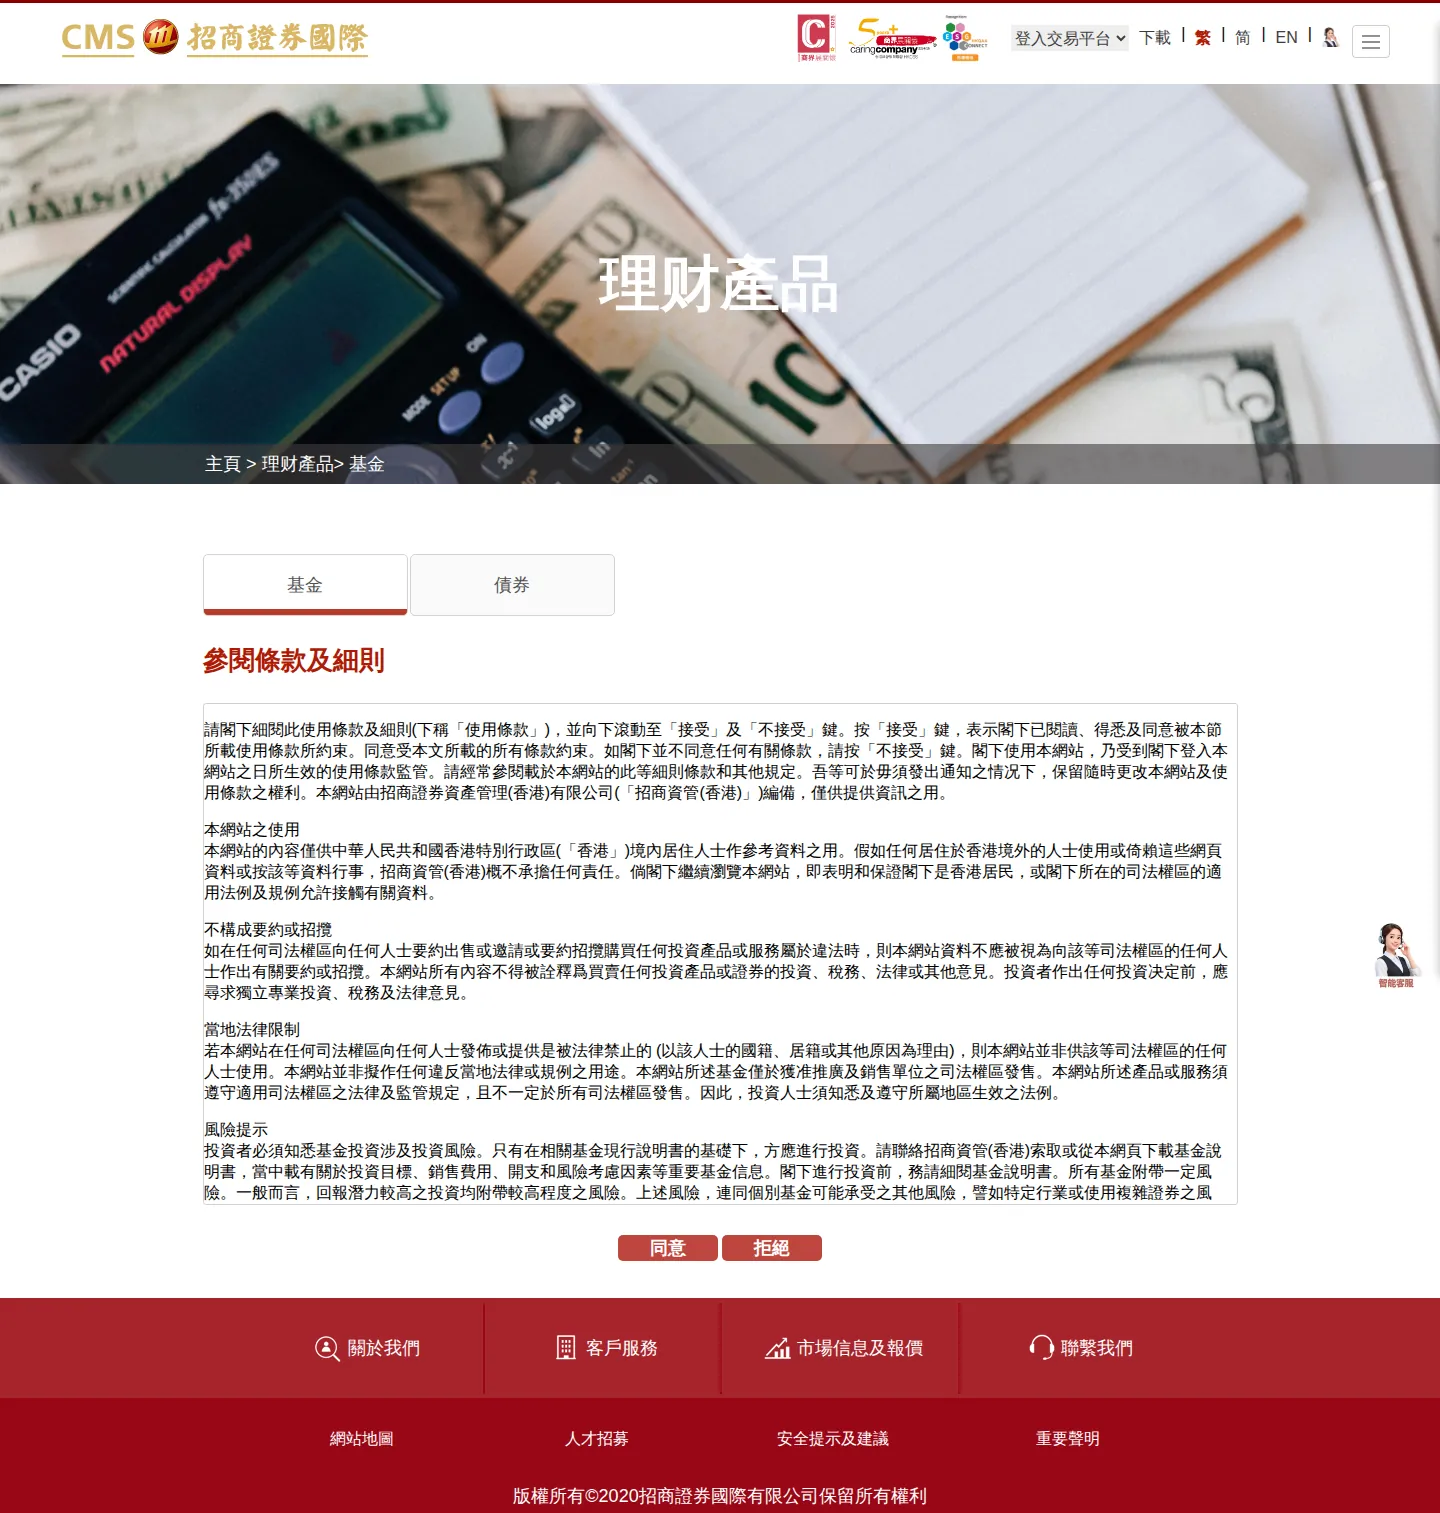
What we saw
Pages captured from CMS’s own site when this review was written. Brokers change their terms; these are what we read.
Score history
Recomputed daily; every move is on the record. The current score is always the latest row.
| Date | Score | Move |
|---|---|---|
| 2026-09-30 | 5.1 | ▲ |
| 2026-07-25 | 4.2 | ▼ |
| 2026-07-18 | 4.4 | ▼ |
| 2026-07-11 | 4.6 | · |
FAQ
Is CMS regulated?
Hong Kong’s SFC confirms active Types 1, 2, 4, 6 and 9 licences for China Merchants Securities (HK) Co., Limited (CE AAI650), a same-named subsidiary, not verified for the reviewed entity itself.
What does CMS charge in fees?
No published cost of trading was found on the broker’s own pages or documents.
What trading platforms does CMS offer?
Its own web platform, mobile app, and Windows and Mac desktop clients, per the firm’s software download page.
Is client money protected if CMS fails?
Under the SFC Hong Kong regime, compensation is capped at 500,000 HKD and there is no negative balance protection requirement.
How good are CMS's reviews?
Reviews average 3.31 stars, but from only 14 ratings, a small sample.
Is CMS regulated in Korea?
A Korea FSS licence claim exists but has not been checked against the register, a directory gap.
How this review works
Track CMS live: score moves and red notices, in your pocket.