CFD · CHECKED 10 OCT 2026
DBG Markets review.
An FCA licence on display whose holder says it has nothing to do with this group, and a domain the FCA lists as a clone.
RISKY
OUT OF 10
An FCA licence on display whose holder says it has nothing to do with this group, and a domain the FCA lists as a clone.
Each criterion is scored 1 to 10 from primary sources. The overall score is their unweighted mean. How scoring works.
- FRN 469459 is a genuine FCA authorisation, though it is held by an unaffiliated firm
- Authorised continuously since October 2007, a long history
- Registered UK entity, Companies House OC300984
- Register entry is current and unambiguous
- The offshore group's Australian and South African entities hold licences that verify on their regulators' own registers
- The register entry is current and unambiguous, with no status anomalies
- The offshore group is a verifiable business: its Australian company is active on the ABR
- Its own terms are explicit about which jurisdictions it will not serve
- The FCA entity is not permitted to hold or control client money
- UK client money protections cannot be assumed to apply to deposits
- Domain registered only in 2020 despite a 2007 authorisation
- Trading costs not verifiable from a primary source
- Instrument range and platforms unverified
- Support arrangements unverified
- Two active FCA clone warnings cover seven domains trading on this name
- dbgmarkets.com, the address our earlier review used, is parked and for sale at $6,295
- The only website the FCA publishes for the firm, dbglondon.co.uk, has an invalid TLS certificate
- Two unaffiliated companies trade as DBG Markets, and the UK one disavows the other
- The FCA licence displayed under “Group Offices” belongs to DBG MARKETS (UK) LLP, which states it is not affiliated with this group
- It holds an Australian licence while refusing Australian residents
- Its mandatory retail loss percentage is deferred to an unspecified future date
- A South African entity operates the Vietnam-facing site
Overview
DBG MARKETS (UK) LLP is authorised by the FCA under reference number 469459 and has been since October 2007, a long, unbroken authorisation. Companies House number OC300984.
One detail on that register entry deserves more attention than the authorisation itself. The FCA records this firm’s client money permission as “Not hold and not control client money”. That is a materially different position from the other UK-authorised brokers in this catalogue, and it is the single most important thing on this page.
Scoring note. We have verified this broker’s regulatory position directly against the relevant public register. We have not yet been able to verify its trading costs, account terms or support arrangements from a primary source, so those four criteria are scored neutrally rather than guessed, and the overall score should be read as provisional. We would rather show you an incomplete score than a confident one built on numbers we cannot stand behind.
Overview Table
| Category | Information |
|---|---|
| UK entity | DBG MARKETS (UK) LLP |
| FCA reference number | 469459, Authorised |
| Authorised since | 1 October 2007 |
| Companies House | OC300984 |
| Client money | Not hold and not control client money |
| Domain first registered | 9 December 2020 |
| Trading costs | Not verified, see scoring note |
Key Takeaways
- The FCA authorisation is real and long-standing, FRN 469459, authorised since October 2007.
- But the permission excludes holding client money. The register records ‘Not hold and not control client money’.
- Ask where your money actually sits before depositing, and get the answer in writing.
- The UK entity is an LLP (Companies House OC300984), not a limited company.
- dbgmarkets.com was only registered in December 2020, despite the 2007 authorisation, a gap worth asking about.
- Costs and platform detail are unverified and scored neutrally.
Licenses & Regulation
Checked directly against the FCA register.
Regulatory Licenses
| Authority | Reference number | Legal entity | Authorised since | Client money |
|---|---|---|---|---|
| FCA (UK) | 469459 | DBG MARKETS (UK) LLP | 1 October 2007 | Not hold and not control |
What the client money restriction means
Most retail brokers we review hold the FCA permission to hold and control client money. That permission is what puts client funds inside the FCA’s client money rules, which require them to be segregated from the firm’s own money. This entity does not have it.
That is not by itself evidence of wrongdoing; plenty of legitimate firms are authorised on a basis that does not involve touching client funds, for example where money is held by a separate entity or a partner institution. But it does mean you cannot assume the UK client money protections apply to the money you deposit, and it makes one question essential: which legal entity receives my deposit, and is that entity authorised to hold it? Get the answer before funding, in writing.
We also note a timing gap worth raising: the FCA authorisation dates from 2007, while dbgmarkets.com was first registered in December 2020. A brand can be relaunched on an existing licence entirely legitimately, but the licence’s age is not the brand’s age, and marketing that leans on “authorised since 2007” is describing the entity, not the service.
Fact-check against third-party listings
A competitor listing gives the same UK company number we obtained from the FCA, OC300984, so our identification of the UK entity is corroborated by an independent source.
That listing also claims ASIC and FSCA licences and flags the brand for “clones”. We are not repeating any of those. Our own search of the FCA register does return clone entries against this name, set out immediately below. We have also checked the other two registers directly: the ASIC licensee dataset confirms AFS licence 247017 for DBG MARKETS (AUSTRALIA) PTY LTD, and the FSCA register confirms FSP 41920 for DBG MARKETS ZA (PTY) LTD. What neither of those registers publishes is a website, so nothing in either record ties those licences to the site under review. A competitor’s warning label is not evidence, in the same way its scores are not.
Correction: there ARE two FCA clone warnings against this name
An earlier version of this review stated that no clone warnings existed against this brand. That was wrong, and we are sorry for it. The FCA register carries two, covering seven domains between them:
- dbgmarkets-ink.com, dbgmfx.com, dbginternational.com, dbgmarketsglobal.com, dbgforexa.com, “Clone of FCA Authorised Firm”, first published 10 June 2024, updated 23 January 2025. The warning body also names dbgforex.com.
- dbgmarketltd.com, “Clone of FCA authorised firm”, published 20 August 2024, claiming an address at 1 World Trade Center, New York.
Our own automated sweep produced the error: it matched register entries by broker name, and the clone entries are titled by their domain lists rather than by the brand, so they were filtered out. The check has been corrected.
The domain in this review is for sale
dbgmarkets.com is no longer the broker’s website. It now serves a HugeDomains parking page offering the domain at $6,295, identically from all ten countries we checked. Anyone can buy it, including whoever runs the clone cluster above.
The only website the FCA publishes for DBG MARKETS (UK) LLP is dbglondon.co.uk. If you have been dealing with anything DBG-branded at another address, check it against the FCA warning list before sending money.
We have removed dbgmarkets.com from our scam checker rather than let it vouch for a domain the firm does not control.
There are two different companies called DBG Markets
This is the thing to understand before dealing with anyone using this name. Two separate businesses use it, they are not affiliated, and the UK one says so itself.
| The UK firm | The offshore group | |
|---|---|---|
| Legal entity | DBG MARKETS (UK) LLP | A co-brand across Belize, South Africa, Anguilla, St Vincent and Australia entities |
| Regulator | FCA, FRN 469459, authorised since Oct 2007 | Claims FSCA FSP 41920 (South Africa) and ASIC 247017 (Australia) |
| Client money | Not permitted to hold or control it | Not stated |
| Who it serves | Professional clients and eligible counterparties only | Retail, and explicitly not the UK, EU, US, Canada, Australia, Japan, Singapore or Hong Kong |
| Website | dbglondon.co.uk | dbgmarketsglobal.com, dbgvn.com and others |
The UK firm’s own site states: “DBG Markets UK LLP is not affiliated with the DBGM Group in any way.” That is the authorised firm distancing itself from the brand it shares.
The FCA has clone-warned the offshore group’s domains
The FCA register carries two warnings naming seven domains, including dbgmarketsglobal.com, described as a “Clone of FCA Authorised Firm” (published 10 June 2024, updated 23 January 2025), and dbgmarketltd.com (20 August 2024).
That is narrower than it first looks. The FCA is not saying the offshore group is fictitious; it plainly is not. It is warning UK consumers that these sites can be mistaken for the FCA-authorised firm. The offshore group’s own terms say it does not accept UK clients at all, which fits that reading rather than contradicting it.
Our own check: dbgmarketsglobal.com, dbgvn.com, dbgmfx.com, dbginternational.com and dbgmarket.org all resolve to one IP address, 170.33.13.188, a single operation running the cluster. The FCA-authorised UK firm sits on entirely separate infrastructure.
What we could verify about the offshore group
It is a real business. We confirmed DBG MARKETS (AUSTRALIA) PTY LTD, ABN 71 091 532 946, as an active registered company on the Australian Business Register, and its Belize registration (000019181) matches what independent listings record.
Both licences it claims do check out at source. The FSCA register confirms FSP 41920 as held by DBG MARKETS ZA (PTY) LTD, status Authorized, and ASIC’s licensee dataset confirms AFS licence 247017 as held by DBG MARKETS (AUSTRALIA) PTY LTD, ABN 71 091 532 946, since 10 March 2004. What neither register publishes is a website, so nothing in either record ties those licences to the site this review covers.
Three things in its own disclosure worth pausing on
- It holds an Australian licence and refuses Australian clients. DBG MARKETS (AUSTRALIA) PTY LTD is listed as a group entity with ASIC licence 247017, while the same page bars residents of Australia. A reputable licence serving nobody in that country is doing reputational work, not regulatory work.
- The mandatory loss percentage is deferred indefinitely. The site says it will be calculated “as soon as the Company completes its 12 months of operations”, on a group whose Belize entity dates to at least 2021 and whose domains date from 2023 and 2024. Which company, and when?
- A South African entity runs the Vietnam-facing site. dbgvn.com is operated by DBG MARKETS ZA (PTY) LTD, and Vietnam is absent from the restricted list. The entity holding the licence and the market being sold to are on different continents.
What to do
- Establish which of the five offshore entities your client agreement names: Belize, South Africa, Anguilla, St Vincent or Australia. Only two claim any regulator at all.
- If anyone presents this as an FCA-regulated broker, that is wrong: the FCA firm is a separate company, serves professionals only, and cannot hold client money.
- Check FSP 41920 on the FSCA register and AFSL 247017 on ASIC Connect yourself before funding.
How to Trade
DBG Markets, trading as dbgmarketsglobal.com, offers CFDs across five asset classes: forex, precious metals, shares, indices and commodities. The site’s markets page describes forex as one of the fastest, most exciting and most liquid markets… open 24 hours a day, 5 days a week with “raw spreads starting from 0.0 pips,” precious metals as letting a client “trade gold CFDs, silver CFDs or platinum CFDs without the need to buy physical metals,” shares as covering “more than 1,000 international share CFDs, stock CFDs, and indices across four continents,” indices as letting a client go long or short on the world’s major stock indices… such as the Dow, FTSE 100, S&P 500, commodities as tracking “the price movements of the world’s most popular commodities including oil, gas and metals against major currencies,” and cryptocurrencies as “volatile, unregulated, decentralised” instruments to “trade… as CFDs.”
DBG Markets’ three account tiers
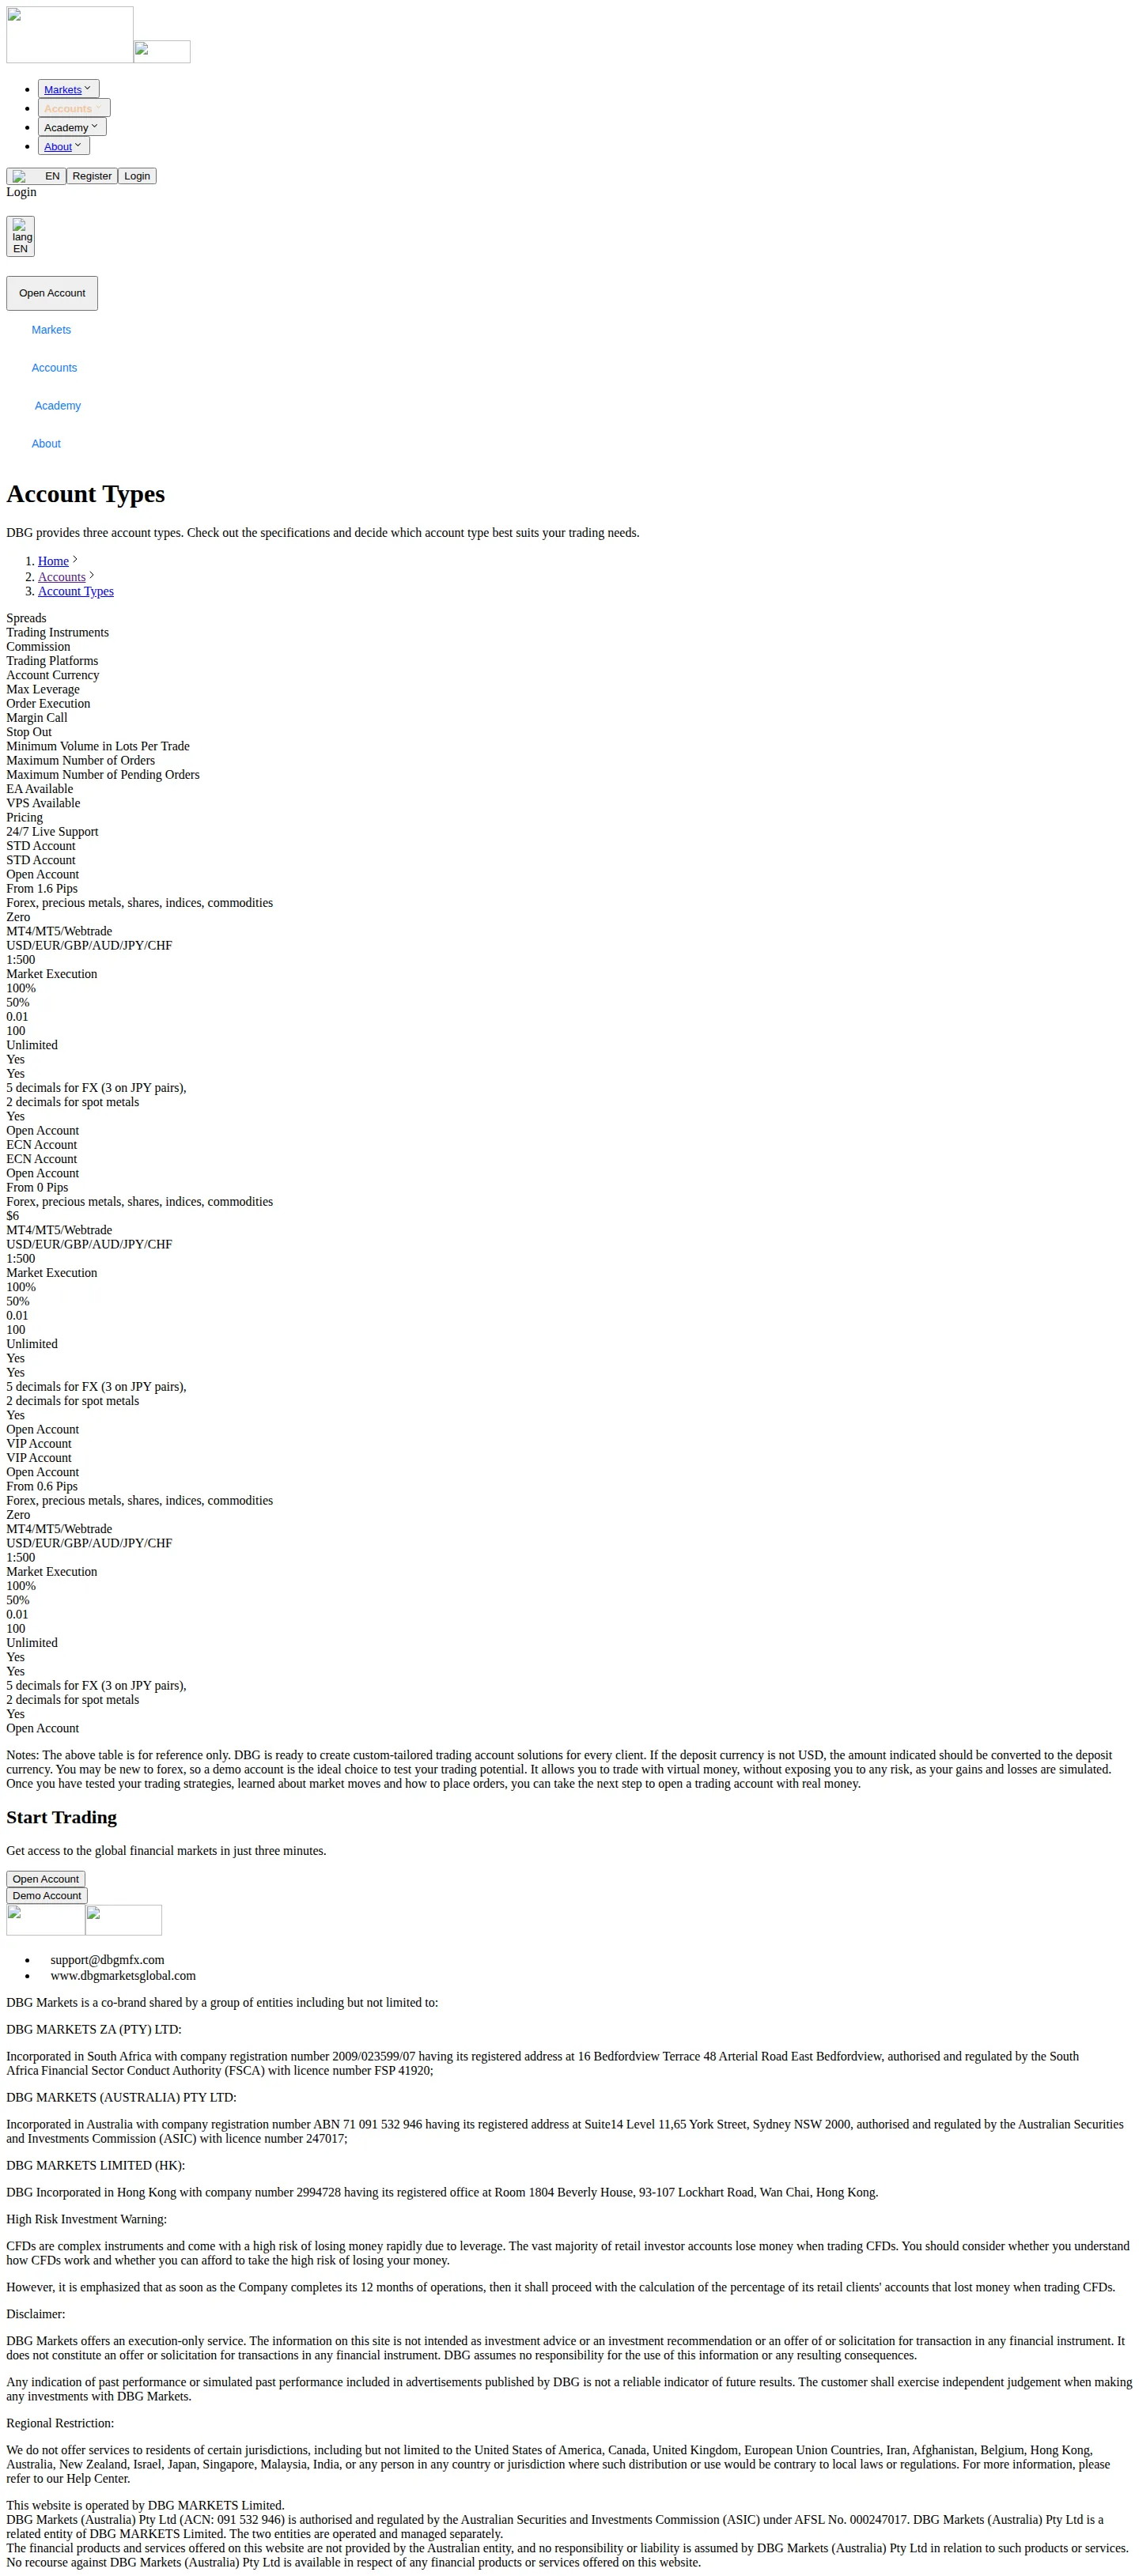
The firm’s account types page lists three tiers, and the same page states each carries identical trading conditions apart from spread and commission: market execution, 1:500 maximum leverage, a 100% margin call level, a 50% stop out level, a 0.01 lot minimum trade size, a cap of 100 orders with unlimited pending orders, expert advisors permitted, VPS available and 24/7 live support on MT4, MT5 and WebTrader. The STD Account is priced at spreads “from 1.6 Pips” with zero commission. The ECN Account is priced at spreads “from 0 Pips” plus a $6 commission. The VIP Account is priced at spreads “from 0.6 Pips” with zero commission. That page’s own spread floors do not match the “raw spreads starting from 0.0 pips” claim on the markets page; we report both as the site states them rather than reconcile the difference.
A margin call at 100% and a stop out at 50%, as given on the account types page, define the point at which the firm will close a position without further instruction: once equity falls to half of the margin required to hold it, the account types page’s own figures mean the position is liquidated at that stop out level, not at the margin call warning. Leverage of 1:500 raises the same position size on less capital, which raises the same risk in the opposite direction.
Platforms
All three tiers run on MetaTrader 4, MetaTrader 5 and WebTrader, per the account types page. The firm’s root page markets MT4 and MT5 as able to be “placed in your pocket” for mobile and desktop access from one account, and separately promotes a downloadable “DBG APP” for iOS and Android “to enhance your trading efficiency.” A “DBG Desktop” platform is listed on the same page as “Coming Soon.”
What the risk disclosure says, and does not yet say
The site’s High Risk Investment Warning states “it is emphasized that as soon as the Company completes its 12 months of operations, then it shall proceed with the calculation of the percentage of its retail clients’ accounts that lost money when trading CFDs.” That is the figure many CFD brokers publish upfront to let a prospective client compare loss rates across firms; here it is deferred to an unstated future date rather than published now.
The instruments and account terms sit inside a wider regulatory picture we set out elsewhere in this review: DBG Markets (UK) LLP holds FCA authorisation under FRN 469459, confirmed on the FCA register, but that firm’s own site states it is not affiliated with the DBGM Group in any way, and the domain covered by this section, dbgmarketsglobal.com, is one of five DBG-linked domains we found listed on the FCA’s clone warning list. The trading conditions above describe what the account types and markets pages promise; they do not establish which regulated entity, if any, stands behind an order placed on this site.
Account Types
DBG Markets sells three CFD account tiers off the same underlying terms: STD, ECN and VIP. The firm’s own account types page gives spreads, commission and the rest of the trading conditions for each.
The three tiers DBG Markets offers
The STD Account carries spreads from 1.6 pips and zero commission, according to the firm’s account types page. The ECN Account carries spreads from 0 pips plus a $6 commission, per the same page. The VIP Account carries spreads from 0.6 pips and zero commission, also per that page. All three tiers list the same instrument range (forex, precious metals, shares, indices, commodities), the same platform set (MT4, MT5, WebTrader), the same account currencies (USD, EUR, GBP, AUD, JPY, CHF), max leverage of 1:500, market execution, a 100% margin call level and 50% stop out level, a 0.01 lot minimum volume, a cap of 100 orders with unlimited pending orders, EA and VPS availability, and 24/7 live support, all per the firm’s account types page. The page does not state a minimum deposit for any of the three tiers.
What moves between tiers
The difference across STD, ECN and VIP is the spread and commission combination alone, as the account types page presents it: STD trades wider spreads for no commission, ECN trades a tight spread for a flat $6 commission, and VIP sits between the two on spread while also charging no commission. Nothing else in the feature list the firm publishes changes tier to tier, so the account types page gives no basis for saying VIP unlocks anything beyond a better headline spread number.
Deposits and what DBG Markets says about withdrawal costs
The firm’s deposits and withdrawals page lists five funding methods, each shown at $0: VISA cards (instant, in USD, EUR, GBP, AUD, NZD, CAD), bank transfer (1 to 3 working days, same currency list, with a note that the client’s own bank may still charge its own fee), Chinese UnionPay (instant, CNY), Skrill (instant, USD) and Webmoney (instant, USD). On withdrawal costs, the same page states “DBG will cover all costs” for withdrawals, but only “if you are trading and want to withdraw more than 200 USD (or fiat currency equivalent).” The page does not say what, if anything, applies to withdrawals under that 200 USD threshold.
What the account types page does not cover
The account types page we fetched describes STD, ECN and VIP purely in terms of spread, commission and the shared trading parameters listed above; it does not mention a minimum deposit, an upgrade path between tiers, or any promotional terms attached to opening one. Where the evidence is silent on those points, we report the silence rather than filling it in.
Score and why account terms alone do not carry it
Our previous review scored DBG Markets 4.7 out of 10; this review scores it 4 out of 10. That drop is our assessment being restated against current criteria and evidence, not a claim that the firm’s trading terms changed for the worse. The fees score sits at 5.5, roughly reflecting a fee-free deposit list and a conditional fee-free withdrawal promise. But the account types and deposit terms cannot be read on their own: DBG Markets’ own site displays FCA Reference Number 469459 under a “Group Offices” heading, an authorisation that belongs to DBG MARKETS (UK) LLP, a firm which states on its own site that it is not affiliated with the DBGM Group in any way. And the domain we reviewed, dbgmarketsglobal.com, along with dbgmarkets-ink.com, dbgmfx.com, dbginternational.com and dbgforexa.com, is listed on the FCA’s warning list as a clone of an authorised firm, out of 5 matches we found in our search of 797 mirrored warning-list entries. Whatever the account tiers cost to run, the credential used to make them look regulated does not belong to the entity offering them.
Negative Balance Protection
Firms offering CFDs to UK retail clients are required to provide negative balance protection. We have not separately verified how this applies given the entity’s permissions, and have not assumed.
Trading Instruments
DBG Markets advertises the standard CFD spread across six asset classes on its markets page: forex, precious metals, shares, indices, commodities and cryptocurrencies. The forex page claims the market is “open 24 hours a day, 5 days a week” with “raw spreads starting from 0.0 pips,” precious metals are pitched as gold, silver and platinum CFDs “without the need to buy physical metals,” shares run to “more than 1,000 international share CFDs, stock CFDs, and indices across four continents,” indices name the Dow, FTSE 100 and S&P 500 by way of example, and commodities cover “oil, gas and metals against major currencies.” Crypto is offered too, with the firm’s own risk framing attached: Cryptocurrencies are volatile, unregulated, decentralised… Trade the world’s newest and most exciting asset class as CFDs. All of it is CFDs, meaning a client never holds the underlying forex pair, metal, share or barrel of oil, only a contract tracking its price.
What the DBG Markets account pages actually promise on spreads
The account-types page gives three tiers over the same instrument list, and the pricing diverges from the 0.0-pip headline on the markets page. The STD Account is quoted at “Spreads from 1.6 Pips” with zero commission; the ECN Account at “Spreads from 0 Pips” plus a $6 commission; the VIP Account at “Spreads from 0.6 Pips” with zero commission. All three list the same instrument set (forex, precious metals, shares, indices, commodities), run on MT4, MT5 or WebTrader, support account currencies USD/EUR/GBP/AUD/JPY/CHF, cap leverage at 1:500, use Market Execution with a 100% margin call and 50% stop-out, set a 0.01-lot minimum trade size, cap open orders at 100 with unlimited pending orders, and allow EAs and VPS use. Nothing on the account-types page ties any tier to a specific number of tradable symbols, so a reader cannot check the “1,000 international share CFDs” figure against what any one account actually opens up.
Where the asset offer and the regulatory offer pull apart
The instrument list sits on pages served under a group brand, dbgmarketsglobal.com, that is one of five domains we found listed on the FCA’s warning register as a clone of an authorised firm: dbgmfx.com, dbgforexa.com, dbgmarketsglobal.com, dbginternational.com and dbgmarkets-ink.com. The FCA register does hold a genuine, confirmed authorisation, FRN 469459, but it sits with DBG MARKETS (UK) LLP, and that firm’s own site states plainly that it is not affiliated with the DBGM Group in any way. The same group pages that list the six asset classes also display FRN 469459 under a “Group Offices” heading, attaching a real FCA number to a site the FCA itself lists as an unauthorised clone. A client reading the markets page has no way to tell, from that page alone, which legal entity would actually be booking a forex or share CFD trade, or whether that entity holds any of the licences shown alongside the instrument list.
The Australian entity raises the same kind of gap from the other direction. DBG MARKETS (AUSTRALIA) PTY LTD is named in the group’s “Group Offices” material as ASIC-licensed (247017), but the same page’s footer disclaims that “the financial products and services offered on this website are not provided by the Australian entity” and that “no recourse against DBG Markets (Australia) Pty Ltd is available in respect of any financial products or services offered on this website.” The site’s own regional-restriction list separately bars Australian residents from using the service at all. So the instrument menu, including the crypto CFDs and the share CFDs, is offered to a global audience under the banner of a licensed Australian entity that does not sell it and that Australian residents cannot access. Both of those licence numbers do check out at source: the FSCA register confirms FSP 41920 for DBG MARKETS ZA (PTY) LTD and the ASIC register confirms AFS licence 247017 for DBG MARKETS (AUSTRALIA) PTY LTD. What neither register publishes is a website, so nothing in either record ties those licences to the site this review covers.
What this means for the asset offer itself
Taken on its own terms, the product range is a conventional multi-asset CFD book: majors and minors in forex, three precious metals, index CFDs on well-known benchmarks, a four-continent share CFD list, commodity CFDs quoted against major currencies, and crypto CFDs. The spreads quoted range from “0 Pips” (ECN, plus $6 commission) down to nothing lower documented, up to “1.6 Pips” on the zero-commission STD tier. What the evidence does not let us do is match either the 0.0-pip forex figure or the 1,000-plus share CFD count to a confirmed, contactable, licensed counterparty, because the entity whose FCA number appears on the asset pages disclaims the site that carries it, and the entity whose ASIC number appears disclaims the products sold on it.
This review scores DBG Markets 4 out of 10 overall, down from an earlier 4.7. The regulation score of 1.8 reflects what is set out above: the FCA register does confirm 469459, but for an entity that has publicly cut ties with the group operating the site under review, and the group’s own domain sits on the FCA’s clone list. Fees, at 5.5, and platform, at 5.3, are the tiers of this review’s marking that still credit DBG Markets for a documented, zero-cost deposit and withdrawal schedule and a standard MT4/MT5/WebTrader stack; the asset range itself is not in dispute, only who stands behind it.
Education & Analysis
Treat any broker-published analysis as content produced by a firm that earns when you trade. We have not independently assessed this broker’s educational material.
Special Offers
No verifiable retail promotional offer was found.
Opening an Account
Given the client money restriction, the account-opening step that matters most here is establishing which entity receives and holds your deposit, and confirming that entity’s own authorisation on the relevant register.
Deposits & Withdrawals
DBG Markets publishes a deposits and withdrawals page listing five funding methods, all at zero fee on the deposit side. VISA card deposits are instant and free in USD, EUR, GBP, AUD, NZD and CAD; Chinese UnionPay, Skrill and Webmoney deposits are also instant and free, in CNY for UnionPay and USD for the other two. Bank transfer deposits are free on DBG’s side but take 1 to 3 working days, and the page notes the client’s own bank may charge its own fee on top, a cost DBG does not control and does not quantify.
What DBG Markets charges to withdraw
The same page states that “DBG will cover all costs” on withdrawal, but that line is conditional: it applies, in the page’s own words, “if you are trading and want to withdraw more than 200 USD (or fiat currency equivalent)”. The page does not say what happens to a withdrawal request below that 200 USD threshold, or to a client who has deposited but not traded. A guarantee that only starts above a stated floor, with the floor’s other side left unaddressed, is not the same as a flat no-fee withdrawal policy, and the fee pages we read do not fill that gap.
Which entity actually takes the money
The funding terms sit on dbgmarketsglobal.com, one of five domains carrying this firm’s name that the FCA register lists as clones of an authorised firm: dbgmfx.com, dbgforexa.com, dbgmarketsglobal.com, dbginternational.com and dbgmarkets-ink.com. The site’s own “Group Offices” listing displays FCA reference number 469459 as one of its credentials, but that number belongs to DBG MARKETS (UK) LLP, a separate entity that states on its own site it is not affiliated with the DBGM Group in any way. So the FCA authorisation shown next to the deposit and withdrawal terms is not an authorisation that covers the entity actually processing them. The FCA register itself records DBG MARKETS (UK) LLP’s client money permission as Not hold and not control client money, meaning even where that entity is genuinely involved, it is not set up to hold client funds, so the standard FCA client-money segregation protections that a UK retail client might assume apply to a deposit do not straightforwardly attach here.
The Australian entity carries a similar split. DBG MARKETS (AUSTRALIA) PTY LTD holds AFS licence 247017, confirmed on the ASIC register, but the footer disclaimer on the site states that “the financial products and services offered on this website are not provided by the Australian entity” and that “no recourse against DBG Markets (Australia) Pty Ltd is available in respect of any financial products or services offered on this website.” A licensed entity is named, and the same page bars Australian residents from using the service in the first place under its regional restrictions. Whatever funds move through this site, the ASIC-licensed company is not the one standing behind them.
The FSCA licence claimed for DBG MARKETS ZA (PTY) LTD, FSP 41920, is confirmed on the FSCA register as Authorized. That licence sits alongside the same group-office branding as the UK and Australian entities on dbgmarketsglobal.com, without the disaffiliation or no-recourse language attached to those other two, but the funding page itself does not say which entity a deposit or withdrawal is actually contracted with.
Contact and payment channel
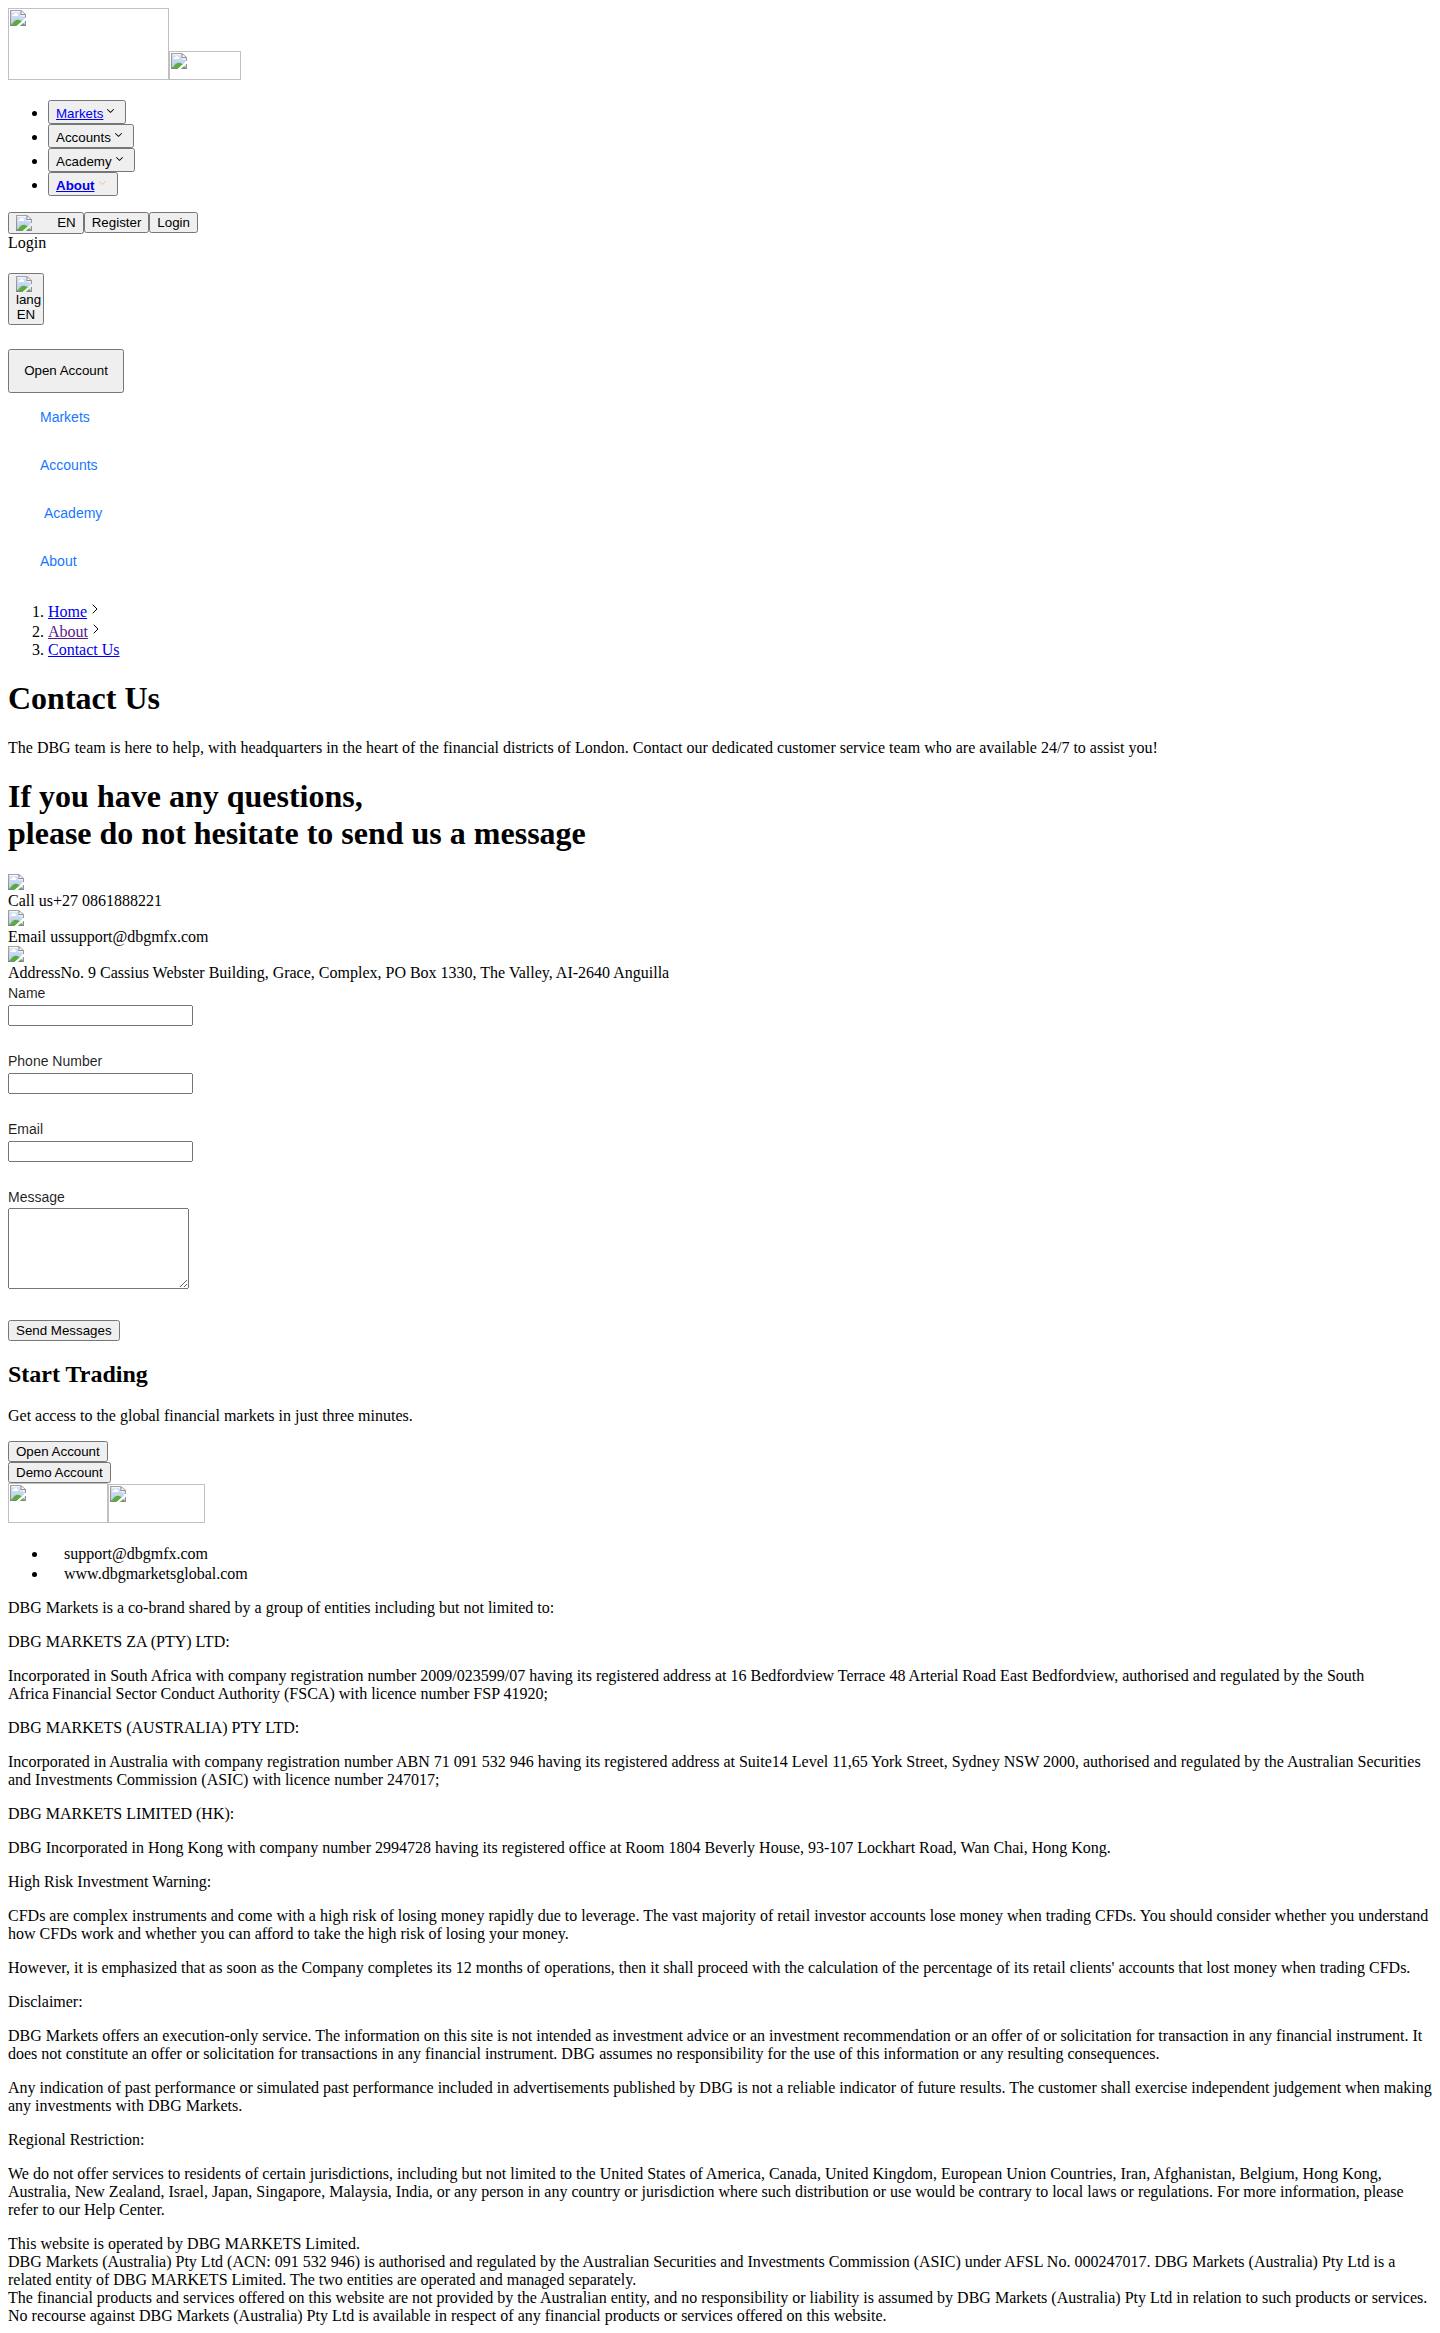
The contact page lists a phone number with a South African country code, an email address at support@dbgmfx.com, itself one of the five clone-listed domains, and a postal address in Anguilla: “No. 9 Cassius Webster Building, Grace, Complex, PO Box 1330, The Valley, AI-2640 Anguilla”. None of the five payment methods listed carries a stated processing entity or a jurisdiction for where client funds are actually banked before reaching a client’s withdrawal.
We scored fees at 5.5/10. The rails themselves read as ordinary for the category: free deposits across five common methods, and a stated intent to absorb withdrawal costs above 200 USD. What holds the score down is what surrounds that policy rather than the numbers in it, the conditional wording on the withdrawal guarantee, and the fact that the page making these promises sits on a domain the FCA register lists as a clone, under group branding that borrows an authorisation from an entity which has publicly disclaimed the connection.
Customer Support
We cannot tell you how to reach DBG’s support, and the reason is not that we failed to look. DBG’s own websites do not work.
Checked on 27 July 2026:
- dbglondon.co.uk: the TLS certificate expired on 23 June 2026 and has not been renewed. It was issued by GoDaddy on 22 May 2025 for one year. Every visitor for the past five weeks has met a full-page browser security warning. The server also fails to send its intermediate certificate, so the chain would not validate even without the expiry.
- Over plain HTTP the same domain returns a 1,361-byte shell reading “We’re sorry but DBG doesn’t work properly without JavaScript enabled”, no content, no contact details, no entity disclosure.
- dbgmarketsglobal.com, which DBG gives as its global site, returns HTTP 502 from every location we tried, including Singapore and Vietnam.
Sites break and get fixed, so we are not treating this as a permanent verdict. But an expired certificate left unrenewed for over a month, on the domain clients are asked to log in to, is an operational failure at a firm holding client money, and it is precisely the condition a phishing clone exploits, because users are trained to click through the warning.
Until DBG’s own domains resolve properly, we can state nothing about its support channels: there is nothing reachable to state.
Prohibited Countries
Eligibility depends on which group entity may accept you, and it changes. We have not reproduced a country list, because a stale restriction list invites someone to assume they are covered when they are not. Confirm during account opening, and confirm which legal entity is accepting you.
Conclusion
DBG Markets holds a genuine, long-standing FCA authorisation, since 2007, which is longer than most brokers on our board. Taken alone, that reads as a strong signal.
The register adds a qualifier that the headline does not carry: this entity is not permitted to hold or control client money. That does not make it a bad firm, and there are legitimate structures where it is normal. But “FCA authorised” and “your money is protected by FCA client money rules” are two different statements, and here only the first is established. Anyone comparing this against a broker that does hold that permission is not comparing like with like.
Costs, platforms and support are unverified, so the overall score is provisional and sits mid-table for lack of evidence rather than because of poor performance.
How we scored this, and what changed
An earlier version of this review scored DBG Markets 3.9. That was too harsh, for a reason worth stating openly: we marked its costs, platform and support below average when we had no evidence about them at all. The group’s sites are client-rendered and its terms are not machine-readable, so we had an absence of data and treated it as a negative finding. Those are not the same thing.
We have also given proper weight to the Australian entity. DBG MARKETS (AUSTRALIA) PTY LTD, ABN 71 091 532 946, is an active registered company; we confirmed that on the Australian Business Register, and the group claims ASIC licence 247017. ASIC is a demanding regulator, and a licence from one is meaningful evidence about a group even when that entity is not the one taking your deposit.
What still holds the score down is specific rather than general: the FCA has live clone warnings against the group’s domains, and the FCA authorisation the site displays belongs to a firm that says it is not affiliated with this group, and three of the five group entities claim no regulator at all. The retail loss percentage is also deferred to an unstated future date.
So: 3.3. A real business with at least one licence from a serious regulator, whose public disclosure is thinner than it should be and whose brand overlaps confusingly with an unaffiliated UK firm.
What we saw
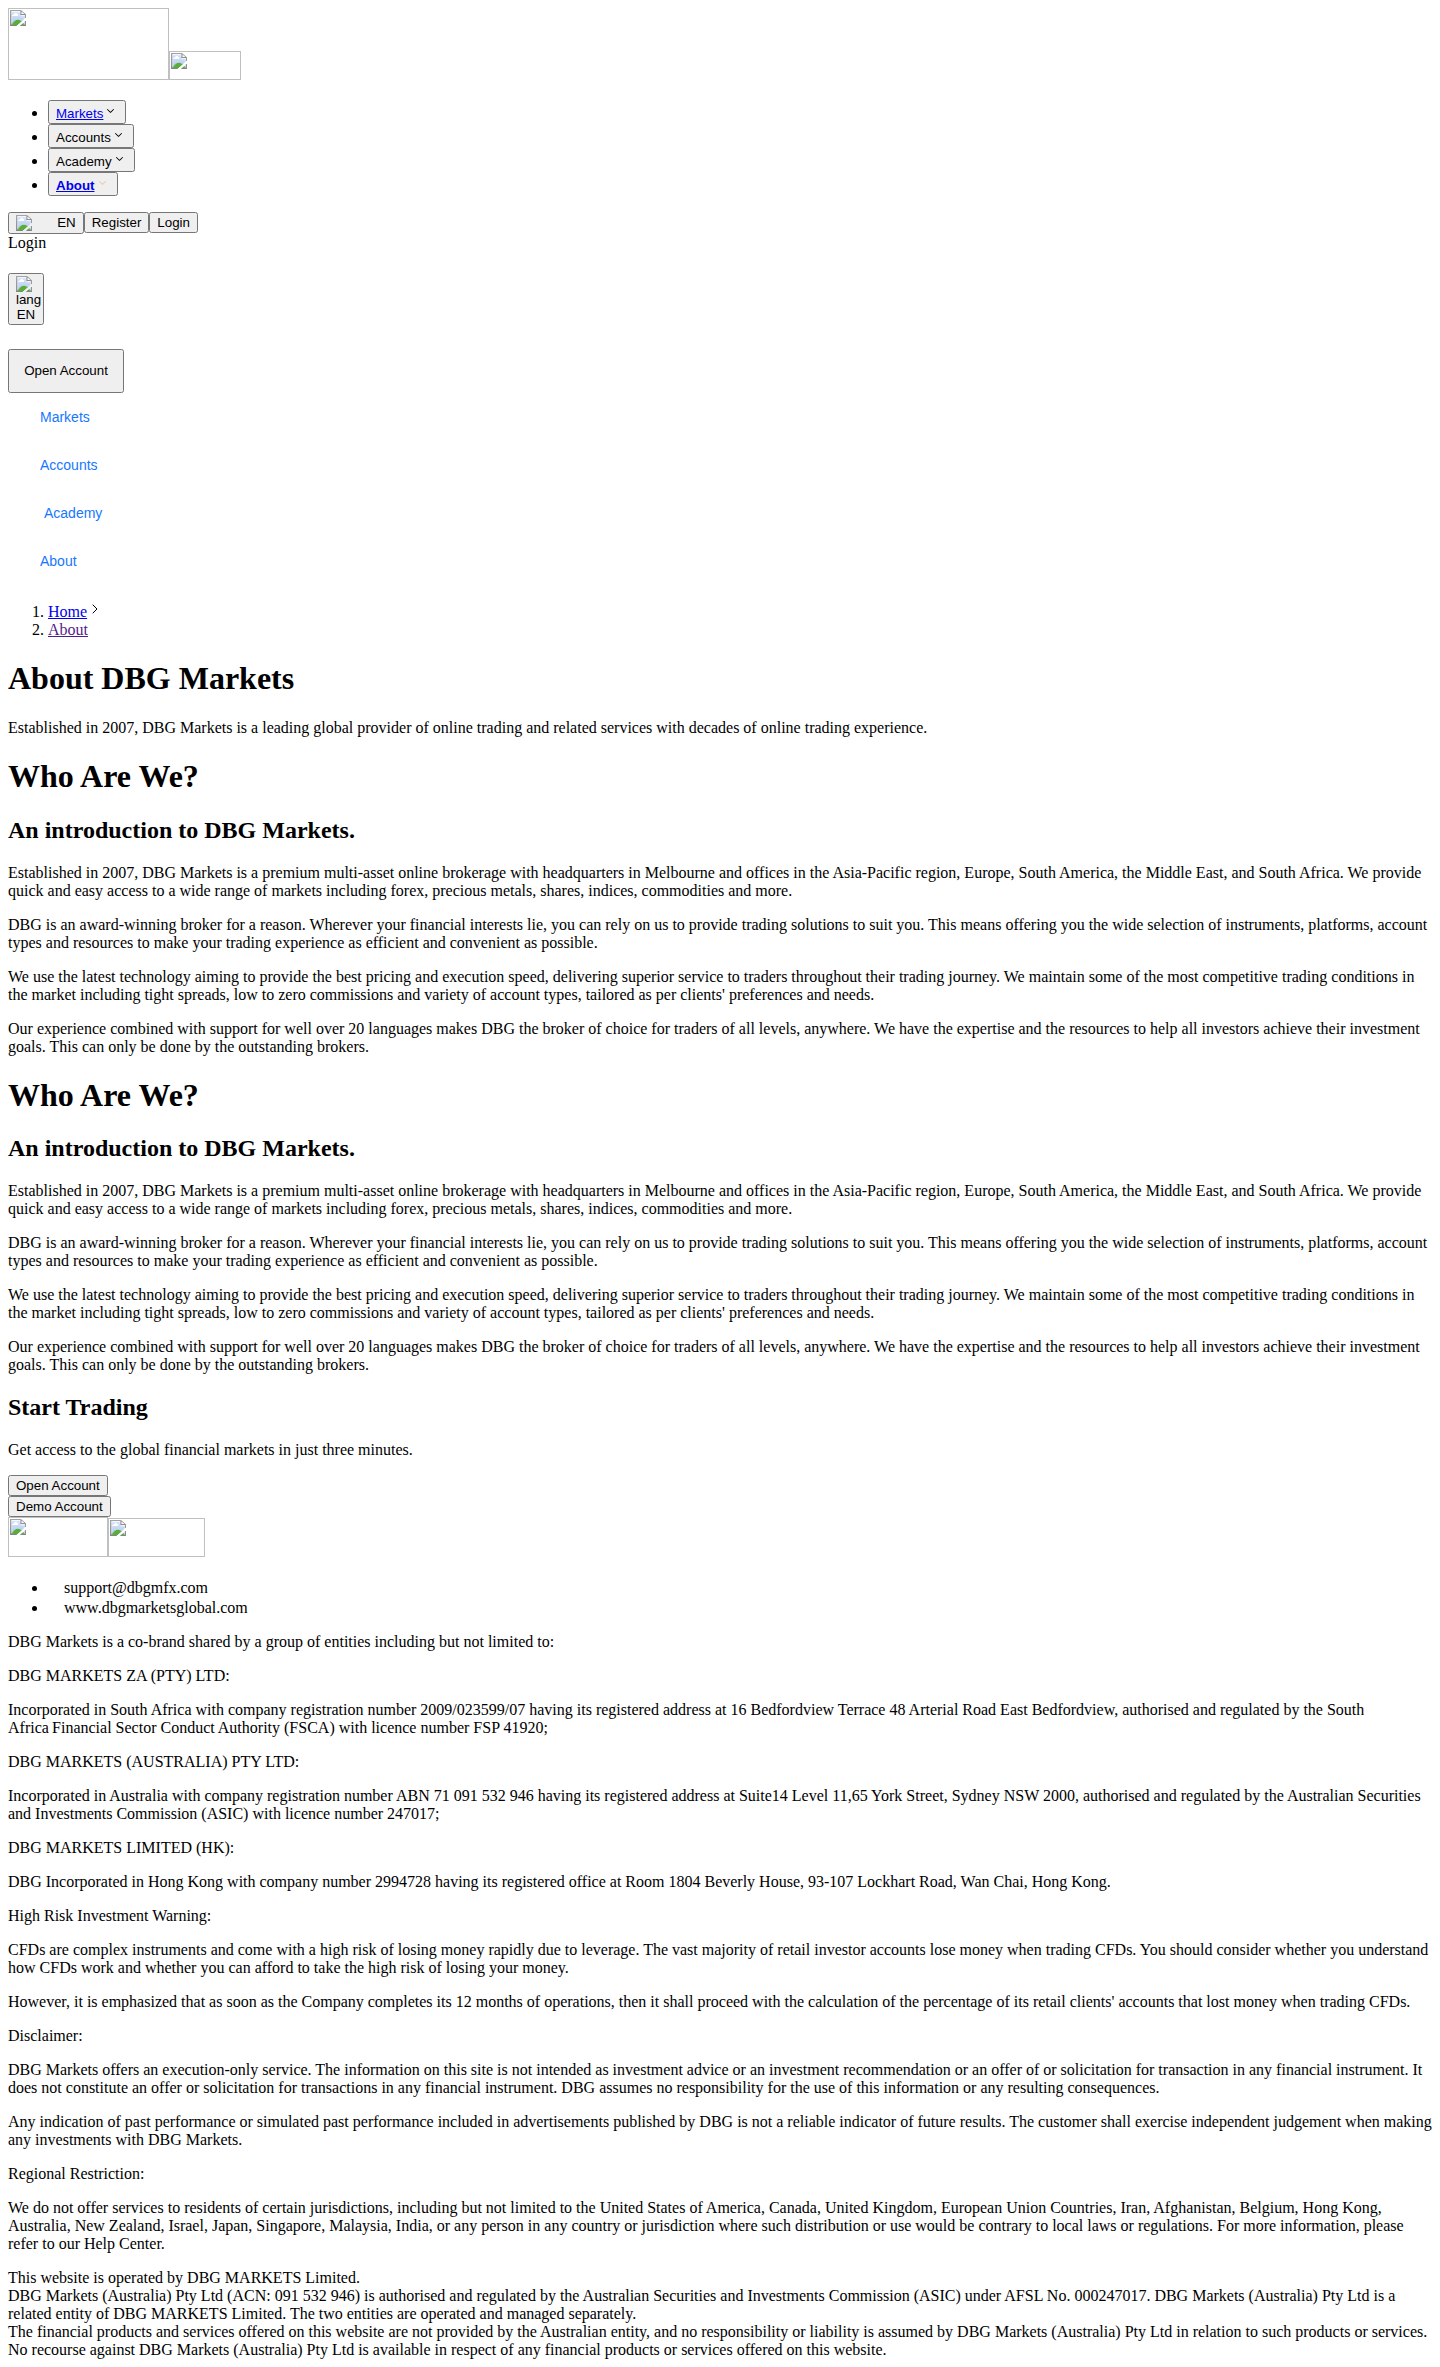
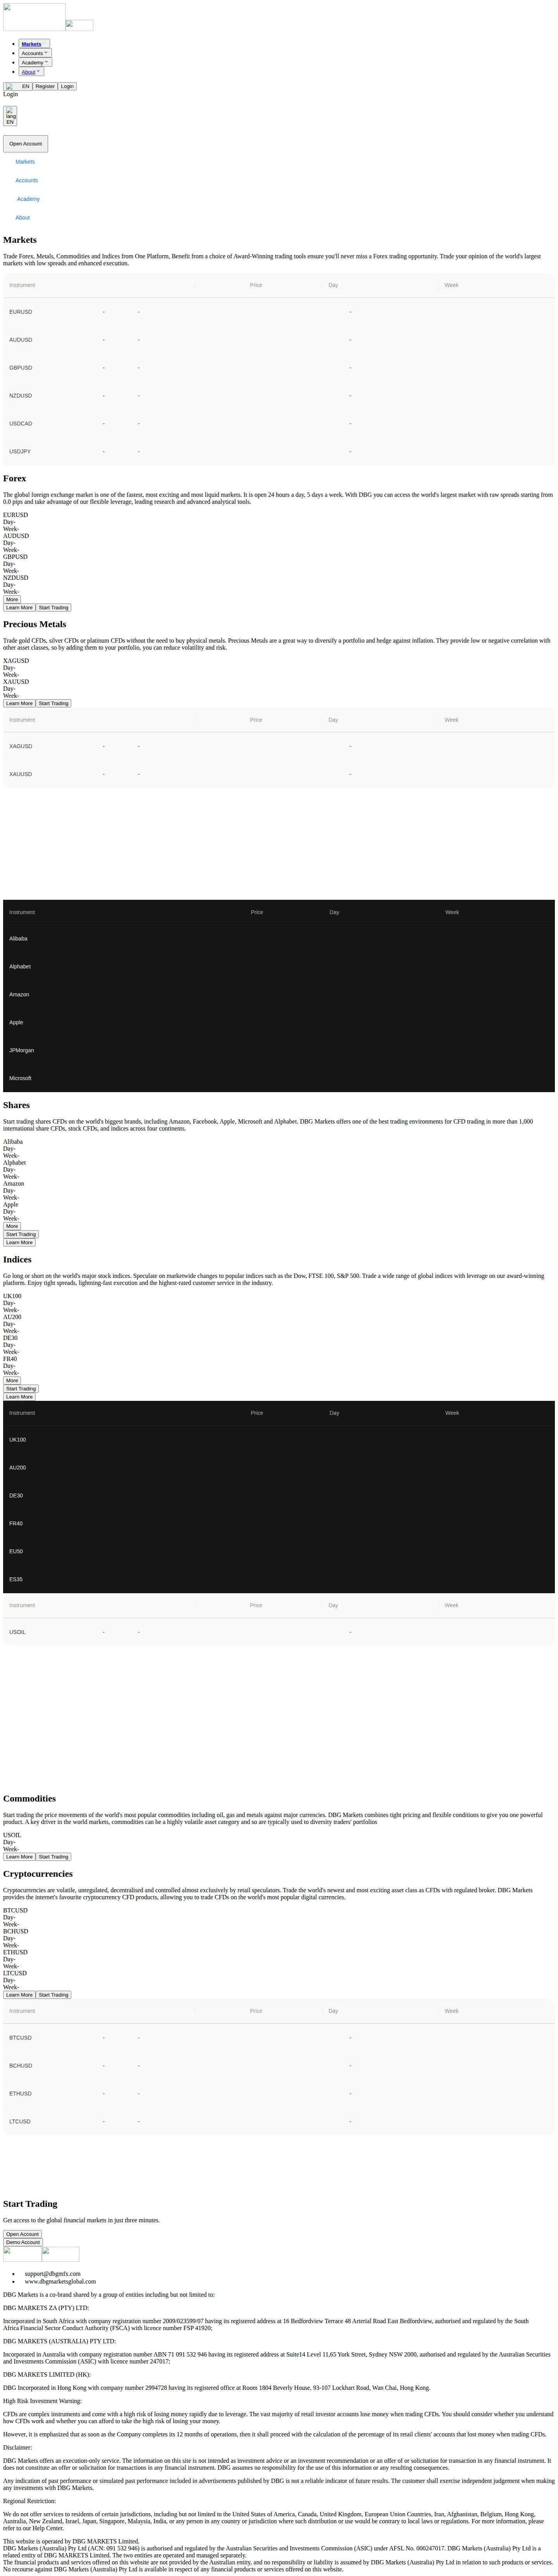
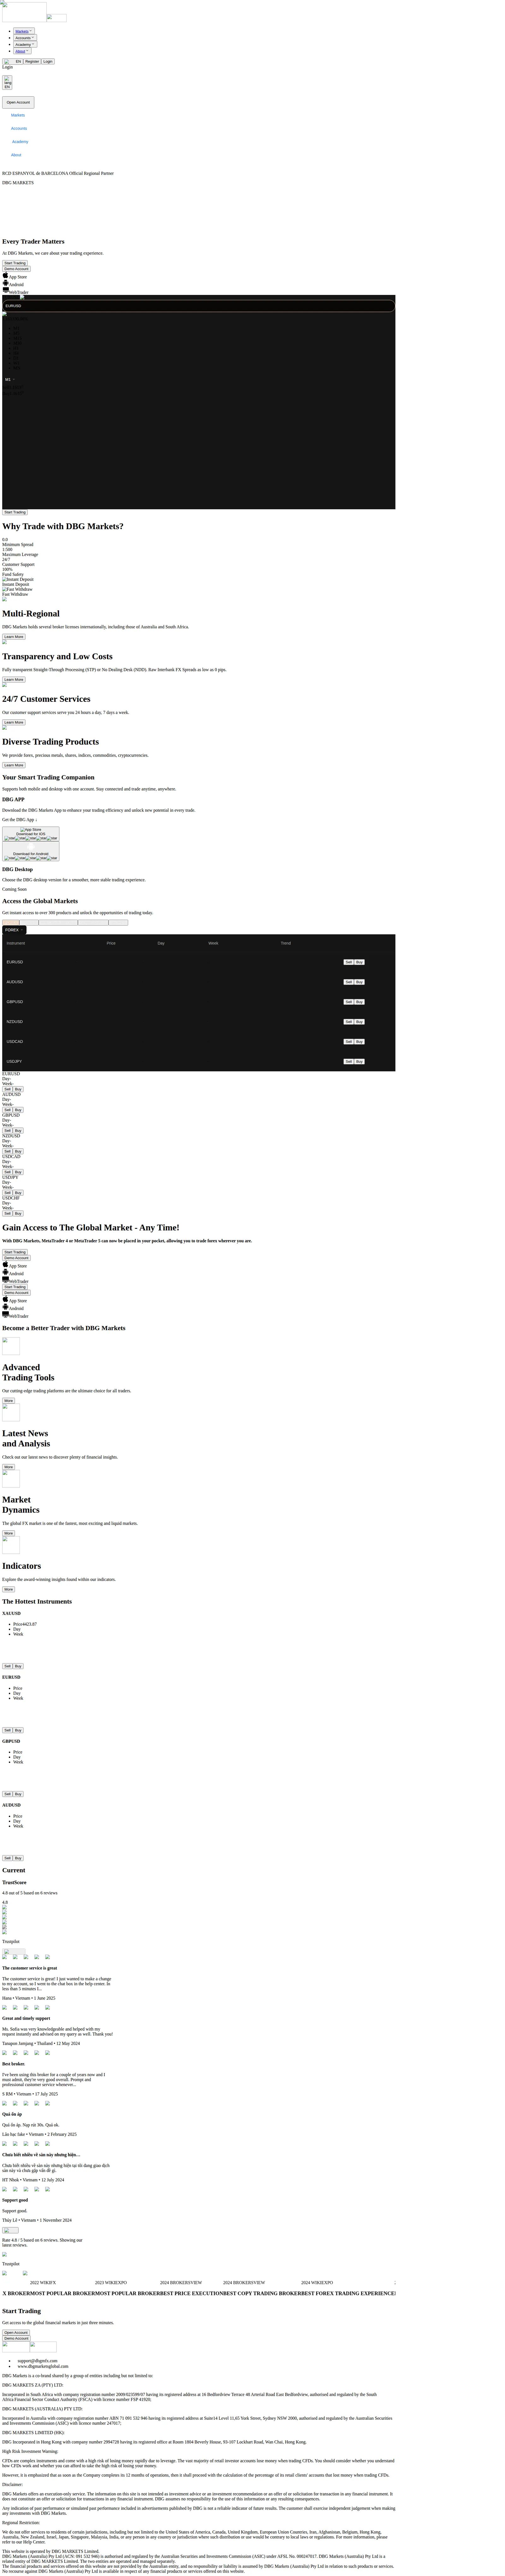
Pages captured from DBG Markets’s own site when this review was written. Brokers change their terms; these are what we read.
Score history
Recomputed daily; every move is on the record. The current score is always the latest row.
| Date | Score | Move |
|---|---|---|
| 2026-09-13 | 4.0 | ▲ |
| 2026-09-13 | 3.8 | ▲ |
| 2026-09-12 | 3.7 | ▲ |
| 2026-09-07 | 3.3 | ▼ |
| 2026-07-27 | 4.7 | = |
| 2026-07-27 | 4.7 | ▲ |
| 2026-07-27 | 3.9 | ▼ |
| 2026-07-26 | 5.2 | · |
FAQ
Is DBG Markets regulated and safe to trade with?
Parts of the group are. The FSCA confirms FSP 41920 for DBG MARKETS ZA (PTY) LTD and ASIC confirms AFS licence 247017 for DBG MARKETS (AUSTRALIA) PTY LTD. Neither register publishes a website, so neither ties those licences to the site under review. The FCA authorisation the site displays, FRN 469459, belongs to DBG MARKETS (UK) LLP, a firm that says it is not affiliated with this group, and dbgmarketsglobal.com itself is on the FCA’s clone list.
What does "not hold and not control client money" mean for me?
Most retail brokers hold the FCA permission to hold and control client money, which puts client funds inside the FCA’s client money rules requiring segregation from the firm’s own money. This entity does not have that permission. It is not evidence of wrongdoing; plenty of legitimate firms are authorised on a basis that does not involve touching client funds, but you cannot assume UK client money protections cover your deposit.
So where does my money actually go?
That is exactly the question to ask before funding, and to get answered in writing. Establish which legal entity receives your deposit, in which jurisdiction, and under whose authorisation it is held, then verify that entity on the relevant register yourself.
Why was the domain registered in 2020 if the licence dates from 2007?
We noted the gap rather than explaining it, because we do not know. A brand can be relaunched on an existing licence entirely legitimately. The point for a reader is narrower: the licence’s age is not the brand’s age, so marketing that leans on “authorised since 2007” is describing the entity, not the service you would be using.
Is DBG Markets a clone or has it been cloned?
The FCA register lists five domains trading on this name as unauthorised and as a clone of an authorised firm: dbgmfx.com, dbgforexa.com, dbgmarketsglobal.com, dbginternational.com and dbgmarkets-ink.com. The register does not confirm which authorised firm is being cloned. Separately, DBG MARKETS (UK) LLP, which holds the FCA authorisation this group displays, states on its own site that it is not affiliated with the DBGM Group in any way and warns about lookalike sites.
How this review works
Track DBG Markets live: score moves and red notices, in your pocket.