CFD · CHECKED 10 OCT 2026
Eightcap review.
CFD broker operating multiple regulated entities across the UK, Australia and Cyprus
OK-ISH
OUT OF 10
AD DISCLOSURE: IF YOU OPEN AN ACCOUNT THROUGH THIS LINK WE MAY EARN A COMMISSION. IT NEVER MOVES THE SCORE. HOW THIS WORKS
Eightcap is a CFD broker running through several linked entities, with tier-1 licences confirmed from the FCA (FRN 921296), ASIC (AFSL 391441) and CySEC (246/14), plus offshore registrations in Seychelles and the Bahamas. Fees are low and platform choice is wide, but support scored weakest of all criteria, and which entity onboards a client shapes what protection and escalation they actually get.
Each criterion is scored 1 to 10 from primary sources. The overall score is their unweighted mean. How scoring works.
| Founded | 2015 |
|---|---|
| Headquarters | AU |
| Minimum deposit | $100 |
| Minimum spread | 0.02 |
| Withdrawal fee | 0 |
| Account opening | 1-3 |
| Platforms | TradingView, MetaTrader 4, MetaTrader 5, TradeLocker |
- Regulated by the FCA (UK), licence FRN 921296, confirmed on the register
- Regulated by ASIC (Australia), licence AFSL 391441, confirmed on the register
- Regulated by CySEC (Cyprus), licence 246/14, confirmed on the register
- Also holds confirmed licences with the Seychelles FSA and Bahamas SCB
- FCA cover includes compensation up to 85,000 GBP and an ombudsman scheme
- Negative balance protection and a 30:1 leverage cap on major FX under FCA rules
- Support scored lowest of all criteria at 4.3/10
- Which entity handles support and escalation depends on who onboarded you
- Mauritius FSC licence is claimed but not verified due to a directory gap
- SVG entity CLMarkets Limited (IBC 24750) is disclosed with no regulator named
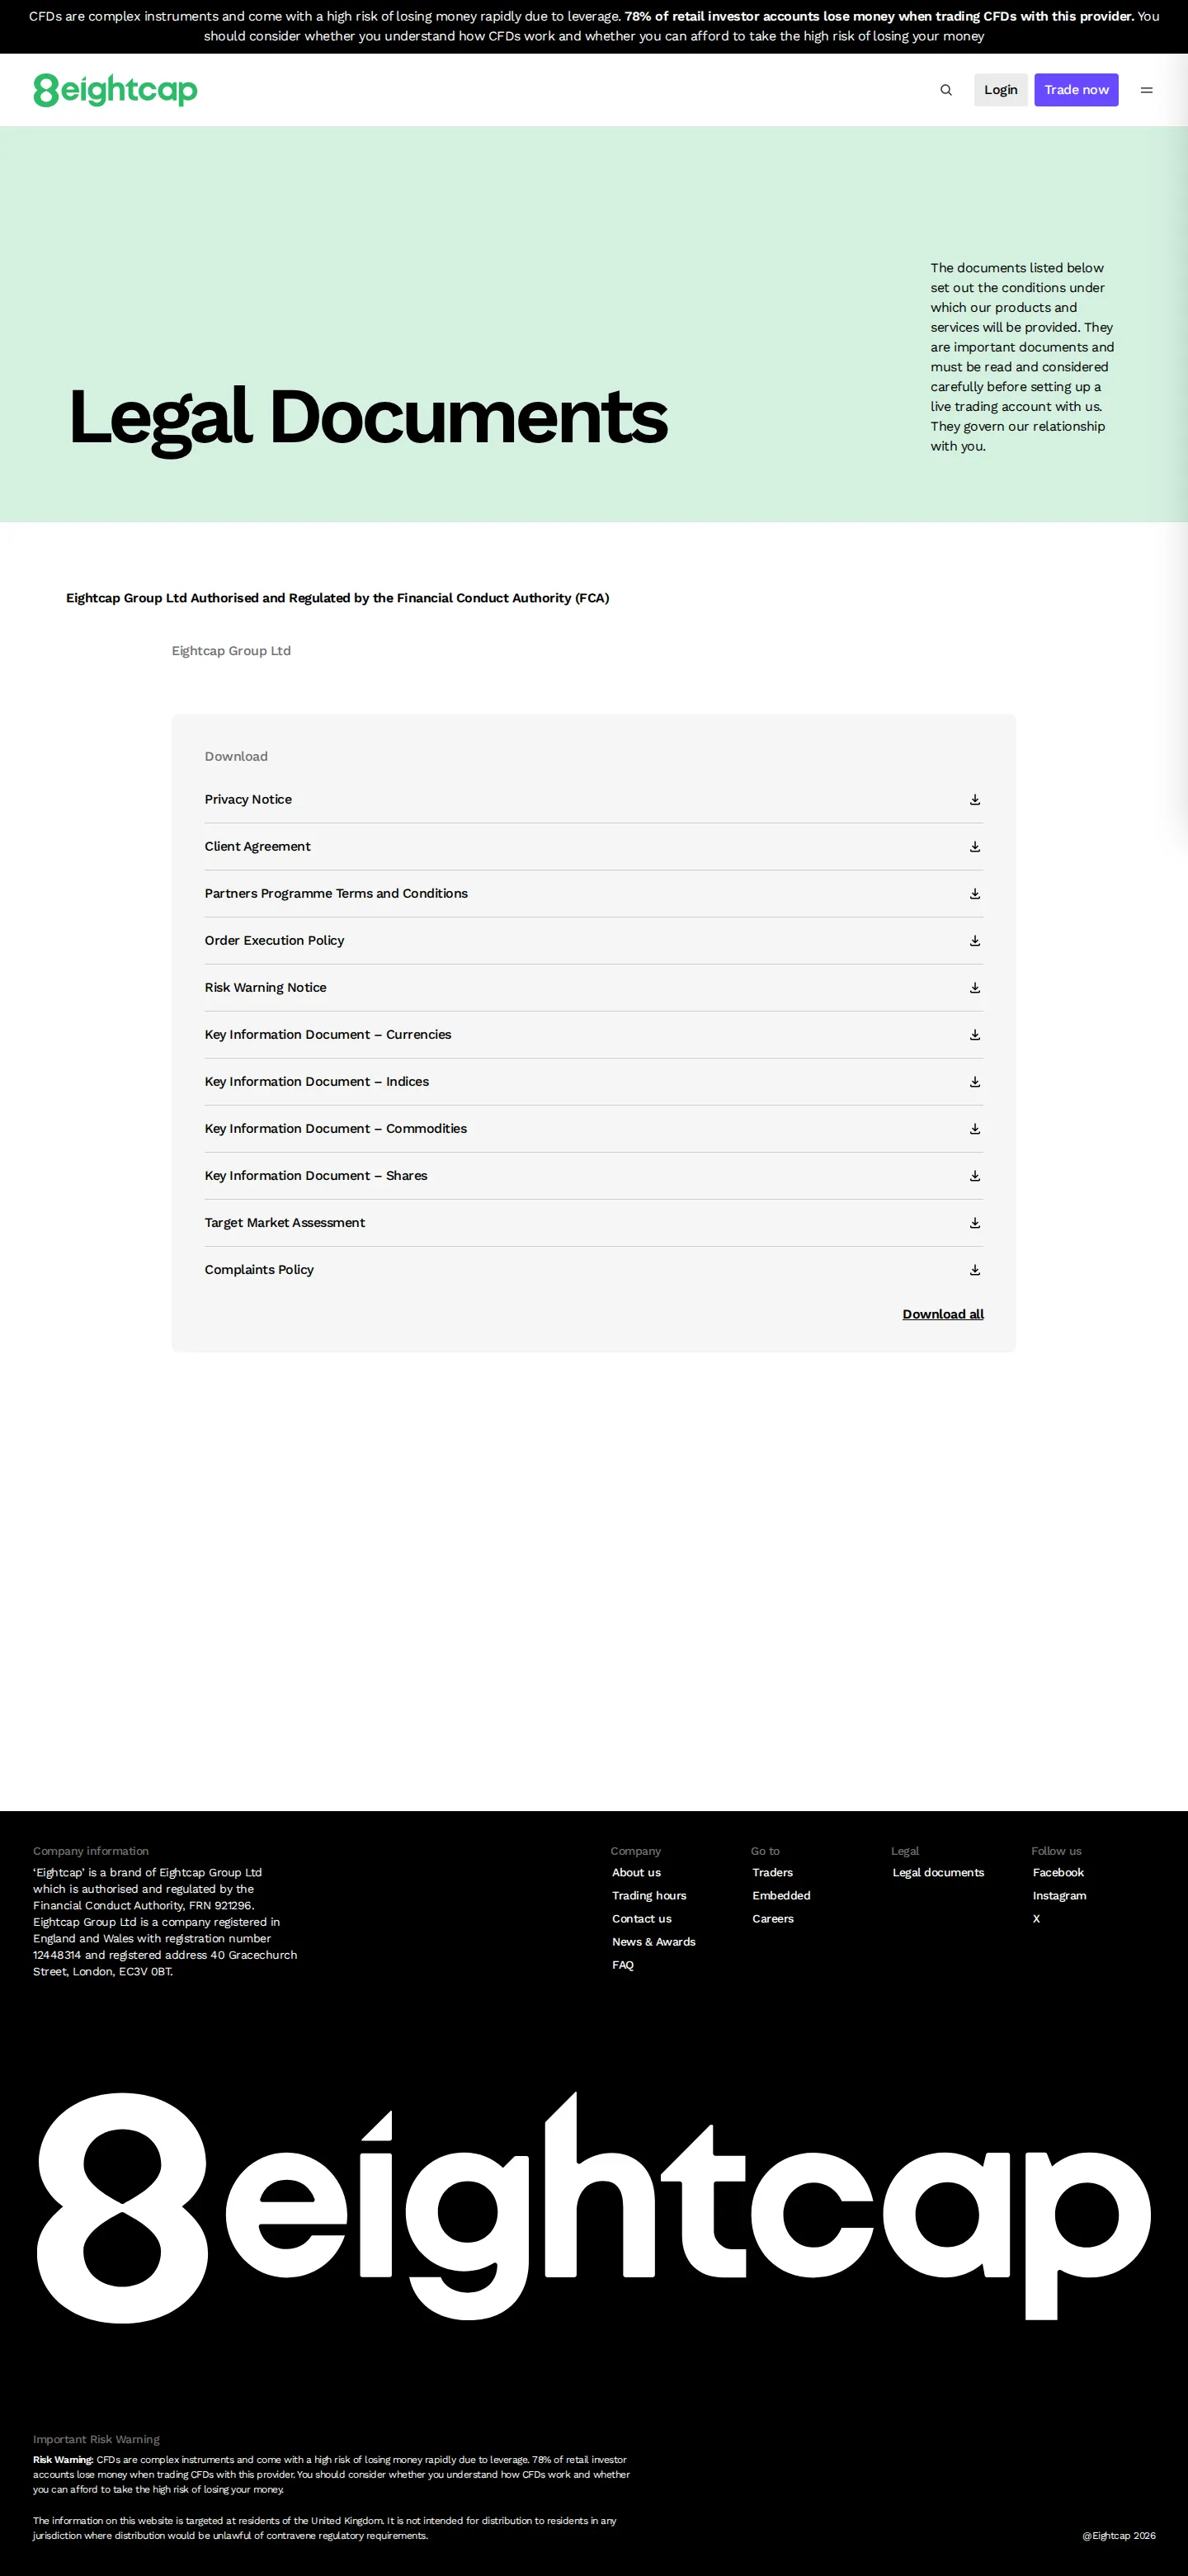
- Legal documents are split opaquely across different entities
Overview
TrueBroker is a free broker safety checker, and this page is our review of Eightcap, scored 6.9 out of 10 across regulation, fees, platform, support and reviews. Eightcap trades through a cluster of separately regulated entities rather than one company: Eightcap Pty Ltd in Australia, Eightcap Group Ltd in the UK, Eightcap EU Ltd in Cyprus, and three offshore entities, Eightcap International Ltd (Seychelles), Eightcap Global Limited (Bahamas) and Eightcap International Trading (Mauritius), plus a fourth registered office in Saint Vincent and the Grenadines that the firm’s contact page lists without naming a regulator against it.
Our previous score for Eightcap was 6.5/10; this review scores it 6.9/10. We’re restating that move from the current evidence rather than claiming the firm changed: fees carries the highest mark here at 8.6, backed by the firm’s own fee pages showing no internal charge on deposits or withdrawals and a published Raw account commission of $3.50 per side per standard lot. Regulation sits at 7.5, built on six licences we were able to check against the regulator’s own register rather than take on the firm’s word, three of them at tier-one regulators (ASIC, the FCA register, CySEC). Support pulls the total down at 4.3: Our evidence gives phone numbers only for the UK and Australian entities, and email plus a chat widget for everyone else.
Overview Table
| Headquarters | Melbourne, Australia (Eightcap Pty Ltd, Level 37, Rialto South Tower, 525 Collins Street, Melbourne 3000) |
| Established | 2015, per the firm’s UK about page |
| Countries Served | 140+ countries, per the firm’s own “Eightcap in numbers” claim on its Australian homepage |
| Regulated By | ASIC (AFSL 391441), FCA (FRN 921296), CySEC (246/14), Seychelles Seychelles FSA (SD100), Bahamas Securities Industry Act firms register (SIA-F220), Mauritian FSC (GB25204603) |
| Minimum Deposit | $100 for the Standard and Raw accounts; £100 for the TradingView account |
| Maximum Leverage | Not stated |
| Total Instruments | 850+ tradable assets per the firm’s homepage count; account pages separately cite 800+ CFD markets |
| Platforms | TradingView, MetaTrader 4, MetaTrader 5, TradeLocker (availability varies by entity) |
| Customer Support | Email and online chat everywhere; phone support only on the UK and Australian contact pages |
| Languages | Not stated |
Facts List
- The Australian Securities and Investments Commission register confirms AFS licence 391441 held by Eightcap Pty Ltd (ABN 73 139 495 944) since 29 April 2011.
- The Financial Conduct Authority register confirms FRN 921296 held by Eightcap Group Ltd, status Authorised, effective 23 December 2020, tied to Companies House number 12448314.
- The Cyprus Securities and Exchange Commission register confirms Eightcap EU Ltd holds CIF Licence Number 246/14 as an active investment-firm authorisation.
- The Seychelles FSA lists Eightcap International Ltd as a regulated securities dealer; the register itself does not publish licence numbers, so the “SD100” figure remains the firm’s own claim.
- The Securities Commission of The Bahamas lists Eightcap Global Limited as registered for dealing in and arranging deals in capital market instruments and trading CFDs, but the register publishes no registration-number column, so “SIA-F220” is unconfirmed by that register.
- The FSC Mauritius Online Public Register lists Eightcap International Trading as an SEC-2.1B Investment Dealer, licensed 7 October 2025; the register publishes no licence numbers, so the quoted GB25204603 itself is not confirmed.
- We searched 1,441 warning-list entries mirrored from CySEC, the FCA and the FSC Mauritius, and Eightcap appears on none of them.
- The firm’s UK, FCA-facing pages disclose that 78% of retail investor accounts lose money trading CFDs with this provider, while its CySEC-facing pages give 71.90% for Eightcap EU Ltd; the Bahamas, Seychelles and Mauritius entities only state that a “majority” of retail accounts lose money, without a figure.
- Eightcap’s fee page warns that maintaining fully matched (hedged) positions results in continuous, dual-sided overnight funding charges that will actively erode the account balance over time.
- The Raw account carries a $3.50 commission per side per standard lot (AUD, USD, NZD, SGD, CAD accounts), £2.25 on GBP accounts and €2.75 on EUR accounts, on top of spreads from 0.0 pips.
What Eightcap actually is
Eightcap is not a single licensed company; it is a brand run across at least seven entities, each carrying its own licence, its own client agreement, and in some cases its own loss-rate disclosure. A client dealing with the UK entity, Eightcap Group Ltd, is trading under an FCA authorisation and a stated 78% retail loss rate. A client onboarded through the Bahamas, Seychelles or Mauritius entities is dealing with a company we could only partly verify: the Bahamas and Seychelles registers confirm the company itself but publish no licence-number field to check the firm’s own SIA-F220 or SD100 figures against, and we have no register entry at all for the Mauritian regulator the firm names. None of that is a finding against Eightcap; it is a description of what we could and couldn’t check, and it means the strength of protection behind an Eightcap account depends heavily on which of its entities actually opened it.
Fees and the account structure
The firm’s own account pages describe two core tiers priced two different ways: Standard, commission-free with spreads from 1.0 pips, and Raw, spreads from 0.0 pips plus the $3.50-per-side commission set out above. Both carry a $100 minimum deposit. A third account, TradingView, sits at a £100 minimum, comes with margin call and stop-out levels of 80% and 50%, and is bundled with a free TradingView Plus subscription (the firm values it at £33.95 a month) that lapses if the client goes a calendar month without placing a trade. The fee page states no internal charge applies to deposits or withdrawals, while noting that third-party payment-provider fees may still apply.
Where the evidence runs out
The pages we fetched give no leverage figure for any account, so we’re not able to state a maximum. They also don’t lay out a supported-language list beyond the general note, repeated across the Indonesian and other translated pages, that where a translation is missing, inaccurate or incomplete, the English version of the site prevails. Deposit and withdrawal methods are described only in general terms, as “multiple payment methods,” with no specific channel or currency named on the pages we read.
Key Takeaways
Eightcap’s regulatory paper is the strongest part of this file. We confirmed AFSL 391441 on ASIC as Eightcap Pty Ltd, FRN 921296 on the FCA register as Eightcap Group Ltd (authorised, effective 23/12/2020), and CIF licence 246/14 on the CySEC register as Eightcap EU Ltd. The Seychelles FSA register lists Eightcap International Ltd as a regulated securities dealer, though that register does not publish licence numbers, so the firm’s own “SD100” tag is unconfirmed by the register itself. The Securities Commission of The Bahamas register lists Eightcap Global Limited as registered for dealing and arranging deals in capital market instruments and trading CFDs, again with no registration-number column, so “SIA-F220” is likewise the firm’s own label rather than something the register prints. Company registries back up the corporate shells: Companies House confirms Eightcap Group Ltd as company 12448314, the Seychelles company search confirms Eightcap International Ltd under C8427413, and the ASIC company dataset confirms Eightcap Pty Ltd under ABN 73 139 495 944. The FSC Mauritius register confirms Eightcap International Trading as an Investment Dealer licensed 7 October 2025, though not the GB25204603 number; the 227050 company number is unchecked, because the Mauritius company registry only answers a person at a browser. We searched 1,441 warning-list entries mirrored from CySEC, the FCA and the FSC Mauritius, and Eightcap matches none of them.
What Eightcap charges
The firm’s own account page prices the Raw account at $3.50 commission per side per standard lot in AUD, USD, NZD, SGD and CAD, £2.25 in GBP, and €2.75 in EUR, against a Standard account it describes as commission-free with spreads from 1.0 pips. Deposits and withdrawals carry no internal fee, per the platform page, though it also notes third-party payment-provider fees may still apply. The gold-spread figure of “as low as 0.120 pips” on the UK fee page is a marketing line tied to a promotional “Elevate your trading” claim, not a stated average or per-account number, so we’re reporting it as exactly that rather than as a representative cost.
The clause that costs hedgers money
Eightcap’s UK fee page carries its own warning, worth quoting exactly: “Maintaining fully matched positions will result in continuous, dual-sided cost adjustments that will actively erode your account balance over time.” That’s the firm telling its own clients that a hedged position gets charged the overnight funding fee on both legs, every night, with no offsetting market exposure to show for it. The same page ties a free TradingView Plus subscription, valued at £33.95 a month, to a rolling condition: “Just connect, trade and stay active with at least one trade per month to keep your rolling Plus access.” Miss a month of trading and the free plan lapses.
Where the loss-rate disclosure changes by entity
The UK/FCA-facing pages state that 78% of retail investor accounts lose money trading CFDs with this provider. The CySEC-facing pages for Eightcap EU Ltd give 71.90%. The Bahamas/Seychelles/Mauritius-facing pages give only an unquantified “majority of retail investor accounts lose money,” with no percentage. Three entities, three different disclosures, and the two regulated in the EU/UK are the only ones giving a number.
Support and documentation gaps
Support channels are an email address and a chat widget per region, plus registered office addresses for each entity, no phone line for the offshore entities and no live-chat detail beyond “click the button.” Legal documents for the Seychelles, Mauritius, Bahamas and SVG entities are only available as separate downloadable documents rather than shown inline, so which terms bind a given client depends on which entity onboarded them and isn’t readable from the page itself. Eightcap Pty Ltd’s own pages disagree with each other on its floor number, Level 37 on the contact/footer pages against Level 35 on the legal documents page, at the same Rialto South Tower, Melbourne address.
Score
Our previous score for Eightcap was 6.5/10; this review puts it at 6.9/10, restated from the current evidence rather than any change in the firm. Regulation sits at 7.5, carried by five confirmed licences across the FCA, ASIC and CySEC registers plus a clean 1,441-entry warning-list search, offset by the two entities, Mauritius and SVG, we could not check against a register. Fees score 8.6 on a published Raw commission structure and no internal deposit or withdrawal fee. Support is the weak point at 4.3, reflecting the thin channel list and the entity-fragmented legal documents. Platform comes in at 7.3 across TradingView, MetaTrader 4, MetaTrader 5 and TradeLocker, and reviews land at 6.7.
Licenses & Regulation
Eightcap trades under a different regulated entity depending on where the client is onboarded, and the four company-registration entries the firm publishes are not four licences: Eightcap International Ltd (Seychelles), Eightcap International Trading (Mauritius), Eightcap Global Limited (Bahamas) and CLMarkets Limited, trading as Eightcap International (Saint Vincent and the Grenadines), sit alongside three onshore-regulated entities: Eightcap Pty Ltd in Australia, Eightcap Group Ltd in the UK, and Eightcap EU Ltd in Cyprus.
What the registers confirm about Eightcap
Checking each licence the firm names against the regulator’s own record, the Australian Securities and Investments Commission register confirms AFS licence 391441 held by Eightcap Pty Ltd. The Financial Conduct Authority register confirms FRN 921296 held by Eightcap Group Ltd, status Authorised, effective 23 December 2020, with Companies House number 12448314. The Cyprus Securities and Exchange Commission register confirms CIF Licence Number 246/14 held by Eightcap EU Ltd, an active investment-firm authorisation rather than a bare company listing. The Seychelles FSA lists Eightcap International Ltd as a regulated securities dealer, though the register does not publish licence numbers, so the number “SD100” the firm prints on its own pages stays a claim we cannot check against that register. The Securities Commission of The Bahamas registrant list carries Eightcap Global Limited as registered for dealing in and arranging deals in capital market instruments, and for trading CFDs, as at 31 August 2026; that register publishes no registration-number column at all, so the company is confirmed and the number “SIA-F220” the firm quotes is not.
The FSC Mauritius Online Public Register lists Eightcap International Trading holding SEC-2.1B Investment Dealer (Full Service Dealer excluding Underwriting), licensed 7 October 2025. It publishes no licence numbers, so the GB25204603 the firm quotes for that entity is not itself confirmed.
Company registrations, which are not licences
Several of the numbers on Eightcap’s legal pages are company registrations, not financial-services permissions, and the firm’s own pages sometimes blur the two. Companies House confirms Eightcap Group Ltd as company 12448314, a private limited company incorporated 7 February 2020, status Active, a registry entry rather than a regulatory one. The Seychelles Business and Company Search confirms Eightcap International Ltd under registration C8427413 (the firm prints it as 8427413-1), industry listed as Business Services; the search publishes no status or incorporation date. The Cyprus Registrar of Companies, checked via a mirror of the official register, shows HE 329922 as an active limited company registered 24 February 2014 under the name R Capital Solutions Limited, not Eightcap EU Ltd; the mirror can lag a change of name, so a different name on the same HE number is not reported here as a different company. The Saint Vincent and the Grenadines FSA entity search confirms CLMarkets Limited under registration 24750, an active Business Company incorporated 7 May 2018 with Wilfred Services Ltd as registered agent; that authority registers companies and does not license forex or CFD brokers, so it confirms the company and nothing about a permission to deal. The Mauritius company registration quoted for Eightcap International Trading, number 227050, has not been checked: the Mauritius Corporate and Business Registration Department’s online search requires a person at a browser, and nobody has run that lookup yet.
What Eightcap’s own pages disclose about client outcomes, and where that disclosure changes
The loss-rate warning Eightcap publishes moves by entity. The UK, FCA-facing pages state that 78% of retail investor accounts lose money trading CFDs with this provider. The CySEC-facing pages for Eightcap EU Ltd give 71.90%. The Bahamas, Seychelles and Mauritius-facing pages carry only an unquantified warning that a majority of retail investor accounts lose money, without a percentage. The offshore entities are the ones a client is likely to be onboarded to outside the UK, Australia and the EU, and they are the ones that publish the least specific figure.
The AE contact page also lists a fourth registered office, in Saint Vincent and the Grenadines, alongside the Bahamas, Seychelles and Mauritius addresses; the company-information footer used across the AE, Singapore and Thailand pages names only the Bahamas, Seychelles and Mauritius entities as regulated. A registered office appears with no regulator named against it anywhere in what we read.
Running Eightcap’s names against the 1,441 warning-list entries we mirror from CySEC, the FCA and the FSC Mauritius returned no match. That covers only the regulators we mirror, not a global check, but it is a clean result worth recording.
This review scores regulation 7.5 out of 10, up from 6.5 previously. The move reflects our current assessment against the evidence above, not any change at the firm: three onshore regulators (ASIC, FCA, CySEC) confirm live licences against the firm’s own claimed numbers, and the warning-list search came back clean, while the same evidence also shows the firm mixing company registrations with licence claims on its own pages, two claimed licence numbers we could not check against a register, and a loss-rate disclosure that gets vaguer the further the entity sits from UK, EU or Australian oversight.
How to Trade
What Eightcap actually offers
The firm’s account pages describe two core structures repeated across jurisdictions: Standard and Raw. Eightcap’s UAE accounts page gives Standard as commission free with spreads “as low as 1.0 pips” and access to 800+ CFD markets, and Raw as spreads starting at 0.0 pips plus a $3.50 commission per lot per side (GBP2.25, EUR2.75 in those currencies). The Australian accounts page lists the same two tiers with a minimum deposit of $100 for both, trade sizes of 0.01 to 100 lots, and account base currencies in AUD, CAD, EUR, GBP, NZD, SGD or USD. UK customers do not get the same choice: the Raw account is not offered to them, leaving TradingView account holders there on a £100 minimum with margin call set at 80% and stop out at 50%, in GBP, EUR or USD.
On markets, the AE, ID and VN site menus list Forex, Crypto, Shares, Commodities and Indices. Eightcap’s UK site navigation, by contrast, lists only Forex, Shares, Commodities and Indices under “Most popular CFDs,” with no crypto category shown, matching a separate note in the evidence that MetaTrader 4 and MetaTrader 5 are also absent from the UK platform pages, which advertise TradingView only. So the instrument list and the platform list both narrow depending on which regulated entity a customer lands on.
Platforms Eightcap runs
Four platforms appear across the group’s pages: TradingView, MetaTrader 4, MetaTrader 5 and TradeLocker. The comparison table on the firm’s own platforms page gives TradingView 9 timeframes, 100+ indicators and 1000+ symbols; MetaTrader 4, 9 timeframes, 30 indicators and 1024 symbols; MetaTrader 5, 21 timeframes, 38 indicators (the running text separately says “80+”) and unlimited symbols; and TradeLocker, 15 timeframes and unlimited symbols, with all four listed as available on Windows, macOS, iOS, Android and web browsers, plus Linux for TradingView. TradeLocker is shown on the AE market pages but not on the AU platform pages, so which platforms a customer can actually open depends again on jurisdiction.
Eightcap also runs a promotion tying platform access to trading activity: funding an account unlocks a TradingView Plus subscription that the firm’s UK fee page values at £33.95 a month, on the condition, quoted from that page, to “connect, trade and stay active with at least one trade per month to keep your rolling Plus access.” A client who goes a month without placing a trade loses that subscription.
What it costs to hold a position
Beyond the per lot commission on Raw accounts, Eightcap’s UK fees page discloses an overnight funding fee, charged to any position held past 10pm UK time, applied for every night the position stays open. The same page carries a specific warning about hedging, quoted here: Maintaining fully matched (hedged) positions results in continuous, dual sided cost adjustments that will actively erode the account balance over time. That means a client running matched long and short positions to stay flat on market exposure is still charged the overnight fee on both sides of the trade, every night, regardless of net exposure. The fee amount itself is not quantified in the pages we read. Deposits and withdrawals carry no internal fee according to the same UK platforms page, though it also notes that third party or payment provider charges may still apply, without naming which providers or what those charges are.
The TradingView account carries a separate commission structure for share CFDs specifically, described on the UK platforms page as “from 0.1% depending on the exchange,” alongside its own version of the overnight funding fee for positions held past 10pm UK time.
Loss rate disclosures differ by entity
The retail loss figure Eightcap publishes changes depending on which regulated entity is serving the client. The UK (FCA facing) pages state that 78% of retail investor accounts lose money trading CFDs with this provider. The CySEC facing pages for Eightcap EU Ltd give 71.90%. The Bahamas, Seychelles and Mauritius facing pages carry only an unquantified statement that a majority of retail investor accounts lose money, without a percentage. Since execution terms, available instruments and platform access all vary by entity in the same pattern, which entity onboards a given customer determines not just their regulator but the specific commercial and risk terms they trade under.
Account Types
Eightcap sells three account types across its geo-targeted sites: Standard, Raw, and a TradingView account that only appears on the UK pages. Which of these is on offer, and on what terms, depends on which entity onboards the client, and the firm’s own account pages give different figures for the same account name depending on jurisdiction.
Standard and Raw accounts
The AE-facing accounts page lists a Standard account with a $100 minimum deposit, commission-free trading, spreads “as low as 1.0 pips,” and access to 800+ CFD markets. The Raw account carries the same $100 minimum and the same market access, with spreads starting at 0.0 pips plus a per-side commission the same page sets at $3.50 for accounts denominated in AUD, USD, NZD, SGD or CAD, £2.25 for GBP accounts, and €2.75 for EUR accounts, charged each side per standard lot traded.
The Australian accounts page describes the same two names with more operational detail: both Standard and Raw carry a $100 minimum, allow scalping, support base currencies AUD, CAD, EUR, GBP, NZD, SGD and USD, and set a trade size range of 0.01 to 100 lots. That page notes commission-free trading on Standard “(shares include commission)” and repeats the 0.0-pips-plus-commission structure for Raw, without restating the AE page’s per-currency commission table.
Raw is not universal: Eightcap’s UK markets page states the Raw account is not offered to UK customers, so a client onboarded through the FCA-regulated Eightcap Group Ltd is restricted to whichever accounts the UK site does carry.
The TradingView account at Eightcap
The UK platform page describes a separate TradingView account with a £100 minimum deposit, a margin call level of 80%, a stop-out level of 50%, base currencies of GBP, EUR or USD, and hedging and scalping both permitted. Eightcap’s UK fee page prices share CFDs on this account “from 0.1% depending on the exchange,” rather than the spread-plus-commission structure used on Standard and Raw.
Funding a TradingView account also unlocks a TradingView Plus subscription the UK fee page values at £33.95 a month, but the offer is conditional: the same page states a client must “connect, trade and stay active with at least one trade per month” to keep the rolling Plus access, so a client who goes a calendar month without placing a trade loses the subscription.
Overnight funding and hedged positions
Eightcap’s UK fee page states that a fee is charged “to hold positions past 10pm UK time,” applied for every night a position stays open, without quantifying the rate in the text we read. The same page carries a direct warning for clients who hedge: “maintaining fully matched positions will result in continuous, dual-sided cost adjustments that will actively erode your account balance over time,” meaning a client holding matched long and short positions is charged the overnight fee on both legs every night, regardless of net market exposure.
Deposits and withdrawals
The UK platform page states deposits and withdrawals carry “no internal fees,” while noting third-party payment-provider charges may still apply; it does not name the payment methods or currencies covered, and no fee schedule for those third-party charges appears in the pages we fetched.
What’s missing from the account pages
The AE and AU accounts pages describe Standard and Raw in near-identical terms but were not reconciled against each other for every field: the AE page gives a per-currency commission table for Raw that the AU page does not repeat, and the AU page gives a base-currency and lot-size range for both accounts that the AE page does not state. Neither account page we fetched sets out a minimum trade size, maximum leverage, or Islamic/swap-free terms, so those points are not reported here.
Negative Balance Protection
Eightcap’s loss-rate disclosure changes depending on which regulated entity signs the client up, and that is the clearest window this evidence gives into how the firm frames drawdown risk. The UK entity, Eightcap Group Ltd, holds FCA authorisation confirmed on the FCA register under FRN 921296, and its own risk page states “78% of retail investor accounts lose money when trading CFDs with this provider.” The Cyprus entity, Eightcap EU Ltd, holds CySEC licence 246/14 confirmed on the CySEC register of investment firms, and its pages carry a different number: 71.90% of retail investor accounts lose money when trading CFDs with Eightcap EU Ltd. The Bahamas, Seychelles and Mauritius-facing pages, which cover Eightcap Global Limited, Eightcap International Ltd and Eightcap International Trading, drop the exact figure and warn only that a “majority of retail investor accounts lose money,” with no percentage attached. A client reading the offshore version of the site is told less precisely how often accounts lose money than a client reading the UK or Cyprus version.
Margin calls and stop-outs, but only on one account
The only account page in this evidence that names an actual margin call level and stop-out level is the TradingView account: margin call at 80%, stop-out at 50%, with account base currencies of GBP, EUR or USD, and both hedging and scalping permitted.
What Eightcap’s overnight funding warning does to a hedged position
Eightcap’s UK fee page sets out an “Overnight Funding Fee” charged on positions held past 10pm UK time, without stating the rate, and attaches a direct warning to it: Maintaining fully matched (hedged) positions results in continuous, dual-sided cost adjustments that will actively erode the account balance over time. The same fee page repeats the warning elsewhere in blunter terms: “Maintaining fully matched positions will result in continuous, dual-sided cost adjustments that will actively erode your account balance over time.” What that means in practice: a client who opens a long and short position on the same instrument to sit flat against the market is still charged the overnight funding fee on both legs, every night either position stays open, so a hedge that looks market-neutral is not a way to avoid ongoing cost while a drawdown plays out.
What the pages we read do not cover
The fee page, the platform pages and the terms and conditions we read describe the overnight funding charge, the TradingView account’s margin call and stop-out levels, and the entity-by-entity loss-rate warnings above. They say nothing about a negative balance protection policy or a stated cap on client losses beyond deposited funds. Eightcap’s Australian site separately states that retail clients must assess a Product Disclosure Statement, Financial Services Guide and Target Market Determination before using its products, for the entity Eightcap Pty Ltd, confirmed on the ASIC register under AFSL 391441 and on the Australian Business Register under ABN 73 139 495 944. We did not read those three documents, so any margin-close-out or negative-balance wording specific to the Australian entity sits outside what this section can report.
The firm’s Client Agreement and Risk Disclosure Policy are also published separately for each regulated entity, Seychelles, Mauritius, Bahamas and SVG, as downloadable files rather than as inline site text, and the substantive drawdown and negative-balance terms in those documents were not among the text pulled from the pages listed here.
Trading Instruments
Eightcap’s own “Eightcap in numbers” panel, on the Australian homepage, claims “850+ Assets to trade with”. The market menus we pulled for the AE, ID and VN versions of the site break that headline into five categories: Forex, Crypto, Shares, Commodities and Indices.
What Eightcap lists as tradeable, and where crypto disappears
The asset list is not the same everywhere. The AU, AE and Singapore-facing markets pages all show Crypto CFDs as one of the “Most popular CFDs” categories. The UK markets page does not: its “Most popular CFDs” list runs Forex, Shares, Commodities and Indices only, with no crypto line, and the UK platforms page repeats the same four-category list. That gap sits alongside an odd cross-reference on the UK site’s own news and awards page, which cites Eightcap as “awarded Best in Class for Crypto Trading” by ForexBrokers.com’s 2026 Annual Awards, on the same entity’s pages that do not list crypto CFDs as a tradeable market. We report both facts as they stand in the pages we fetched: the award is quoted on a UK page, and the UK markets and platforms pages do not carry crypto CFDs in their published lists.
The UK pages carry a second gap: the Raw account, available elsewhere, is marked “not offered” to UK customers, alongside the crypto exclusion above.
Eightcap’s account tiers and what each one covers
Outside the UK, Eightcap runs two core account types on identical market access. The Standard account, per both the AE and AU account pages, asks a $100 minimum deposit for commission-free trading, spreads advertised “from 1.0 pips” and access to “800+ CFD markets”. The Raw account carries the same $100 minimum and the same market access, but drops spreads to “from 0.0 pips” and adds a commission the firm’s own accounts page prices at $3.50 per side per standard lot in AUD, USD, NZD, SGD and CAD, £2.25 in GBP, and €2.75 in EUR. Both tiers permit scalping, and the AU account page lists trade sizes running from 0.01 to 100 lots with base currencies in AUD, CAD, EUR, GBP, NZD, SGD or USD.
The TradingView account is a separate, narrower product built around that one platform. The UK platforms page sets its minimum deposit at £100, gives access to “600+ instruments” against the 800+ quoted for Standard and Raw, and sets a margin call level of 80% and a stop-out level of 50%, with base currencies limited to GBP, EUR or USD. Hedging and scalping are both permitted on it.
Platform access splits by jurisdiction too
Which platform a client can use depends on which of Eightcap’s regulated entities onboards them, and the evidence shows the split runs along the same lines as the asset gaps above. The AE, ID and VN platform pages advertise four platforms: TradingView, MetaTrader 4, MetaTrader 5 and TradeLocker. The UK site drops MT4 and MT5 entirely and offers TradingView only. The Cyprus-facing (CySEC, Eightcap EU Ltd) site drops MT4 but keeps TradingView and MT5. TradeLocker, in turn, appears on the AE pages but not on the Australian platform pages we checked. None of this is disclosed as a single comparison table across entities; it has to be pieced together from the separate geo-specific pages the firm publishes for each of Eightcap International Ltd (Seychelles), Eightcap Pty Ltd (Australia), Eightcap Group Ltd (UK) and Eightcap EU Ltd (Cyprus).
On fees tied directly to what gets traded: the TradingView account carries an unquantified overnight funding fee for positions held past 10pm UK time, and the firm’s own fees page warns that maintaining fully matched (hedged) positions results in continuous, dual-sided cost adjustments that will actively erode the account balance over time, a cost that falls specifically on hedged positions rather than on the instrument itself.
Education & Analysis
Eightcap’s Middle East/Asia facing site lists four platforms: TradingView, MetaTrader 4, MetaTrader 5 and TradeLocker. The firm’s own platform comparison table on that page gives specifics for each: TradingView with 9 timeframes, 100+ indicators and 1000+ symbols; MetaTrader 4 with 9 timeframes, 30 indicators and 1024 symbols; MetaTrader 5 with 21 timeframes and, in the comparison table specifically, 38 indicators (the marketing copy elsewhere on the same page rounds this to “80+”), with unlimited symbols; and TradeLocker with 15 timeframes and unlimited symbols. TradingView is described as letting a client “trade directly from TradingView’s charts” with 15+ chart types and access to what the page calls 100,000+ indicators and social trading, and MetaTrader 5 is pitched on “powerful trading tools” alongside its indicator count. TradeLocker’s own line promises advanced charting, more than 100 indicators and TradingView integration for deeper analysis.
What Eightcap actually offers UK clients
The platform list above does not hold across every regulated entity. The UK site’s navigation and platform pages advertise TradingView only; MetaTrader 4 and MetaTrader 5 do not appear there. The EU/CySEC-facing site sits in between: MetaTrader 4 is absent, but MetaTrader 5 and TradingView are both offered. Eightcap’s own AE platform page confirms the same split from the other direction, noting MetaTrader 4 is not listed for the EU or GB entities. TradeLocker follows the same pattern in reverse: it appears on the AE market pages but is not listed on the AU platform pages. A trader’s choice of charting and automation tooling, in other words, depends on which of Eightcap’s regulated entities they are onboarded with, not on a single global product line.
MetaTrader 4 and MetaTrader 5
Where MT4 is offered, Eightcap’s own copy pitches it for automated strategies, 24/7 trading robots, 30+ built-in indicators, matching the 30-indicator figure in the comparison table. MT5 is pitched for its wider timeframe range and indicator count, and the AE evidence separately notes a FlashTrader integration mentioned on the Indonesian platform page, which is not described further in what we read. Both platforms are listed as available on Windows, macOS, iOS, Android and web browser, per the UAE platforms page comparison table (the AE copy adds Linux for TradingView specifically).
TradeLocker and the TradingView Plus tie-in
TradeLocker is offered as a third charting and execution option on the AE-facing pages, built around what Eightcap calls “seamless TradingView integration for deeper analysis,” though the firm’s own text does not spell out what that integration covers beyond charting. On the UK site, Eightcap goes further with TradingView itself: The firm’s UK fees page advertises that funding an Eightcap account unlocks a TradingView Plus plan (valued at £33.95/month). The same page attaches a condition to that benefit: “just connect, trade and stay active with at least one trade per month to keep your rolling Plus access.” A client who stops trading for a month loses the subscription, so the “free” analysis tooling is really a rolling perk tied to trading activity rather than a one-time unlock.
Where charting tools meet Eightcap’s fee structure
The TradingView account carries its own commission and financing terms, separate from the Standard and Raw accounts. The UK platform page states TradingView-account commission runs “from 0.1% depending on the exchange” for share CFDs, and that an overnight funding fee applies to positions held past 10pm UK time, without quantifying the rate in this text. Eightcap’s fee page carries a specific warning about this mechanic for anyone charting and holding two-sided exposure: maintaining fully matched (hedged) positions results in continuous, dual-sided cost adjustments that will actively erode the account balance over time. In other words, the charting platforms are free to open, but a client using them to run hedged positions pays overnight financing on both legs, every night, regardless of net market exposure.
What the pages don’t show
Across all the platform and markets pages we read, Eightcap does not publish independent test results, execution-speed data, or third-party charting reviews; what we have is the firm’s own indicator, timeframe and symbol counts for each platform, and those counts are not consistent even within the firm’s own material, as the MT5 indicator figure above shows (38 in the comparison table against “80+” in the marketing text on the same page).
Special Offers
The clearest promotional item in the pages we fetched is not a deposit bonus or a cashback scheme: it is a bundled subscription. The fee page states that a client who funds an Eightcap account can “unlock a TradingView Plus plan (valued at £33.95/month)”, subject to the condition: “Just connect, trade and stay active with at least one trade per month to keep your rolling Plus access.” That is the whole mechanism as the firm states it: fund the account, get the subscription, and keep it only by placing at least one trade every month. A client who goes quiet for a calendar month loses the £33.95/month benefit, since the access is described as rolling rather than a one-off credit. Neither page we fetched sets out what happens the month a client falls short, whether the plan lapses immediately or on a grace period, or whether it reactivates automatically once trading resumes; the fee page states the monthly-trade condition and nothing about its mechanics beyond that.
What Eightcap’s TradingView Plus offer actually ties together
The offer sits on top of the TradingView account rather than being independent of it: the platforms page describes the TradingView account itself as carrying a £100 minimum deposit, a margin call level of 80%, a stop-out level of 50%, and base currencies of GBP, EUR or USD. The TradingView Plus subscription is pitched as a reason to fund that account rather than the Standard or Raw accounts, both of which the AE accounts page prices through spreads and, on Raw, a $3.50-per-side commission with no mention of a bundled subscription or credit. The fee page we read also warns, in the same breath as the overnight funding fee, that maintaining fully matched (hedged) positions results in continuous, dual-sided cost adjustments that will actively erode the account balance over time, a warning about a cost mechanic, not a promotion, but worth noting because it sits on the same page as the TradingView Plus pitch and the account it is bundled with is one many hedging or scalping style traders would gravitate to for the “advanced charting” pitch.
A marketing figure, not a documented promotion
The same UK fee page also carries a separate marketing line under the heading “Elevate your trading”, quoting spreads “as low as 0.120 pips on gold”. The fee material we read flags this itself as a promotional claim rather than an average or a per-account figure, and the page attaches no conditions, no qualifying account, and no time window to it. We are not able to say what account tier that figure applies to, or whether it is a standing marketing claim rather than a time-limited offer, because the page we fetched does not separate the two.
What we did not find
The account pages we fetched for the Standard, Raw and TradingView tiers describe pricing through spreads and, on Raw, per-lot commission, and none of the fee, accounts or platform pages we read mentions a welcome bonus, a deposit-matching offer, a cashback scheme, or a refer-a-friend credit. That reflects the pages our review process fetched, not a survey of every page Eightcap publishes across its various regulated entities: the contact and legal material list four separate regional entities (Seychelles, Mauritius, Bahamas and Saint Vincent and the Grenadines) each with its own set of legal documents held as separate downloads, and a promotions page specific to one of those entities may exist without having been among the pages we read. The warning-list search covered 1,441 entries mirrored from CySEC, the FCA and the Mauritius FSC, and Eightcap does not appear on any of them, though that check is about regulatory warnings rather than promotional terms and has no bearing on whether a given offer’s conditions are fair.
Opening an Account
Eightcap does not onboard through one company. Which entity signs the client up depends on where they say they live: Eightcap International Ltd (Seychelles), Eightcap International Trading (Mauritius), Eightcap Global Limited (the Bahamas) and, per the firm’s own legal documents page, CLMarkets Limited trading as Eightcap International (Saint Vincent and the Grenadines) between them cover the offshore markets, while Eightcap Group Ltd (FCA, UK), Eightcap EU Ltd (CySEC, Cyprus) and Eightcap Pty Ltd (ASIC, Australia) handle the regulated markets. The firm’s own legal documents page states that the Client Agreement, Risk Disclosure Policy, Complaints Handling Policy and Privacy Policy are organised separately for each of the Seychelles, Mauritius, Bahamas and SVG entities, with the Bahamas entity also carrying its own Website T&Cs, Partners Programme T&Cs, EULA and AML/Client Verification Requirements document, and each is only available as a download rather than shown on the page itself. That means the account terms a new client actually agrees to, and what verification that entity demands, depend on which of these companies takes them on, and the substance of any one of those documents was not read for this section.
What Eightcap asks for at the minimum deposit
The firm’s account-types page gives a $100 minimum deposit for both the Standard and Raw accounts. The same $100 figure appears on the Australian accounts page for Eightcap Pty Ltd’s Standard and Raw accounts. Opening through the TradingView-integrated account instead carries a £100 minimum, per the platform page aimed at UK clients, denominated in the currency of that market rather than the $100 used elsewhere. Account base currencies on the Australian accounts page are listed as AUD, CAD, EUR, GBP, NZD, SGD and USD; the TradingView account page lists GBP, EUR and USD.
Who Eightcap won’t sign up, or won’t sign up the same way
The firm’s own UK markets page does not offer the Raw account to UK customers. The same UK markets page does not list Crypto CFDs among its “Most popular CFDs,” where the AE, Australian and other market pages do, so a client onboarded through the UK entity is opening into a narrower product set than one onboarded offshore. For Australian retail clients, the firm’s own root page states that a Product Disclosure Statement, Financial Services Guide and Target Market Determinations must be assessed and considered before using products or services, which puts a documentation step ahead of trading for that entity specifically that the offshore pages do not mention. More generally, the Indonesian-facing legal page states that the site’s information is not intended for distribution to residents of jurisdictions where that distribution would be unlawful or contravene regulatory requirements, and the UK risk page states that the UK site’s content is targeted specifically at UK residents and not intended for distribution elsewhere where that would be unlawful. Neither page names the jurisdictions this excludes.
The language a client actually signs in
Both the Indonesian-facing legal page and the AE markets page carry the same disclaimer in Eightcap’s own words: the firm “makes reasonable efforts to provide accurate translations of the website in other languages for your convenience,” but “where content is missing, inaccurate or incomplete, the English version prevails.” A client who opens an account reading a translated version of the site is agreeing to whatever the English version says, not necessarily to what the translation showed them.
Funding and the TradingView tie-in
On the UK-facing fees and platform pages, Eightcap advertises that funding an account unlocks a TradingView Plus subscription it values at £33.95 a month, on the condition, in the firm’s own wording, to “just connect, trade and stay active with at least one trade per month to keep your rolling Plus access.” A client who opens the account, funds it, and then goes a calendar month without placing a trade loses that access under the terms as published.
Beyond the deposit minimums, the entity-dependent document set and the AU disclosure step above, the pages fetched for this review do not set out a numbered sign-up flow or list the identity documents Eightcap asks a new client to upload, so none is reported here.
Deposits & Withdrawals
We hold no dedicated deposits-and-withdrawals policy page for Eightcap; the only text touching payment mechanics comes from the UK platforms page and the UK fees page, and it is thin. Both say the same thing: “Deposit and withdraw funds quickly wherever you are, with multiple payment methods and no internal fees.” No method is named, no currency is named, no processing time is given, and no minimum or maximum withdrawal figure appears anywhere in the pages we fetched. “No internal fees” is the firm’s own phrase and we report it as such, but it is paired in the same sentence with an acknowledgement that third-party or payment-provider fees may still apply, so it is not a claim that a withdrawal costs nothing, only that Eightcap does not add its own charge on top of whatever the payment rail takes.
What Eightcap actually charges, according to the pages we read
Eightcap’s account-types page sets minimum deposits at $100 for both Standard and Raw accounts, and the UK TradingView-account page gives the same account a £100 minimum in that jurisdiction. None of the three account pages we read states a minimum withdrawal, a withdrawal processing window, or a cap on how much can be moved out in a single request. Where the evidence is silent, we say so rather than filling the gap: we cannot tell a reader whether a $50 withdrawal is possible or whether it takes a day or a week, because the firm’s own pages we fetched do not cover it.
The cost that keeps eating the balance between deposit and withdrawal
The one recurring charge documented in detail sits between funding and cashing out, not at either end of it. Eightcap’s UK fees page describes an Overnight Funding Fee applied to any position held past 10pm UK time, and states plainly that maintaining fully matched (hedged) positions results in continuous, dual-sided cost adjustments that will actively erode the account balance over time. That is the firm’s own warning, not our inference: a client who hedges is charged the fee on both legs of the position, every night, regardless of net market exposure. The same fee is mentioned for the TradingView account specifically on the firm’s UK platforms page, again without being quantified as a rate; we can report that the fee exists and how it behaves, not what it costs in points or currency, because the page we read does not price it.
Trading costs that reduce what reaches a withdrawal in the first place
Alongside the funding fee, the Raw account carries a per-side commission of $3.50 in AUD, USD, NZD, SGD and CAD, £2.25 in GBP, and €2.75 in EUR, charged per standard lot traded, per Eightcap’s account-types page. The Standard account is described as commission-free, with the cost instead built into a wider spread. The TradingView account carries its own commission structure on share CFDs, described on the UK platforms page as starting from 0.1% depending on the exchange, again with no fixed schedule given. None of these are deposit or withdrawal fees as such, but they set how much of a deposit survives to be withdrawn, so we include them here rather than let a reader assume the “no internal fees” line covers the whole cost of moving money through the account.
A conditional benefit tied to ongoing activity, not a one-off deposit bonus
The UK fees and platforms pages both advertise a TradingView Plus subscription, valued by the firm at £33.95 a month, unlocked by funding an Eightcap account. The condition is stated in the firm’s own words: “Just connect, trade and stay active with at least one trade per month to keep your rolling Plus access.” That means the benefit is not secured by the deposit itself; a client who funds the account and then stops trading for a month loses it. We note this because it is the closest thing to a deposit-linked incentive in the evidence, and its mechanics work against inactivity rather than against withdrawal.
Which entity a client’s money actually sits with
Eightcap operates through separate regulated entities for different regions, confirmed across the registers we checked: Eightcap Group Ltd under FCA reference FRN 921296 in the UK, Eightcap EU Ltd under CySEC licence 246/14 in Cyprus, Eightcap Pty Ltd under ASIC licence AFSL 391441 in Australia, Eightcap Global Limited on the Securities Commission of The Bahamas registrant list under SIA-F220, and Eightcap International Ltd listed by the Seychelles FSA as a regulated securities dealer. The firm’s own legal-documents page describes the Client Agreement, Risk Disclosure Policy and Complaints Handling Policy as organised separately per entity, available only as downloadable documents rather than shown inline, so which set of terms governs a deposit or a withdrawal depends on which of these entities onboarded the client, and we did not have the text of those downloadable agreements to read for this section.
Score
Our previous score for Eightcap was 6.5/10; this review scores 6.9/10. The fees criterion sits at 8.6 in this pass, the highest of the five, which lines up with what the evidence supports on the cost side: a published $100/£100 minimum deposit, a stated Raw-account commission schedule with exact figures across seven currencies, and a firm-published “no internal fees” line on deposits and withdrawals. Support sits at 4.3, the lowest criterion, and the evidence here explains why on this specific topic: no withdrawal timeframe, no withdrawal minimum or maximum, and no named payment method appears anywhere in the pages we fetched, so a client with a withdrawal question has nothing on these pages to check against. We are restating the score from the current evidence and the current scoring criteria, not reporting any change in how Eightcap itself runs its payments.
Customer Support
Eightcap runs support through whichever of its five entities opened the account, and the pages we fetched show that entity, not “Eightcap” generically, decides the phone number, the office address and the policy document a complaint has to go through.
The channels Eightcap actually lists
For clients onboarded under Eightcap International Ltd (Seychelles), Eightcap International Trading (Mauritius), Eightcap Global Limited (Bahamas) or CLMarkets Limited (Saint Vincent and the Grenadines, trading as Eightcap International), the contact pages give one global address, global@eightcap.com, and an instruction to click the button in the bottom-right corner to chat online (the firm’s Indonesian contact page; the firm’s UAE contact page). No phone number is given for any of these four entities on the firm’s UAE contact page, and that page does not state support hours. The same two pages list four registered offices for written correspondence: Office 12, 3rd Floor, IMAD Complex, Ile Du Port, Mahe, Seychelles; 201 Church Street, Sandyport, Nassau, Bahamas; The Cyberati Lounge, Ground Floor, The Catalyst, Silicon Avenue, 40 Cybercity, Ebene, Mauritius; and Suite 305, Griffith Corporate Centre, PO Box 1510, Beachmont, Kingstown, Saint Vincent and the Grenadines.
Australian clients of Eightcap Pty Ltd get a dedicated line: customerservice@eightcap.com and +61 3 8375 9700, tied to the Melbourne office. UK clients of Eightcap Group Ltd get their own line too: customerservice-uk@eightcap.com and +44 333 1503 027, tied to 40 Gracechurch Street, London. We did not find a separate contact page for Eightcap EU Ltd, the entity holding the CySEC licence, among the pages fetched for this review.
Which regulator stands behind Eightcap’s support, entity by entity
The Seychelles FSA lists Eightcap International Ltd as a regulated securities dealer, and the Securities Commission of The Bahamas lists Eightcap Global Limited as a registrant for dealing in and arranging capital market instruments and trading CFDs, so a client under either entity has a named financial regulator to escalate a complaint to beyond the firm itself. The Saint Vincent and the Grenadines FSA entry we found for CLMarkets Limited shows registration 24750 IBC 2018, a BC-Business Company, status Active, incorporated 2018-05-07, with Wilfred Services Ltd as registered agent, but that authority registers companies and does not license forex or CFD brokers, so it confirms the company behind the SVG office listed on the contact page and not a financial licence a client of that entity could appeal to. The FSC Mauritius register likewise lists Eightcap International Trading as a licensed Investment Dealer, so a client of the Mauritius entity also has a named regulator to escalate to.
An Eightcap address that doesn’t match itself
Eightcap Pty Ltd’s own pages disagree on its floor number: the contact and footer pages give “Level 37, Rialto South Tower, 525 Collins Street, Melbourne, VIC, 3000” while the legal documents page gives ‘The Rialto’, South Tower, Level 35/525 Collins St, Melbourne VIC 3000. A client trying to send formal written correspondence, including a complaint, has two different floor numbers to choose between on the firm’s own site.
Where the complaints policy actually lives
Eightcap does not publish its Complaints Handling Policy, Client Agreement or Risk Disclosure Policy inline. Each is a separate downloadable document, organised per regulated entity, and for the Bahamas entity the same page also lists separate Website Terms and Conditions, Partners Programme Terms and Conditions, an End User Licence Agreement and AML/Client Verification Requirements. Which document governs how a complaint is handled, and what it promises a client, depends on which of the entities above onboarded them, and none of that substantive text is readable from the page that lists the documents; a client has to identify their entity first and then download the matching file.
Support promises that don’t survive translation
Eightcap’s own footer states: “Eightcap International Ltd makes reasonable efforts to provide accurate translations of the website in other languages for your convenience. Where content is missing, inaccurate or incomplete, the English version prevails.”. A client reading the site, including any contact or complaints instructions, in a translated language is bound by the English version wherever the translation falls short, regardless of whether they can read English.
Prohibited Countries
Eightcap trades under at least seven separately incorporated entities: Eightcap International Ltd (Seychelles), Eightcap International Trading (Mauritius), Eightcap Global Limited (Bahamas), CLMarkets Limited trading as Eightcap International (Saint Vincent and the Grenadines), Eightcap Pty Ltd (Australia), Eightcap Group Ltd (United Kingdom) and Eightcap EU Ltd (Cyprus). None of the pages we fetched from this firm carries a named list of prohibited or restricted countries. What the pages carry instead is generic distribution language and a set of entity-by-entity differences in what is actually on offer, and that is what we can report.
What Eightcap’s own pages say about distribution
The Indonesia-facing legal page describes the site’s information as general in nature and states it is not intended for distribution to residents of jurisdictions where that distribution would be unlawful or would contravene local regulatory requirements. It does not name a single jurisdiction that requirement is meant to catch. The UK risk-warning page makes a narrower version of the same point from the other direction: it states that the UK site’s content is targeted specifically at residents of the United Kingdom and is not intended for distribution elsewhere where doing so would be unlawful, again without naming which other countries that covers. Both statements tell a reader that some unnamed jurisdictions are excluded somewhere in Eightcap’s group; neither page tells a reader which ones.
Where Eightcap International Ltd, Eightcap Group Ltd and the others actually apply
The Indonesia legal page notes that Eightcap’s legal documents, including the Client Agreement, Risk Disclosure Policy, Complaints Handling Policy and Privacy Policy, are organised separately per regulated entity, with the Bahamas entity carrying additional documents (Website Terms and Conditions, Partners Programme terms, an End User Licence Agreement and AML/client-verification requirements) that the others do not. Which entity signs up a given client, and therefore which set of these documents governs the relationship, is not spelled out on the page itself: a client only finds out which downloadable document set applies to them once they are already assigned to one of the four offshore or onshore entities. The AE contact page also lists a registered office in Saint Vincent and the Grenadines alongside the Bahamas, Seychelles and Mauritius offices, but the company-information footer on the Indonesia legal page names only the Bahamas (SCB), Seychelles (FSA) and Mauritius (FSC) entities as regulated. The SVG office appears with no regulator named against it anywhere in the pages we read.
What Eightcap’s UK entity does not offer its own customers
Rather than naming excluded countries, Eightcap’s UK-facing pages document a narrower set of exclusions that apply to UK customers specifically, regardless of where else in the group those products exist. The UK markets page does not offer the Raw account to UK customers, and does not list crypto CFDs among the UK site’s “Most popular CFDs” (Forex, Shares, Commodities and Indices only), where the AU and AE market pages list crypto CFDs as a category. The UK site’s navigation and platform pages advertise only TradingView; MetaTrader 4 and MetaTrader 5, offered elsewhere in the group, do not appear there. Eightcap’s CySEC-regulated EU entity has its own narrower cut: MetaTrader 4 is absent from its platform list too, though MetaTrader 5 and TradingView remain.
Eightcap Pty Ltd and Australian retail clients
Eightcap’s Australian homepage states that a Product Disclosure Statement, a Financial Services Guide and Target Market Determinations must be assessed and considered by Australian retail clients before they use Eightcap Pty Ltd’s products or services. That is a disclosure and suitability step the firm’s own page describes for a client the firm has already decided to onboard, not a claim that any class of person is barred from opening an account.
What our crawl actually found for Japan and South Africa
We did not fetch a page from Eightcap naming Japan or South Africa as either a licensed market or an excluded one. What we did find is that the same geo-targeted copy of Eightcap’s main marketing page served for the “ae” (UAE) site variant is also served, unchanged, for the “jp” (Japan) and “za” (South Africa) site variants. On the evidence we hold, that shows the marketing site presenting Japan- and South-Africa-styled pages to visitors from those variants; it does not show a licence, a registration or a restriction attached to either country, because none of the pages we read name one.
Conclusion
Eightcap scores 6.9 out of 10 in our assessment, up from the 6.5 we gave it previously. The move is ours, not the firm’s: this review rests on the same live licence checks across six regulators plus a clean sweep of 1,441 mirrored CYSEC, FCA and FSC Mauritius warning entries, and the fee and platform detail we read directly from the firm’s own account and fee pages carried the fees and platform criteria higher than our prior pass had them. Support did not move with the rest: at 4.3 it is the weakest criterion in this scorecard and the one a reader should weigh most heavily before funding an account.
What the registers confirm about Eightcap
The entity a client actually signs with depends on where they are. Eightcap Group Ltd holds FCA reference number 921296, confirmed on the FCA register as authorised, effective 23 December 2020, and the same company sits on Companies House as number 12448314, a private limited company incorporated 7 February 2020, status active. Eightcap EU Ltd holds CySEC licence 246/14, confirmed on the Cyprus Securities and Exchange Commission’s register of Cypriot investment firms as an active investment firm authorisation, not merely a company filing. Eightcap Pty Ltd holds AFS licence 391441, confirmed by ASIC and cross checked against the ASIC company dataset, which also confirms ABN 73 139 495 944 as a registered proprietary company since 16 September 2009.
Outside those three, the picture thins. The Seychelles FSA lists Eightcap International Ltd as a regulated securities dealer, but the register publishes no licence numbers, so the number “SD100” printed on the firm’s own pages is the firm’s claim, not something the register itself states. The Securities Commission of The Bahamas lists Eightcap Global Limited as a registrant for dealing in and arranging capital market instruments and trading CFDs as at 31 August 2026, again with no registration number column, so “SIA-F220” is confirmed as far as the company goes and unconfirmed as a number. CLMarkets Limited, trading as Eightcap International for Saint Vincent and the Grenadines clients, is active on the SVG FSA’s company register, incorporated 7 May 2018, but that register records companies, not financial licences, and SVG does not license forex or CFD brokers at all. The Mauritius entity, Eightcap International Trading, is on the FSC Mauritius register as an Investment Dealer licensed 7 October 2025.
What Eightcap charges
The firm’s own account pages set out two core tiers with a $100 minimum deposit each: Standard, commission free with spreads from 1.0 pips, and Raw, spreads from 0.0 pips plus a $3.50 commission per side per standard lot in AUD, USD, NZD, SGD and CAD (GBP2.25, EUR2.75 in those currencies). UK clients get a third option, the TradingView account, with a £100 minimum and share CFD commission from 0.1% depending on the exchange, but the same UK fee page discloses that Raw is not offered to UK customers at all. Deposits and withdrawals carry no internal fee on the firm’s own account pages, though third party payment provider charges may still apply, and that page does not say which providers or currencies are involved.
The fee page’s overnight funding disclosure is worth reading past the number, since there isn’t one published here: the firm states plainly that “we charge a fee to hold positions past 10pm UK time,” and warns that maintaining fully matched (hedged) positions results in continuous, dual sided cost adjustments that will actively erode the account balance over time. A client who hedges to stay flat is still paying funding on both legs every night. The same fee page markets spreads “as low as 0.120 pips on gold” under an “Elevate your trading” banner, a promotional figure rather than a stated average for any specific account.
What Eightcap offers on platforms and support
Eightcap’s own pages list four platforms across its wider site: TradingView, MetaTrader 4, MetaTrader 5 and TradeLocker. UK and EU clients see a narrower set: the UK’s own platform page offers only TradingView, and the EU (CySEC) pages drop MetaTrader 4, leaving TradingView and MetaTrader 5. The UK fee page also runs a promotion tying a free TradingView Plus subscription, quoted at £33.95 a month, to account activity: “just connect, trade and stay active with at least one trade per month to keep your rolling Plus access.” A client who goes quiet for a month loses the benefit.
Support channels, by contrast, are thin next to the platform build out. The pages we fetched list an email address and an online chat widget for the global entities, plus a UK phone line and a separate Australian phone line for those two regulated entities; there is no live phone number published for Seychelles, Bahamas, Mauritius or SVG clients in this evidence, only registered office addresses and the shared email. That gap, more than any single figure, is what holds the support score down at 4.3.
Eightcap on the warning lists
We searched 1,441 warning list entries mirrored from CySEC, the FCA and the FSC Mauritius, and Eightcap and its named entities appear on none of them. That coverage extends only to the three regulators we mirror, not to every regulator worldwide, so it is a clean result within that scope rather than a clearance from any wider body.
Eightcap holds confirmed FCA, CySEC and ASIC licences alongside its offshore Seychelles, Bahamas and SVG entities, clears all 1,441 mirrored CySEC, FCA and FSC Mauritius warning-list entries, and prices Raw accounts from $100 with spreads from 0.0 pips plus $3.50 per lot commission, but its support channels stop at email and chat for most entities. TrueBroker scores Eightcap 6.9 out of 10.
What we saw
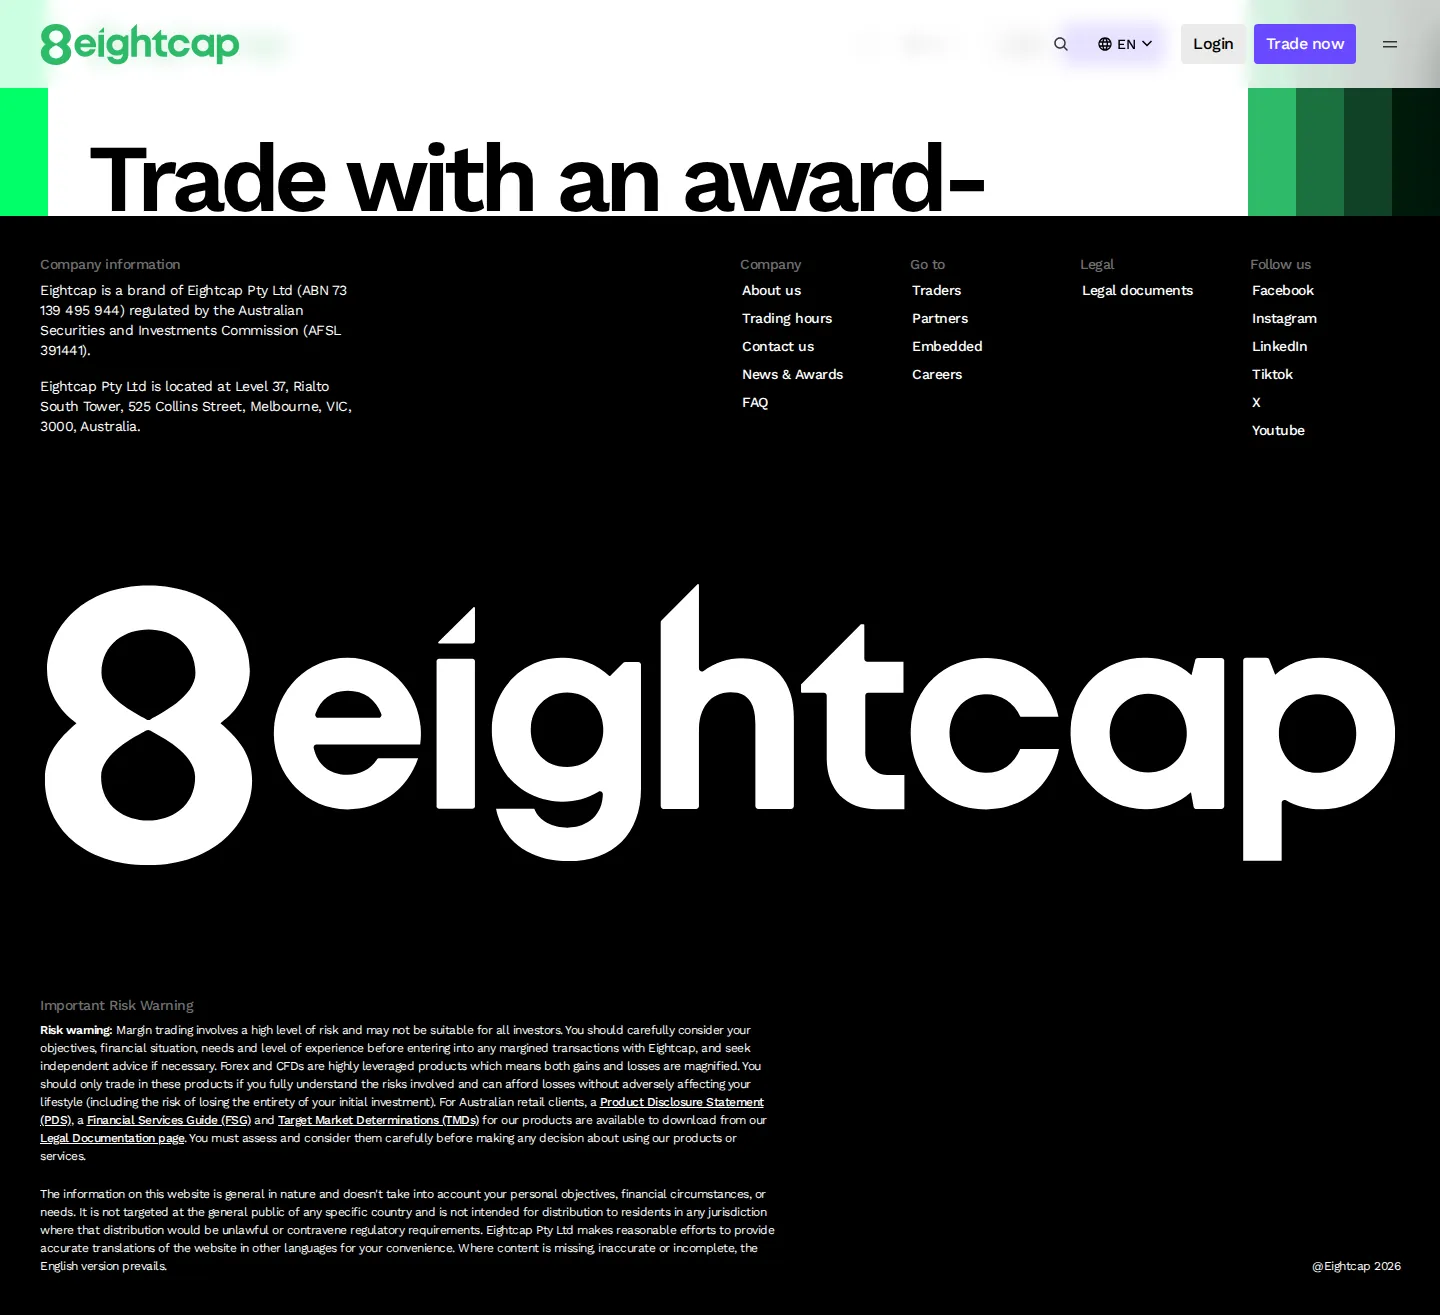
Pages captured from Eightcap’s own site when this review was written. Brokers change their terms; these are what we read.
Score history
Recomputed daily; every move is on the record. The current score is always the latest row.
| Date | Score | Move |
|---|---|---|
| 2026-09-29 | 6.9 | ▲ |
| 2026-07-25 | 6.5 | ▲ |
| 2026-07-18 | 6.4 | ▼ |
| 2026-07-11 | 6.6 | · |
FAQ
Is Eightcap regulated?
Yes, it holds confirmed licences from the FCA, ASIC and CySEC, plus the Seychelles FSA and Bahamas SCB; a Mauritius FSC licence is claimed but not verified.
What does Eightcap charge?
Raw account spreads start from USD 7 round turn per lot on EURUSD, with a minimum deposit of USD 100.
What trading platforms does Eightcap offer?
MetaTrader 4, MetaTrader 5, the MetaTrader web terminal, TradingView and TradeLocker.
Is client money protected at Eightcap?
Through its FCA-regulated entity, clients get compensation cover up to 85,000 GBP, an ombudsman, negative balance protection and a 30:1 leverage cap on major FX.
How good is Eightcap's customer support?
It scored the lowest of all criteria at 4.3/10, and which entity handles support and escalation depends on which one onboarded the client.
What do reviews say about Eightcap?
It has a blended rating of 4.09 stars across 3904 reviews.
How this review works
Track Eightcap live: score moves and red notices, in your pocket.