CFD · CHECKED 10 OCT 2026
Infinox review.
CFD broker holding an FCA licence, though retail clients trade via a Mauritius entity
OK-ISH
OUT OF 10
AD DISCLOSURE: IF YOU OPEN AN ACCOUNT THROUGH THIS LINK WE MAY EARN A COMMISSION. IT NEVER MOVES THE SCORE. HOW THIS WORKS
Infinox is a CFD broker holding an FCA licence in the UK and an FSC licence in Mauritius, but retail clients are onboarded through the Mauritius entity, not the FCA one. That entity's own onboarding notice says clients give up MiFID II level protections and rely on private Lloyd's insurance with a $20,000 retention instead of a statutory scheme.
Each criterion is scored 1 to 10 from primary sources. The overall score is their unweighted mean. How scoring works.
| Founded | 2009 |
|---|---|
| Minimum deposit | $1 |
| Maximum leverage | 1000:1 |
| Minimum spread | 0.2 |
| Withdrawal fee | 0 |
| Account opening | 1-3 |
| Platforms | MetaTrader 4 (MT4), MetaTrader 5 (MT5), IX Social, IX App |
- FCA licence 501057 confirmed on the register, held by Infinox Capital Ltd
- FSC Mauritius licence confirmed, Investment Dealer status, held by Infinox Limited
- Offers MetaTrader 4, MetaTrader 5, its own mobile app and IX App
- Copy trading available through IX Social
- Blended 4.25 stars across 1132 ratings
- Live chat and email support with published, round-the-clock hours
- FCA entity takes no retail clients, retail trading runs through the Mauritius entity
- Mauritius entity drops MiFID II level protections for retail clients
- Balance protection is private Lloyd's insurance with a $20,000 retention, not statutory
- CMA UAE licence number could not be matched on the register
- CMA UAE entity covers only marketing, no compensation scheme, no leverage cap
- Minimum deposit not published
Overview
TrueBroker is a free broker safety checker, and this page is our review of Infinox, scored 6.5 out of 10 across regulation, fees, platform, support and reviews.
Infinox is not one company but a group of separately regulated entities trading under the same brand. Infinox Capital Ltd is the FCA registered authorised entity, but the firm’s own account page states plainly that “INFINOX Capital Ltd does not offer trading services to retail clients,” restricting that entity to professional clients and institutions. Most retail traders are instead onboarded through INFINOX Limited in Mauritius, licensed by the Financial Services Commission there, or through the Anguilla company INFINOX Global Limited. A separate UAE entity, Infinox Financial Consultants L.L.C S.O.C, holds a Category 5 licence from the Capital Market Authority but functions as a marketing and introducing entity, not a dealer. A Cyprus company, INFINOX Services EU Limited, handles payment processing only.
Overview Table
| Headquarters | Not stated |
|---|---|
| Established | Infinox Capital Ltd incorporated 21 March 2009 (UK Companies House, company 06854853) |
| Countries Served | Not stated as a single list; the firm’s site disclaimer excludes residents of Afghanistan, Belgium, Canada, India and the United States, and its UK site separately excludes US and EU/EEA residents |
| Regulated By | Financial Conduct Authority (FCA), UK, FRN 501057; Financial Services Commission (Financial Services Commission), Mauritius; Capital Market Authority (Capital Market Authority), UAE |
| Minimum Deposit | Not stated in the firm’s own fetched pages (our earlier review reports $1 for the STP and ECN accounts) |
| Maximum Leverage | Up to 1:1000, described by the firm as “Dynamic Leverage” that scales down as notional exposure grows |
| Total Instruments | Not stated as a total count; the firm’s markets page lists 45+ currency pairs plus indices, commodities, stocks, cryptocurrencies and futures as CFD asset classes |
| Platforms | MetaTrader 4, MetaTrader 5, IX Social (copy trading), IX App (mobile) |
| Customer Support | Email, live chat, contact form |
| Languages | Not stated |
Facts List
- The FCA register confirms FRN 501057 is held by Infinox Capital Limited, status Authorised, effective 15/09/2009, Companies House number 06854853.
- Infinox Capital Ltd’s own account page states it “does not offer trading services to retail clients,” limiting the FCA authorised entity to professional and institutional clients.
- The FSC Mauritius Online Public Register confirms INFINOX Limited holds an SEC-2.1B Investment Dealer licence, licensed 19/11/2020; the register does not publish a licence number, so the quoted number GB20025832 is not confirmed by the register.
- The UAE Capital Market Authority (SCA) register lists Infinox Financial Consultants L.L.C S.O.C as CP-0001749, status Active; the register does not publish the licence number the firm quotes.
- “INFINOX” is not on the Securities Commission of The Bahamas registrant list as at 31 August 2026; an earlier, second hand review claims a Bahamas licence that does not appear on the firm’s own regulatory framework page.
- Companies House confirms Infinox Capital Limited as company 06854853, Private limited Company, incorporated 21 March 2009, status Active.
- The Cyprus Registrar of Companies confirms INFINOX Services EU Limited as HE 440832, registered 24/11/22, status Active; this entity handles payment processing, not client trading.
- We searched 1441 warning list entries mirrored from CYSEC, FCA and FSC Mauritius, and Infinox appears on none of them.
- The Mauritius entity’s entry disclaimer warns clients they will be outside the EU regulatory regime, MIFID II and will lose all protections granted under EU Regulations and Law.
- The firm’s account terms note that leverage, commission and stop/limit levels “may vary depending on entity, client profile and account setup.”
Which Infinox entity a client actually deals with
The regulatory picture that matters most is which entity signs up a given client, since protections differ sharply between them. A client who lands on the FCA authorised entity as a retail trader cannot actually open a trading account there. Retail flow goes instead to the Mauritius or Anguilla entities, where the firm’s own site tells clients that under FSC regulation it will provide only Best Execution, Segregated accounts, and Balance Protection, with no leverage caps or statutory compensation scheme mentioned on that page. Separately, we hold no register entry for the Anguilla company registry cited for INFINOX Global Limited (company number A000001246), so that filing has not been checked.
What Infinox charges and offers
Infinox’s own UAE account comparison page lists two core account types. The STP account carries spreads from 0.9 pips on FX majors and gold spreads from 15 cents, with commission from 0. The ECN account carries spreads from 0.2 pips on FX majors and gold spreads from 8 cents, with commission applying separately. Both list leverage up to 1:1000 and a minimum trade size from 0.01 lots. The firm’s fee page states there are no hidden fees on deposits or withdrawals from Infinox’s side, though independent bank or payment provider fees may still apply. Swap-free (Islamic) accounts are available subject to eligibility, but the firm’s own terms note that “admin fees may apply to certain Swap-Free / Islamic instruments” in place of standard swap charges. An earlier, second hand review gives different figures, a $1 minimum deposit and a $7 per lot round-turn commission on the ECN account, which this review reports only as what that earlier review found, not as something we confirmed on the firm’s current pages.
Platforms and execution conditions
Infinox offers MetaTrader 4 and MetaTrader 5, its IX Social copy trading platform, and the IX App for mobile account management including deposits, withdrawals and KYC verification. Stocks and ETFs are available on MT5 only. The firm’s own operational terms warn that “during extreme macro events or illiquid holiday sessions, Tier-1 liquidity providers may reduce market depth,” under which Infinox may temporarily adjust margin requirements or toggle specific assets to ‘Close Only’ to protect client capital, with no stated notice period. The same terms note that spreads “routinely widen immediately before and after” scheduled liquidity breaks, a cost not reflected in the advertised “spreads from” figures.
Capital protection
Infinox’s legal page describes an Excess of Loss Policy underwritten by Arch 2012 at Lloyd’s, covering eligible clients for net loss up to USD 500,000 per claimant, “subject to a USD 20,000 retention and policy limits,” payable only “in the unlikely case of an Insolvency Event.” This is private insolvency insurance rather than a statutory compensation scheme, and it does not cover the first USD 20,000 of any claim.
Key Takeaways
What decides the score
- Regulation lands at 4.8 because the FCA authorisation that headlines Infinox’s marketing does not cover the retail traders reading this review. Infinox Capital Ltd’s own UK page states plainly that the entity “does not offer trading services to retail clients”, only to professional clients or institutions.
- The FCA register itself confirms FRN 501057 as held by Infinox Capital Limited, status Authorised, effective 15/09/2009, Companies House number 06854853. That confirmation is real. It just does not reach the account most visitors would open.
- Retail clients are onboarded instead through INFINOX Limited in Mauritius, and the FSC Mauritius Online Public Register confirms that entity holds an SEC 2.1B Investment Dealer licence, licensed 19/11/2020 (the register publishes the licence type and date, not the number GB20025832 the firm quotes, so the company and permission are confirmed and the number is not). Entry to that entity comes with a pop up warning that clients will be outside the EU regulatory regime, MIFID II and will lose all protections granted under EU Regulations and Law, left with only Best Execution, Segregated accounts and Balance Protection under FSC rules.
- The UAE side of the business is licensed only as an introducer. The UAE Capital Market Authority (SCA) register lists INFINOX FINANCIAL CONSULTANTS L.L.C S.O.C as CP 0001749, status Active, listed since 2026, and the firm’s own material describes that entity as a marketing and introducing entity rather than a dealer.
- We searched the Securities Commission of The Bahamas registrant list as at 31 August 2026 and Infinox is not on it, a finding rather than a coverage gap since that list is the Commission’s full roll. The only source for a Bahamas licence is the earlier review we rewrote, and it is not backed by anything on the firm’s own “Global Regulatory Framework” page, which names only FCA, CMA and FSC.
- We checked Companies House and it confirms Infinox Capital Ltd as company 06854853, Private limited Company, incorporated 21 March 2009, status Active, a company record, not a licence. The Cyprus company registry (via the CyprusRegistry.com mirror) confirms INFINOX Services EU Limited as HE 440832, Limited Company, registered 24/11/22, status Active, but that entity handles payment processing only. We hold no register entry for Anguilla, so INFINOX Global Limited’s company number A000001246 has not been checked.
- Against the 1441 warning list entries mirrored from CySEC, the FCA and FSC Mauritius, Infinox matches none of them. That is a genuine clean result, though it only covers the three lists we mirror.
What Infinox charges
- Fees score 7.9. The firm’s own account comparison page lists an STP account with spreads from 0.9 pips on FX majors, gold spreads from 15 cents, commission from 0, leverage up to 1:1000 and a minimum trade size from 0.01 lots, alongside an ECN account with spreads from 0.2 pips on FX majors, gold spreads from 8 cents, and commission applying.
- The account specification note attached to that same page qualifies the headline numbers: the 1:1000 leverage is available “for initial tiers, scaling based on your total notional exposure,” and commission, leverage and stop and limit levels “may vary depending on entity, client profile and account setup.” The advertised ceiling applies to small positions and shrinks as exposure grows.
- The firm’s own fee page states no hidden fees on the Infinox side for deposits and withdrawals, while flagging that independent bank or payment provider network fees may still apply on top.
- The same page lists a wide funding stack: Visa and Mastercard cards with instant funding, USDT and USDC stablecoin deposits, and a set of local instant rails including Brazil Pix, Mexico SPEI, Portugal Pay by Bank, Singapore PayNow, Vietnam VietQR, Thailand PromptPay, Malaysia FPX, Indonesia QRIS, South Korea and Japan bank transfer, and a Gate to Pay e-wallet across several Middle East and North Africa markets. Nothing on that page mentions Skrill, Neteller or bank wire, the methods the earlier review reported, so that older list appears out of date.
- Swap free or Islamic accounts are marketed as avoiding interest based swap charges, but the firm’s own page notes that “admin fees may apply to certain Swap Free / Islamic instruments” in their place, with the amount not published.
- VPS hosting through 4XSolutions is available to clients who meet unspecified monthly volume requirements, with pricing not published and eligibility to be confirmed through support.
- Two contract terms carry real cost that will not show up in the “spreads from” line: spreads “routinely widen immediately before and after” scheduled liquidity breaks as pools reset, and short CFD positions held past the ex dividend date “incur a debit” while long positions receive a credit.
Platforms and markets
- Platform scores 7.7. Infinox runs MT4 on a hedging only order setup and MT5, which supports hedging and, depending on account setup, netting, plus stocks and ETFs, which the firm’s own page states are “Available on MT5 only.” Its own proprietary tools add IX Social for copy trading and the IX App for full account management, including deposits, withdrawals and KYC.
- The markets page advertises 45+ currency pairs with dynamic leverage up to 1:1000, plus indices, commodities, US and UK/Europe stocks, cryptocurrencies as a CFD instrument class on the account comparison table, and forex, index and commodity futures as CFDs. The earlier review’s figures of 49 pairs, 900+ instruments and no crypto class do not match what the firm currently publishes.
- The firm’s own operational terms state that during extreme macro events or illiquid holiday sessions, Infinox may temporarily adjust margin requirements or toggle specific assets to ‘Close Only’ with no stated notice period, a unilateral power worth weighing against the platform choice.
Support and the reviews score
- Support scores 4.8. The channels the firm publishes are an email address, support@infinox.com, a separate professional and institutional line, primesupport@infinox.co.uk, for the FCA regulated UK entity only, a live chat icon described as part of 24/7 operational support, and a “Send a Message” web form that requires a registered email and routes to a regional desk. There is no published phone line among these channels.
- Reviews sit at 7.1. Set against the clean warning list result, the discrepancies logged above (the unverified Bahamas licence, the prohibited country list that clashes with the firm’s dedicated Australia and Japan pages, the outdated payment methods and instrument counts, and two different registered addresses given for the same Anguilla company number across English and Indonesian locale pages) point to a firm whose own materials are not fully consistent from page to page.
What protects client money
- Beyond the FSC’s three stated protections, Infinox’s own capital protection page describes an Excess of Loss Policy underwritten by Arch 2012 at Lloyd’s, covering eligible clients for net loss up to USD 500,000 per claimant, “subject to a USD 20,000 retention and policy limits,” and payable only “in the unlikely case of an Insolvency Event.” That is private insolvency insurance bought by the firm, not a statutory scheme like the FSCS, and the first USD 20,000 of any claim falls outside it.
Licenses & Regulation
We searched six public registers directly for Infinox: the FCA, the FSC in Mauritius, the CMA in the UAE, the Securities Commission of The Bahamas, Companies House in the UK, and the Cyprus company registry. Before treating any absence as meaningful, we ran a positive control on each of those six, searching for a firm we already knew was listed, so that a blank result means the firm is not there rather than that our search failed.
The FCA licence Infinox advertises does not cover retail trading
The FCA register confirms FRN 501057 as held by Infinox Capital Limited, status Authorised, effective from 15/09/2009, and cross-referenced to Companies House number 06854853. That entry is real and current. But Infinox’s own UK account page states plainly that “Infinox Capital Ltd does not offer trading services to retail clients” and onboards only professional clients or institutions. A retail trader reading “FCA regulated” on Infinox’s marketing is being pointed at a licence that, by the firm’s own account page, does not apply to them.
Where retail clients actually land: Infinox Limited in Mauritius
Retail business runs instead through Infinox Limited, licensed by the Financial Services Commission (FSC) in Mauritius. The FSC’s Online Public Register confirms Infinox Limited holds an SEC-2.1B Investment Dealer (Full Service Dealer excluding Underwriting) licence, dated 19/11/2020. The register publishes the licence type and date but not a licence number, so the company and its permission are confirmed while the number Infinox quotes, GB20025832, is not something the register itself shows us. Infinox’s own Mauritius entry page carries a pop-up telling clients they will be outside the EU regulatory regime, MIFID II and will lose all protections granted under EU Regulations and Law, and lists only Best Execution, Segregated accounts, and Balance Protection as what the FSC licence provides in place of that. There is no leverage cap or statutory compensation scheme named on that page.
The UAE licence is for marketing, not dealing
The CMA (Securities and Commodities Authority) register lists Infinox Financial Consultants L.L.C S.O.C as CP-0001749, status Active, listed since 2026 on the SCA’s register of licensed companies. Infinox’s own UAE legal page describes this entity’s role as a marketing and introducing entity holding a Category 5 licence, not a dealing licence, and the number the firm quotes, 20200000379, is not the code the register itself shows. The register confirms the company; it does not confirm the licence number.
A regulator claimed for Infinox that its own pages do not name
An earlier published review credited Infinox with a Securities Commission of The Bahamas (SCB) licence. We searched the Commission’s Securities Industry Act registrant list, which is its complete roll of registrants, and “INFINOX” is not on it as at 31 August 2026. Infinox’s own “Global Regulatory Framework” page names only the FCA, the CMA, and the FSC. An absence from a complete registrant list is a finding, not a gap in our coverage, and here it lines up with what the firm’s own page already tells a reader.
Company registrations, which are not licences
Companies House confirms Infinox Capital Limited as UK company 06854853, a private limited company incorporated 21 March 2009, status Active. That is a company registration, not a financial licence, and it sits alongside the FCA number rather than adding to it. The Cyprus Registrar of Companies, via the CyprusRegistry.com mirror, confirms Infinox Services EU Limited as HE 440832, a limited company registered 24/11/22, status Active; Infinox’s own UAE account page describes this entity’s role as payment processing and support, not as a licensed dealer. INFINOX Global Limited is also named on Infinox’s UAE legal page as the Anguilla-incorporated company trading as INFINOX, company number A000001246, but we hold no register entry for an “Anguilla company registry” and have not checked that number. That is a gap in our directory rather than a finding about the firm.
What we found on the warning lists
We searched 1,441 warning-list entries mirrored from CySEC, the FCA, and the FSC Mauritius, and Infinox appears on none of them. That is a clean result on the lists we hold, and it covers only those three regulators’ mirrored lists, not every regulator worldwide.
What sits behind the licences if Infinox fails
Infinox’s own legal page describes an Excess of Loss Policy underwritten by Arch 2012 at Lloyd’s, covering eligible clients for net loss up to USD 500,000 per claimant, subject to a USD 20,000 retention, and payable only “in the unlikely case of an Insolvency Event.” This is private insolvency insurance arranged by the firm, not a statutory compensation scheme like the FSCS that the FCA licence might otherwise imply, and the first USD 20,000 of any claim sits with the client rather than the insurer.
How to Trade
Infinox splits trading across account types and platforms, and the account comparison table on the firm’s own accounts page is where the actual mechanics sit rather than in the marketing copy above it.
Accounts and pricing
Infinox’s accounts page lists two core account types. The STP Account is quoted with spreads from 0.9 pips on FX Majors, gold spreads from 15 cents, commission from 0, and leverage up to 1:1000, with a minimum trade size from 0.01 lots. The ECN Account is quoted with spreads from 0.2 pips on FX Majors, gold spreads from 8 cents, commission applying on top of the tighter spread, and the same leverage ceiling and minimum trade size. Both are offered on MT4 and MT5 and both list Swap-Free/Islamic variants as available “subject to eligibility.”
The accounts page carries an “Important Specification Note” stating that commission, leverage, and stop/limit levels “may vary depending on entity, client profile and account setup.” That means the numbers on the comparison table are a starting point rather than a fixed schedule, and what a given trader actually gets depends on which Infinox entity onboarded them.
Leverage is not a flat number
The same accounts page describes leverage as Dynamic Leverage: Up to 1:1000 available for initial tiers, scaling based on your total notional exposure. Read plainly, the 1:1000 figure applies to small positions only, and the ratio comes down automatically as a trader’s notional exposure grows. Anyone opening an account on the strength of the “1:1000” headline should expect that ceiling to shrink once a position gets larger, not to hold across the account.
Execution conditions Infinox reserves the right to change
The accounts page, under “Operational & Execution Parameters,” states that “during extreme macro events or illiquid holiday sessions, Tier-1 liquidity providers may reduce market depth” and that under those conditions INFINOX may temporarily adjust margin requirements or toggle specific assets to ‘Close Only’ to protect client capital. In plain terms, Infinox can raise margin requirements or block new positions on a given instrument during volatile periods, and the page does not state a notice period for when this happens.
The same section also warns that spreads “routinely widen immediately before and after” scheduled liquidity breaks “as liquidity pools reset.” That widening is not captured in the “spreads from” figures quoted on the account comparison table, so the advertised minimums apply to normal trading conditions rather than around those scheduled pauses.
Costs that sit outside the spread
Infinox’s accounts page states that for CFD corporate actions, “open long positions receive a proportional credit, while open short positions incur a debit if held past the ex-dividend date.” Anyone running a short CFD position on a dividend-paying stock through a dividend date will see that debit taken from their account balance.
On Swap-Free/Islamic accounts, marketed as avoiding interest-based swap charges, the same page notes that “admin fees may apply to certain Swap-Free / Islamic instruments” and that “standard administrative holding fees may apply.” The page does not publish an amount for this, so a swap-free account holder can still be billed a holding fee in place of the swap charge it’s meant to replace.
What Infinox trades and where
Infinox’s markets page advertises 45+ currency pairs with dynamic leverage up to 1:1000, alongside indices (UK & Europe, US, and Global), commodities (precious metals, energy, agricultural), stocks (US and UK & Europe), and futures (index, commodity, and forex futures as CFDs). The account comparison table also lists cryptocurrencies, covering major coins and altcoins, as a tradable CFD class. Stocks and ETFs, per the accounts page, are “Available on MT5 only,” so a trader on MT4 does not get access to that instrument set.
Platforms
MT4 on Infinox is described as hedging-only in its order management. MT5 supports hedging and, depending on account setup, netting, and is the only platform carrying stocks and ETFs. Beyond the two MetaTrader platforms, Infinox runs IX Social, a proprietary copy-trading platform for auto-copying trades from selected strategy providers, and the IX App, a mobile-first app the firm describes as handling full account management including direct trading, deposits, withdrawals, and KYC verification.
Which Infinox entity actually executes the trade
The FCA register confirms FRN 501057 is held by Infinox Capital Limited, authorised, and the firm’s own UK accounts page states plainly that this FCA-regulated entity “does not offer trading services to retail clients” and onboards only professional clients or institutions. Retail traders reading the “FCA-regulated” claim are, by the firm’s own words, not the clients that entity actually serves; retail flow runs through other entities in the group, such as the Mauritius-licensed INFINOX Limited, which the FSC Mauritius register confirms holds a SEC-2.1B Investment Dealer licence. Infinox’s own site entry disclaimer for that Mauritius entity warns that clients onboarding there are outside the EU regulatory regime, MIFID II and will lose all protections granted under EU Regulations and Law, with only Best Execution, Segregated accounts, and Balance Protection stated as the protections that apply instead.
Account Types
Infinox sells two account types on its own comparison table: an STP account and an ECN account. The firm’s account-types page gives the STP account spreads “from 0.9 pips” on FX majors, gold spreads from 15 cents, commission “from 0”, leverage up to 1:1000, and a minimum trade size from 0.01 lots. The ECN account on the same page carries tighter spreads, “from 0.2 pips” on FX majors and gold from 8 cents, but commission applies rather than being folded into the spread, with the same 1:1000 leverage ceiling and 0.01-lot minimum. Both run on MT4 and MT5 and both list Swap-Free/Islamic trading as available “subject to eligibility”. The page does not state a minimum deposit for either account.
An earlier review of Infinox that this write-up draws on for comparison reported a $1 minimum deposit on both accounts and put the ECN commission at $7 per standard lot round turn. Those figures did not come from a page we fetched ourselves, so they are reported here as what that earlier review found, not as something Infinox’s own account page currently states.
What the 1:1000 leverage figure actually means
The headline leverage number on Infinox’s account page comes with a qualifier most traders will not read past the table. Under “Trading Accounts – Important Specification Note”, the page describes Dynamic Leverage as “up to 1:1000 available for initial tiers, scaling based on your total notional exposure”, and adds that commission, leverage, and stop or limit levels “may vary depending on entity, client profile and account setup”. In plain terms, 1:1000 is a ceiling for small positions that reduces automatically as exposure grows, and the exact terms a given client gets depend on which Infinox entity signed them up.
Which Infinox entity is actually opening the account
That last point matters because Infinox is not one regulated firm but several. Infinox Capital Ltd, the entity holding FCA authorisation (FRN 501057, confirmed on the FCA register), states on its own page that it “does not offer trading services to retail clients” and takes on professional clients or institutions only. Retail applicants land instead with entities such as INFINOX Limited in Mauritius, where the FSC Mauritius register confirms the company holds an SEC-2.1B Investment Dealer licence, or with the Anguilla-incorporated INFINOX Global Limited. The entry pop-up shown to clients onboarding through the Mauritius route warns them directly: You will be outside the EU regulatory regime, MIFID II. Therefore you will lose all protections granted under EU Regulations and Law. Under FSC regulation, the same page says Infinox will provide only Best Execution, Segregated accounts, and Balance Protection, with no leverage cap or statutory compensation scheme named alongside those three.
Swap-free accounts and other costs baked into the account, not the spread
The Swap-Free (Islamic) option on either account is marketed as removing interest-based swap charges, but the same account page notes under Trading Accounts, Swap-Free (Islamic) Capabilities that “admin fees may apply to certain Swap-Free / Islamic instruments”, with standard administrative holding fees substituted for the swap charge on some instruments. The published fee material does not say what that admin fee is, so a Swap-Free client cannot price it in advance from what Infinox has published.
Clients trading equity CFDs on either account should also weigh the corporate-actions handling set out under “Operational & Execution Parameters”: “Open long positions receive a proportional credit, while open short positions incur a debit if held past the ex-dividend date.” A short stock CFD position carried over a dividend date is charged, not credited. The same section notes that spreads “routinely widen immediately before and after” scheduled liquidity breaks, a cost that sits outside the “spreads from” figures quoted on the account table.
What sits behind the account beyond the spread
Account holders who qualify get access to MT4, which the firm runs in hedging-only order mode, and MT5, which supports netting as well as hedging and is the only platform where the stocks and ETFs on Infinox’s instrument list can be traded. Clients meeting an unspecified monthly volume requirement can also request VPS hosting through 4XSolutions, though Infinox does not publish the volume threshold or the hosting cost; eligibility has to be checked with support directly. Separately from the account terms, Infinox’s “Capital Protection & Asset Security” page describes an Excess of Loss Policy underwritten by Arch 2012 at Lloyd’s, covering eligible clients for a net loss of up to USD 500,000 per claimant, “subject to a USD 20,000 retention and policy limits”, and payable only “in the unlikely case of an Insolvency Event”. That is private insolvency insurance sitting behind the account, not a statutory compensation scheme, and the first USD 20,000 of any claim is not covered by it.
Negative Balance Protection
Infinox’s published pages do carry sections titled “Negative Balance Protection,” which state: “We enforce negative balance protection for all retail clients, ensuring you never lose more than your total deposited capital.” Beyond those sections, what we found sits scattered across the site’s entry disclaimer, its account specification notes, and its capital-protection page, and none of that additional material amounts to a plain statement of a stop-out percentage.
The “Balance Protection” line on Infinox’s Mauritius entry screen
The pop-up shown to visitors entering the Mauritius-regulated site warns that you will be outside the EU regulatory regime, MIFID II and that they will lose all protections granted under EU Regulations and Law. In the same breath it states that under FSC regulation the firm provides only three things: Best Execution, Segregated accounts, and Balance Protection. That third item is the closest thing to a negative-balance commitment in the evidence, but the pop-up names it without defining it, so the pages we fetched do not say what threshold triggers it, whether it applies per-position or per-account, or whether any client category is excluded.
What the Lloyd’s policy actually covers
Infinox’s capital-protection page describes an Excess of Loss Policy underwritten by Arch 2012 at Lloyd’s, covering eligible clients for net loss up to USD 500,000 per claimant, “subject to a USD 20,000 retention and policy limits,” and payable only “in the unlikely case of an Insolvency Event.” That is insurance against Infinox itself going insolvent, not a mechanism for closing out a losing trade before a client’s balance turns negative, and the first USD 20,000 of any claim under it is not covered at all. It is worth keeping separate from “Balance Protection” on the entry pop-up, since the two are different things doing different jobs, and the firm’s page describes only the insolvency policy in detail.
Margin and close-only powers during volatile markets
The account specification notes for the UAE-facing site describe what happens when liquidity thins out: During extreme macro events or illiquid holiday sessions, Tier-1 liquidity providers may reduce market depth. Under these conditions, INFINOX may temporarily adjust margin requirements or toggle specific assets to ‘Close Only’ to protect client capital. That gives Infinox the right to raise margin requirements or block new positions on an instrument during a volatile stretch, with no notice period stated on the page. The same notes warn that “spreads routinely widen immediately before and after” scheduled liquidity breaks, a cost that sits outside the advertised “spreads from” figures and can eat into margin faster than those headline numbers suggest.
Leverage that shrinks as exposure grows
The same account page describes Infinox’s leverage as dynamic: “Up to 1:1000 available for initial tiers, scaling based on your total notional exposure,” with commission, leverage and stop/limit levels stated to “vary depending on entity, client profile and account setup.” In practice this means the 1:1000 figure used in the account tables is a ceiling for small positions, and it steps down automatically as a trader’s total exposure rises, which functions as a drawdown limiter of sorts even though the page does not publish the tiers themselves or the exposure thresholds at which they change.
Which entity a client actually lands on matters here
The FCA-authorised entity, Infinox Capital Ltd, states on its own page that it “does not offer trading services to retail clients” and onboards only professional clients or institutions. Retail traders are instead routed to the Mauritius entity (FSC-licensed) or the Anguilla company, both of which sit behind the entry pop-up quoted above. That matters for a section on loss limits because whatever balance protection exists is described as an FSC-regulation feature on the entry screen a retail client sees, not as an FCA one, and the FCA-regulated entity a client might assume is protecting them is not the one taking their trades.
Short positions and corporate actions
Infinox’s account terms also note a mechanic that can push a balance the wrong way independent of price movement: “Open long positions receive a proportional credit, while open short positions incur a debit if held past the ex-dividend date.” A client short a stock CFD over an ex-dividend date is charged a debit against their account balance under this clause, which is a direct balance deduction the account comparison pages do not flag alongside their headline spread and commission figures.
Trading Instruments
INFINOX’s own account comparison table, fetched from its UAE-locale accounts page, lists the same instrument access for both its STP and ECN account types; the split it draws is by platform, not by account. Forex, indices, commodities and CFD futures trade on both MT4 and MT5, but the firm’s page states stocks and ETFs are “Available on MT5 only.” A client who opens on MT4, whether by habit or by whichever entity onboarded them, cannot reach the equity CFDs the marketing shows elsewhere.
What Infinox lists as tradable
The markets page advertises 45+ currency pairs under Dynamic Leverage up to 1:1000. Beyond forex, the accounts page groups the rest as indices (UK & Europe Indices, US Indices, Global Indices), commodities (Precious Metals, Energy, Agricultural Commodities), stocks (US Stocks, UK & Europe Stocks), a cryptocurrency line described only as “Major Coins, Altcoins,” and index, commodity and forex futures, all traded as CFDs. Nothing in the evidence fetched from Infinox’s own pages gives a coin count or names individual tokens.
That current instrument list does not match what the earlier published review reported: 900+ instruments overall and no cryptocurrency class at all. Infinox’s own markets page now includes crypto, so the aggregator’s figures look out of date rather than wrong at the time they were written.
The leverage ceiling is not what it looks like
The 1:1000 figure that headlines the forex and account pages carries a qualifier on the same accounts page: Dynamic Leverage is “up to 1:1000 available for initial tiers, scaling based on your total notional exposure,” and the page adds that commission, leverage, and stop/limit levels “may vary depending on entity, client profile and account setup.” Read plainly, the advertised ratio applies to small positions and steps down as a trader’s exposure grows, and the exact terms depend on which Infinox entity did the onboarding.
Two account types sit on top of that leverage structure. Infinox’s own page puts forex-major spreads on the STP account from 0.9 pips and Gold from 15 cents, with commission from 0, against ECN spreads from 0.2 pips and Gold from 8 cents, with commission applying on top. Both quote a minimum trade size from 0.01 lots and both list Swap-Free/Islamic variants “subject to eligibility.” The earlier review’s version of the same two accounts adds figures Infinox’s own page does not carry in the evidence gathered here: a $1 minimum deposit for both, and a $7 per standard lot round-turn commission on the ECN account. Those numbers come from our earlier review, not from a page fetched for this write-up.
Conditions that change what “tradable” means in practice
Infinox’s own operational-parameters page describes several conditions that sit between the advertised instrument list and what a position actually costs or whether it can be opened at all. During “extreme macro events or illiquid holiday sessions,” the page states that Tier-1 liquidity providers may reduce market depth, and that Infinox may temporarily adjust margin requirements or toggle specific assets to ‘Close Only’ to protect client capital, with no notice period given. The same page warns that spreads “routinely widen immediately before and after” scheduled liquidity breaks as liquidity pools reset, a cost the “spreads from” figures elsewhere do not reflect.
Equity CFDs carry a further mechanic tied to corporate actions: the page states that open long positions “receive a proportional credit, while open short positions incur a debit if held past the ex-dividend date.” A client short a stock CFD over that date is charged, not credited, and the account pages give no schedule of which names or dates this applies to.
Swap-Free accounts get a similar caveat. They’re marketed as avoiding interest-based swap charges, but the same accounts page notes that “admin fees may apply to certain Swap-Free / Islamic instruments” and that “standard administrative holding fees may apply” in their place. Neither the size of that fee nor the list of instruments it applies to is published in what was fetched.
Which entity actually fills the order
The instrument range above is what appears on Infinox’s account and markets pages generally, but which entity a client trades through is not uniform. Infinox Capital Ltd, the FCA-authorised entity (FRN 501057, confirmed on the FCA register), states on its own page that it “does not offer trading services to retail clients,” restricting itself to professional clients and institutions. Retail access to the instrument list above runs instead through INFINOX Limited under its Mauritius FSC licence (confirmed on the FSC Mauritius register as an Investment Dealer) or through the Anguilla-incorporated INFINOX Global Limited, and the site’s entry disclaimer for the Mauritius route warns that clients will be outside the EU regulatory regime, MIFID II and will lose all protections granted under EU Regulations and Law. The breadth of instruments on offer sits on top of that regulatory split, and which protections apply to a given trade depends on which entity booked it.
Education & Analysis
The account comparison table on INFINOX’s own accounts page splits trading into two platforms, MetaTrader 4 and MetaTrader 5, and both come with a specification note worth reading before signing up for either. MT4 runs hedging-only order management on INFINOX. MT5 supports hedging and, depending on account setup, netting, and it is the only one of the two that carries stocks and ETFs; anyone who wants to trade US or UK/Europe shares as CFDs has to be on MT5, not MT4.
Both the STP and ECN accounts on the firm’s accounts page list MT4/MT5 as the trading platform, with no charting package, proprietary desktop terminal, or third-party analysis suite named anywhere in that table. What INFINOX adds on top of the two MetaTrader builds are two of its own apps, described on its platforms page: IX Social, a copy-trading platform that auto-copies trades from selected strategy providers, and the IX App, described as a mobile-first app that handles direct trading, deposits, withdrawals and KYC verification in one place. Neither is described as a charting or technical-analysis tool in the evidence we hold; both are account-management and copy-trading layers sitting alongside MT4/MT5 rather than a alternative to them.
What Infinox’s own specification note says about execution
The accounts page carries an “Operational & Execution Parameters” note that matters for anyone charting entries around news or session opens. It warns that “during extreme macro events or illiquid holiday sessions, Tier-1 liquidity providers may reduce market depth” and that under those conditions INFINOX may temporarily adjust margin requirements or toggle specific assets to ‘Close Only’ to protect client capital. The same note states that “spreads routinely widen immediately before and after these breaks as liquidity pools reset,” referring to scheduled liquidity breaks. Neither the margin adjustment nor the spread widening is quantified on the page, and both fall outside the “spreads from” figures quoted elsewhere on the same accounts page for the STP and ECN tiers.
The same page also flags that commission, leverage and stop/limit levels “may vary depending on entity, client profile and account setup,” and that the advertised 1:1000 Dynamic Leverage is, in the firm’s own words, “up to 1:1000 available for initial tiers, scaling based on your total notional exposure.” A trader building a position size or stop-loss plan on a charting platform against a stated 1:1000 figure is working against a ceiling that shrinks as exposure grows, not a fixed ratio, and the exact terms depend on which INFINOX entity onboarded the client.
Instruments available to chart and trade
INFINOX’s own markets page lists 45+ currency pairs under Forex with Dynamic Leverage up to 1:1000, and the accounts page adds Indices (UK & Europe, US, Global), Commodities (Precious Metals, Energy, Agricultural), Stocks (US, UK & Europe, MT5 only), Cryptocurrencies (listed on the account comparison table as “Major Coins, Altcoins”) and Futures (Index, Commodity, Forex, as CFDs). An earlier review of this firm had put the count at 49 forex pairs and 900+ instruments with no cryptocurrency asset class at all; the firm’s own current markets and accounts pages contradict both of those figures, giving 45+ pairs and listing crypto as a tradable CFD class, which points to that earlier figure being out of date rather than to anything wrong with the current pages.
One further mechanical detail affects anyone charting short positions around dividend dates: the accounts page states that for equity CFDs, “open long positions receive a proportional credit, while open short positions incur a debit if held past the ex-dividend date.” A short position held into that date is charged a debit taken from the account balance, a cost that a chart of the underlying price alone would not show.
Beyond MT4 and MT5, IX Social and the IX App, we hold no evidence of a VPS offering’s terms beyond its existence: INFINOX’s markets page mentions VPS hosting through 4XSolutions as available to clients who meet unspecified monthly volume requirements, with pricing not published and eligibility to be confirmed by contacting support directly.
Special Offers
We went into this section looking for deposit bonuses, cashback offers, refer-a-friend credit, the usual toolkit of broker promotions. The pages we fetched for Infinox don’t have one. What follows is what those pages actually describe instead of what a promotions page would have shown.
What Infinox’s own pricing pages describe
The account comparison page lists two account types, STP and ECN, both priced through spreads, with commission applying on the ECN account: STP spreads “from 0.9 pips” on FX majors with commission from 0, ECN spreads “from 0.2 pips” on FX majors with commission applied separately. Neither entry mentions a deposit match, a welcome credit, or any promotional rate tied to opening an account. The fee page we checked states Infinox itself charges no hidden fees on deposits or withdrawals, while noting that the client’s own bank or payment provider may still apply its own charges on top. That’s a fee disclosure, not an offer.
The one volume-linked perk we found: VPS hosting
The closest thing to a loyalty benefit in the material we fetched is VPS hosting through a provider called 4XSolutions, listed on Infinox’s markets page. The price isn’t published. Eligibility is described only as clients who meet unspecified monthly volume requirements, and a trader has to contact support directly to find out whether they qualify. That’s a real perk if a client trades enough volume to reach it, but it isn’t advertised with a threshold, a duration, or terms a reader could check in advance, and Infinox’s own page doesn’t say what happens to the perk if volume drops below whatever the unstated bar is.
Swap-free accounts come with a catch worth flagging here
Infinox’s account page offers Swap-Free (Islamic) trading on both the STP and ECN accounts, subject to eligibility. Accounts marketed as swap-free are often positioned as a standing offer to clients who can’t hold interest-bearing positions. Infinox’s own accounts page qualifies it: “admin fees may apply to certain Swap-Free / Islamic instruments” in place of the standard swap charge, and elsewhere on the same page, “standard administrative holding fees may apply.” Neither the rate nor the list of affected instruments is published on the page we read, so a client signing up for the swap-free label should expect to ask what, if anything, replaces the swap charge on the specific instrument they trade.
Dynamic leverage isn’t a promotional rate either
The same account page advertises leverage “up to 1:1000,” which on some broker sites is dressed up as a promotional tier. Infinox’s own page rules that out directly: the 1:1000 figure is described as “available for initial tiers, scaling based on your total notional exposure,” and the page adds that commission, leverage, and stop/limit levels “may vary depending on entity, client profile and account setup.” That’s a structural ceiling that shrinks as a position grows, not a limited-time or promotional rate, and it depends on which Infinox entity actually onboards the client.
What we didn’t find
Nothing in the fee page, the account comparison page, the markets page, or the legal page names a bonus scheme, a deposit-matching offer, a cashback program, or a referral incentive. That reflects the pages we fetched, not a search of every page Infinox publishes or every jurisdiction it operates in, so it should be read as the material we reviewed doesn’t describe one, not as a finding that no such program exists anywhere on the firm’s site.
Opening an Account
Infinox trades under several legal entities, and which one actually opens an account matters more than the marketing page a prospective client lands on.
Which Infinox entity actually opens the account
Infinox Capital Ltd’s own UK accounts page states plainly that this FCA-authorised entity “does not offer trading services to retail clients” and onboards only professional clients or institutions. A retail applicant is therefore not opening an account with the entity the FCA record (FRN 501057, Authorised, effective 15/09/2009) actually covers. In the UAE, Infinox Financial Consultants L.L.C S.O.C holds the CMA Category 5 licence as a marketing and introducing entity rather than a dealer, and INFINOX Services EU Limited in Cyprus is described as a payment services provider handling payment processing and support, not as the counterparty taking the trade. That leaves INFINOX Limited, the Mauritius-licensed Investment Dealer, as the entity that appears to actually book retail business. Anyone opening an account should check, at sign-up, which of these entities is named on the account-opening agreement, since the protections attached differ by entity.
The site’s Mauritius entry pop-up warns applicants that continuing means leaving the EU regulatory regime under MIFID II and losing the protections granted under EU regulations and law. Under FSC regulation the firm states it provides only Best Execution, Segregated accounts, and Balance Protection to clients who continue past that pop-up. Separately, the firm’s Capital Protection page describes an Excess of Loss Policy underwritten by Arch 2012 at Lloyd’s, covering net loss up to USD 500,000 per claimant “subject to a USD 20,000 retention and policy limits,” and payable only “in the unlikely case of an Insolvency Event.” That is private insolvency insurance with a USD 20,000 excess, not a statutory scheme like the FSCS, and it only pays if Infinox itself goes under.
Who Infinox will not onboard
The firm’s own site-entry disclaimer states its information is not intended for residents of Afghanistan, Belgium, Canada, India, or the United States, or any jurisdiction where distribution or use would be unlawful. The UK-facing infinox.co.uk site separately states its content is not directed at residents of the United States, the EU/EEA, or any country outside the UK. Applicants using that UK site who are not professional clients or institutions are excluded outright, per the retail-services statement above.
We’d flag one inconsistency here rather than resolve it: an earlier review of Infinox listed a different prohibited-country set (United States, Canada, Japan, Australia, New Zealand, Belgium), but Infinox runs dedicated, geo-targeted pages for both Australia and Japan, which sits awkwardly next to a claim that residents of those countries are barred. We can’t reconcile the two lists from what we fetched, so we’re reporting both rather than picking one.
Account types on offer at sign-up
Infinox’s own UAE account-comparison page lists two core account types available through MT4 and MT5: an STP Account, with spreads from 0.9 pips on FX majors, gold spreads from 15 cents, commission from 0, and leverage up to 1:1000; and an ECN Account, with spreads from 0.2 pips on FX majors, gold spreads from 8 cents, a commission structure, and the same leverage ceiling. An earlier review of Infinox reported a $1 minimum deposit for both account types and put the ECN commission at $7 per standard lot round turn; we did not find either the minimum deposit figure or that specific commission number on the pages we fetched, so those two figures should be read as the earlier review’s figures rather than Infinox’s own current wording.
The account page itself carries an “Important Specification Note” that the advertised 1:1000 leverage is “available for initial tiers, scaling based on your total notional exposure,” and that commission, leverage and stop/limit levels “may vary depending on entity, client profile and account setup.” In practice, the leverage and cost terms a new client actually gets depend on which entity signs them up and how large their positions grow, not solely on the account type chosen at opening.
Verification and platform access
Infinox’s own platforms page describes the IX App as a proprietary mobile-first app with full account management: direct trading, deposits, withdrawals, KYC verification, which places identity verification inside the same app used for funding and trading rather than as a separate onboarding step. Beyond naming KYC verification as a function of the app, the pages we fetched do not itemise which documents or checks that verification involves, so we can’t say more about the specific proof-of-identity or proof-of-address requirements than that KYC exists as a step within the app.
Swap-Free (Islamic) account status is described as “available subject to eligibility” on both the STP and ECN account types, and the firm’s own accounts page notes that “admin fees may apply to certain Swap-Free / Islamic instruments” in place of standard swap charges, so an applicant requesting swap-free terms is not guaranteed the standard swap-free treatment across every instrument they trade.
One further point worth flagging for anyone opening an account through the Anguilla entity, INFINOX Global Limited (company number A000001246): the registered office address given for that company differs between locales, reading “Victoria House, The Valley, A-12640” on the English-language pages and “No. 9 Cassius Webster Building, Grace Complex, PO Box 1330, The Valley, AI-2640” on the Indonesian-locale pages. We hold no register entry for an “Anguilla company registry” against which to check either address, so neither figure is independently confirmed.
Deposits & Withdrawals
INFINOX’s own fee page states that the firm itself charges no hidden fees on deposits or withdrawals, though it flags that independent bank and payment-provider fees may still apply on top of that.
What Infinox charges to move money
The Australia-region fee page lists a set of funding rails: Visa and Mastercard for instant card funding, USDT and USDC stablecoin crypto deposits, and a run of local instant-payment methods aimed at specific markets, Brazil’s Pix, Mexico’s SPEI, Portugal’s Pay by Bank, Singapore’s PayNow, Vietnam’s VietQR, Thailand’s PromptPay, Malaysia’s FPX, Indonesia’s QRIS, bank transfer in South Korea and Japan, and a Gate to Pay e-wallet covering the UAE, Saudi Arabia, Qatar, Oman, Bahrain, Jordan, Egypt, Morocco and Tunisia. That page does not carry a fee schedule beyond the “no hidden fees” statement, so what a client sees at the point of transfer, and whatever their own bank charges for the transfer itself, is not something we hold evidence for.
Worth flagging: an earlier published review of this firm listed Skrill, Neteller and bank wire transfer as funding methods, with no mention of the rails above. INFINOX’s own current funding page names cards, stablecoin crypto and the local instant-payment methods listed above, and does not mention Skrill, Neteller or bank wire at all. The two accounts describe different payment stacks, so the list from our earlier review looks out of date against what the firm currently publishes.
Costs that sit next to deposits and withdrawals without being labelled as such
The account comparison page describes a Swap-Free (Islamic) option available on both the STP and ECN accounts, subject to eligibility, and states that “standard administrative holding fees may apply” in place of the standard swap charge. No figure is published; a client on a swap-free account would need to check with the firm directly what, if anything, gets deducted in place of overnight swaps.
Separately, the same account page’s execution notes cover a corporate-actions clause for CFDs: open long positions get a proportional credit around a dividend date, while open short positions “incur a debit if held past the ex-dividend date.” That debit is taken from account balance rather than charged as a transaction fee, but it reduces what a short-holding client keeps in exactly the same way a withdrawal fee would, and it will not show up on any funding page.
Capital protection if the firm fails
The legal page describes an Excess of Loss policy underwritten by Arch 2012 at Lloyd’s, covering eligible clients for net loss up to USD 500,000 per claimant, “subject to a USD 20,000 retention and policy limits,” and payable only “in the unlikely case of an Insolvency Event.” This is private insolvency insurance arranged commercially through Lloyd’s, not a statutory compensation scheme like the FSCS or an investor compensation fund tied to a specific licence, and the first USD 20,000 of any claim sits with the client rather than the insurer. Whether this policy applies to a given client’s funds depends on which INFINOX entity holds their account, since the page does not tie the policy to a specific licensed entity.
That distinction matters for withdrawal risk specifically because of how the group is structured. Infinox Capital Ltd, the entity holding FCA authorisation (FRN 501057, confirmed on the FCA register), states on its own accounts page that it “does not offer trading services to retail clients,” onboarding only professional clients or institutions. Retail clients are, by the firm’s own Mauritius-entry disclaimer, routed instead to INFINOX Limited under the FSC Mauritius licence (confirmed on the FSC Mauritius Online Public Register, though the register publishes the licence type and date without the number the firm quotes), where the entry pop-up warns clients they will be outside the EU regulatory regime, MIFID II and will lose all protections granted under EU Regulations and Law, stating only three protections under FSC rules: Best Execution, Segregated accounts, and Balance Protection. A retail client’s deposit and withdrawal terms, and whatever compensation route applies if something goes wrong, run through the Mauritius entity’s weaker protections rather than the FCA entity whose authorisation is what typically builds trust in this brand.
Cyprus entity handles payments, not dealing
INFINOX Services EU Limited, registered in Cyprus as company HE 440832 (confirmed on the Cyprus Registrar of Companies via the CyprusRegistry.com mirror, incorporated 24/11/22, status Active), is described on the firm’s own accounts page as a payment services provider handling payment processing and support only. It is not a licensed dealer and carries no financial licence of its own in the evidence we hold; its role in the deposit and withdrawal chain is limited to processing, with the actual trading relationship sitting with whichever regulated or introducing entity onboarded the client.
What the warning-list check found
We searched 1,441 warning-list entries mirrored from CySEC, the FCA and FSC Mauritius, and Infinox does not appear on any of them. That check covers only the three regulators we mirror, not every regulator globally, but it is a clean result on the lists we hold.
Customer Support
Infinox lists four ways to reach it, and the register work above already narrows who each one is actually for. The firm’s contact page names a general support inbox, a live chat icon, and a web contact form; the FCA-regulated UK entity runs a separate address reserved for a different class of client entirely. The detail worth reading is not the list of channels but what each one will and won’t do for a client who has a problem.
How to reach Infinox
- Email: support@infinox.com, the general address given on the firm’s contact page.
- Live chat: an icon in the bottom right corner of the site, which the contact page describes as part of 24/7 operational support.
- Contact form: a “Send a Message” web form that requires a registered email address, which the contact page says is routed internally to a regional desk.
- Email for professional/institutional clients only: primesupport@infinox.co.uk, published on the account page for Infinox Capital Ltd, the FCA-regulated UK entity.
Who actually answers a retail complaint
The FCA registration that gives Infinox its headline regulatory credibility does not cover retail support at all. Infinox Capital Ltd’s own account page states plainly that it “does not offer trading services to retail clients,” and the primesupport@infinox.co.uk address on that page is for professional clients or institutions only. A retail trader is instead onboarded through the Mauritius entity, INFINOX Limited, or the Anguilla-incorporated INFINOX Global Limited, and the entry pop-up on the firm’s site tells that client outright: continuing means going outside the EU regulatory regime, MIFID II and that they will lose all protections granted under EU Regulations and Law. Under FSC regulation, the same page states the firm provides only Best Execution, Segregated accounts, and Balance Protection. So a retail client with a complaint is dealing with the entity that offers three named protections, not the FCA one, and the general support@infinox.com inbox rather than any UK-specific escalation route we found published.
What backs a complaint if Infinox can’t pay
The one financial backstop the firm’s own legal page describes is private insurance, not a statutory compensation scheme. It names an Excess of Loss Policy underwritten by Arch 2012 at Lloyd’s, covering eligible clients for net loss up to USD 500,000 per claimant, “subject to a USD 20,000 retention and policy limits,” and payable only “in the unlikely case of an Insolvency Event.” That means the policy does not pay out for a trading dispute or an execution complaint, only if Infinox itself goes insolvent, and the first USD 20,000 of any claim is not covered at all. We found no mention on the pages we fetched of a statutory scheme such as the UK’s FSCS or a Cyprus-style investor compensation fund attaching to the entity that actually serves retail clients.
Terms that shape what a complaint is actually about
Several clauses in the material we read give Infinox discretion that a client would need to invoke support to dispute in the first place. Under “Operational & Execution Parameters,” the firm states that during extreme macro events or illiquid holiday sessions, when Tier-1 liquidity providers reduce market depth, INFINOX may temporarily adjust margin requirements or toggle specific assets to ‘Close Only’ to protect client capital, with no notice period stated. The same section warns that “spreads routinely widen immediately before and after” scheduled liquidity breaks, a cost not reflected in the “spreads from” figures quoted on the account comparison pages. And under corporate actions, a client holding a short CFD position past an ex-dividend date “incur[s] a debit,” deducted directly from their account balance, while long positions receive a credit. None of these are unusual for a CFD broker, but each is a point where a client’s account balance can move for reasons outside their own trading decisions, which is exactly the kind of dispute a support desk would need to explain and that a client would need documentation to challenge.
Set against that, the warning-list check we ran turned up nothing: Infinox does not appear on any of the 1,441 entries mirrored from the CySEC, FCA, and FSC Mauritius warning lists, which is a clean result worth stating plainly, while noting it covers only those three regulators’ published lists.
Prohibited Countries
The clearest statement of who Infinox will not deal with sits in the entry disclaimer on its own site: the firm’s the firm’s Indonesian home page states that Site information not intended for residents of Afghanistan, Belgium, Canada, India, United States, or any jurisdiction where distribution/use is unlawful. That is the list as Infinox itself publishes it, on the page a visitor is routed through before reaching the rest of the site.
What the FCA-regulated entity will and will not do
A separate restriction applies inside the UK. Infinox Capital Ltd, the entity holding FCA authorisation number 501057, states on its own accounts page that “INFINOX Capital Ltd does not offer trading services to retail clients” and restricts onboarding to professional clients or institutions. A UK resident who is not classed as a professional client or an institution cannot open a trading account with the FCA-authorised entity at all, regardless of nationality restrictions elsewhere on the site. The same page adds that the infinox.co.uk site is not directed at residents of the United States, EU/EEA, or any country outside the UK, which rules out US and EU/EEA residents using that particular entity even where they might otherwise qualify as professional clients.
Where retail-facing trading does happen, it runs through a different entity. The Mauritius-facing entry page carries its own warning, aimed at the clients who land there rather than at the FCA book: You will be outside the EU regulatory regime, MIFID II. Therefore you will lose all protections granted under EU Regulations and Law. Under FSC regulation, the same page says Infinox will provide only Best Execution, Segregated accounts, and Balance Protection. That is not a nationality bar, but it is a condition attached to using the entity that actually serves most retail traders: an EU or EU-adjacent client who proceeds anyway is accepting a narrower protection regime than the FCA entity’s brand recognition might suggest.
The list from our earlier review does not match what Infinox itself publishes
An earlier review of Infinox gives a different prohibited-countries list: United States, Canada, Japan, Australia, New Zealand, Belgium. We are not able to verify that list against any page we fetched, and two of the entries on it are hard to square with what Infinox currently publishes: the firm runs dedicated, geo-targeted pages for Australia and for Japan, which is difficult to reconcile with those two countries being barred outright. We report the figure from our earlier review as what the earlier review said, not as a fact confirmed from Infinox’s own material, and we flag the contradiction rather than silently dropping it.
Between the two sources, the only prohibited-countries claim we can attribute to Infinox’s own page is the Indonesian home page disclaimer: Afghanistan, Belgium, Canada, India, and the United States, plus a general catch-all for any jurisdiction where distribution/use is unlawful. Belgium and Canada appear on both the firm’s own list and the one in our earlier review; Afghanistan, India, Japan, Australia and New Zealand do not overlap between the two at all. A reader relying on this review should treat the Indonesian home page wording as the current statement from Infinox and treat the figures from our earlier review as unconfirmed and possibly outdated.
No published country list for the Mauritius or UAE entities specifically
The pages we fetched for the Mauritius entity (INFINOX Limited, FSC licence) and the UAE marketing entity (Infinox Financial Consultants L.L.C S.O.C, CMA licence) describe licensing and protections but do not carry their own country-exclusion list separate from the site-wide the firm’s Indonesian home page disclaimer. We have not fetched a page that sets out, entity by entity, which of Infinox’s regulated or unregulated books a resident of a given country would actually be onboarded through. Where the site’s own disclaimer, the FCA entity’s professional-only rule, and the Mauritius entity’s EU-protection warning between them, that is the extent of what the fetched pages establish about who is shut out and on what terms.
Conclusion
Infinox lands at 6.5 overall, and the gap between its individual scores explains why: solid pricing and platform choice sit next to weak marks for regulation (4.8) and support (4.8), pulled down not by any single red flag but by a structure that keeps its best-known licence away from most of the clients reading this review.
What the FCA licence actually covers at Infinox
The FCA register confirms FRN 501057 as Authorised, held by Infinox Capital Limited since 15/09/2009, and Companies House confirms the same company as number 06854853, a Private limited Company incorporated 21 March 2009 and still Active. That is real oversight of a real company. But Infinox Capital Ltd’s own UK accounts page states plainly that it “does not offer trading services to retail clients” and only onboards professional clients or institutions. A retail trader reading “FCA-regulated” is not describing the entity that will hold their account.
Retail business instead runs through INFINOX Limited in Mauritius, which the FSC Mauritius Online Public Register confirms holds an SEC-2.1B Investment Dealer (Full Service Dealer excluding Underwriting) licence dated 19/11/2020, though the register lists the licence type and date without a licence number, so the GB20025832 number Infinox quotes is not itself confirmed there. The entry page clients pass through to reach the Mauritius entity warns them directly that they will be outside the EU regulatory regime, MIFID II and will lose all protections granted under EU Regulations and Law, leaving only Best Execution, Segregated accounts, and Balance Protection as the stated FSC-level safeguards. In the UAE, the Capital Market Authority register confirms Infinox Financial Consultants L.L.C S.O.C as CP-0001749, Active, but licensed under Category 5 as a marketing and introducing entity rather than a dealer: it brings clients in, it does not hold their trades. An earlier review of Infinox claimed a Securities Commission of The Bahamas licence; we checked the Commission’s Securities Industry Act registrant list as at 31 August 2026 directly, and “INFINOX” is not on it, and that list is the Commission’s complete roll of registrants. We also hold no register to check the Anguilla incorporation (company A000001246, trading as INFINOX Global Limited) against, so that entity’s status is untested by us rather than confirmed either way.
Infinox’s spreads and account fees
Infinox’s own account comparison page lists two live account types. The STP account quotes spreads from 0.9 pips on FX majors and from 15 cents on gold, commission from 0, and leverage up to 1:1000. The ECN account quotes spreads from 0.2 pips on FX majors and from 8 cents on gold, with commission applying on top and the same 1:1000 leverage ceiling. Infinox’s fee page states there are no hidden fees on its side for deposits or withdrawals, though it notes independent bank or payment-provider network fees may still apply. Its account terms also flag that “Admin fees may apply to certain Swap-Free / Islamic instruments” in place of standard swap charges, without publishing an amount, and that VPS hosting through 4XSolutions goes only to clients who meet unspecified monthly volume requirements, again with no published fee. Infinox’s own operational notes add that the advertised 1:1000 leverage is a ceiling only, “scaling based on your total notional exposure” rather than staying flat, and that spreads “routinely widen” around scheduled liquidity breaks, a cost the headline “spreads from” figures don’t carry.
Platforms and how Infinox handles support
Trading runs on MetaTrader 4, hedging-only, and MetaTrader 5, which supports hedging or netting depending on account setup and is the only platform carrying stocks and ETFs. Infinox layers its own IX Social copy-trading platform and IX App mobile app, which handles direct trading, deposits, withdrawals and KYC verification, on top of the MetaTrader pair. Support runs through support@infinox.com, a Live Chat widget described as part of 24/7 operational support, and a web contact form; a separate primesupport@infinox.co.uk address is reserved for professional and institutional clients of the FCA entity only, meaning most retail traders are routed to the general channels rather than to the UK desk.
We searched 1,441 warning-list entries mirrored from the FCA, CySEC and FSC Mauritius, and Infinox appears on none of them, a clean result, though it only covers the regulators we mirror and not every authority worldwide.
Infinox’s FCA licence, confirmed on the FCA register, excludes retail clients, who trade instead through weaker-protected entities in Mauritius or the UAE, with ECN spreads from 0.2 pips. We score Infinox 6.5 out of 10 overall.
What we saw
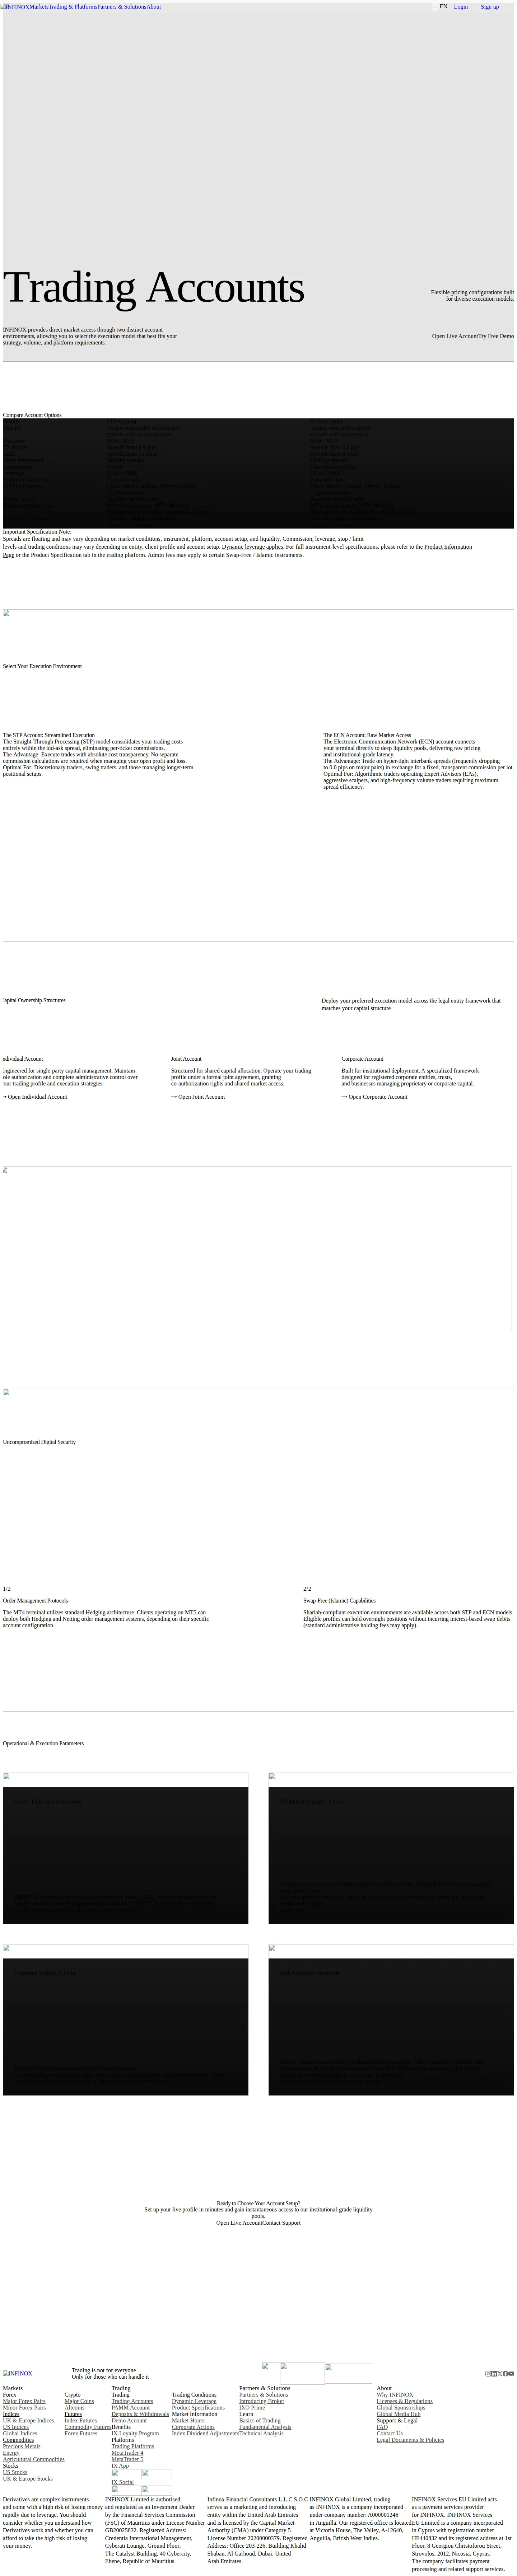
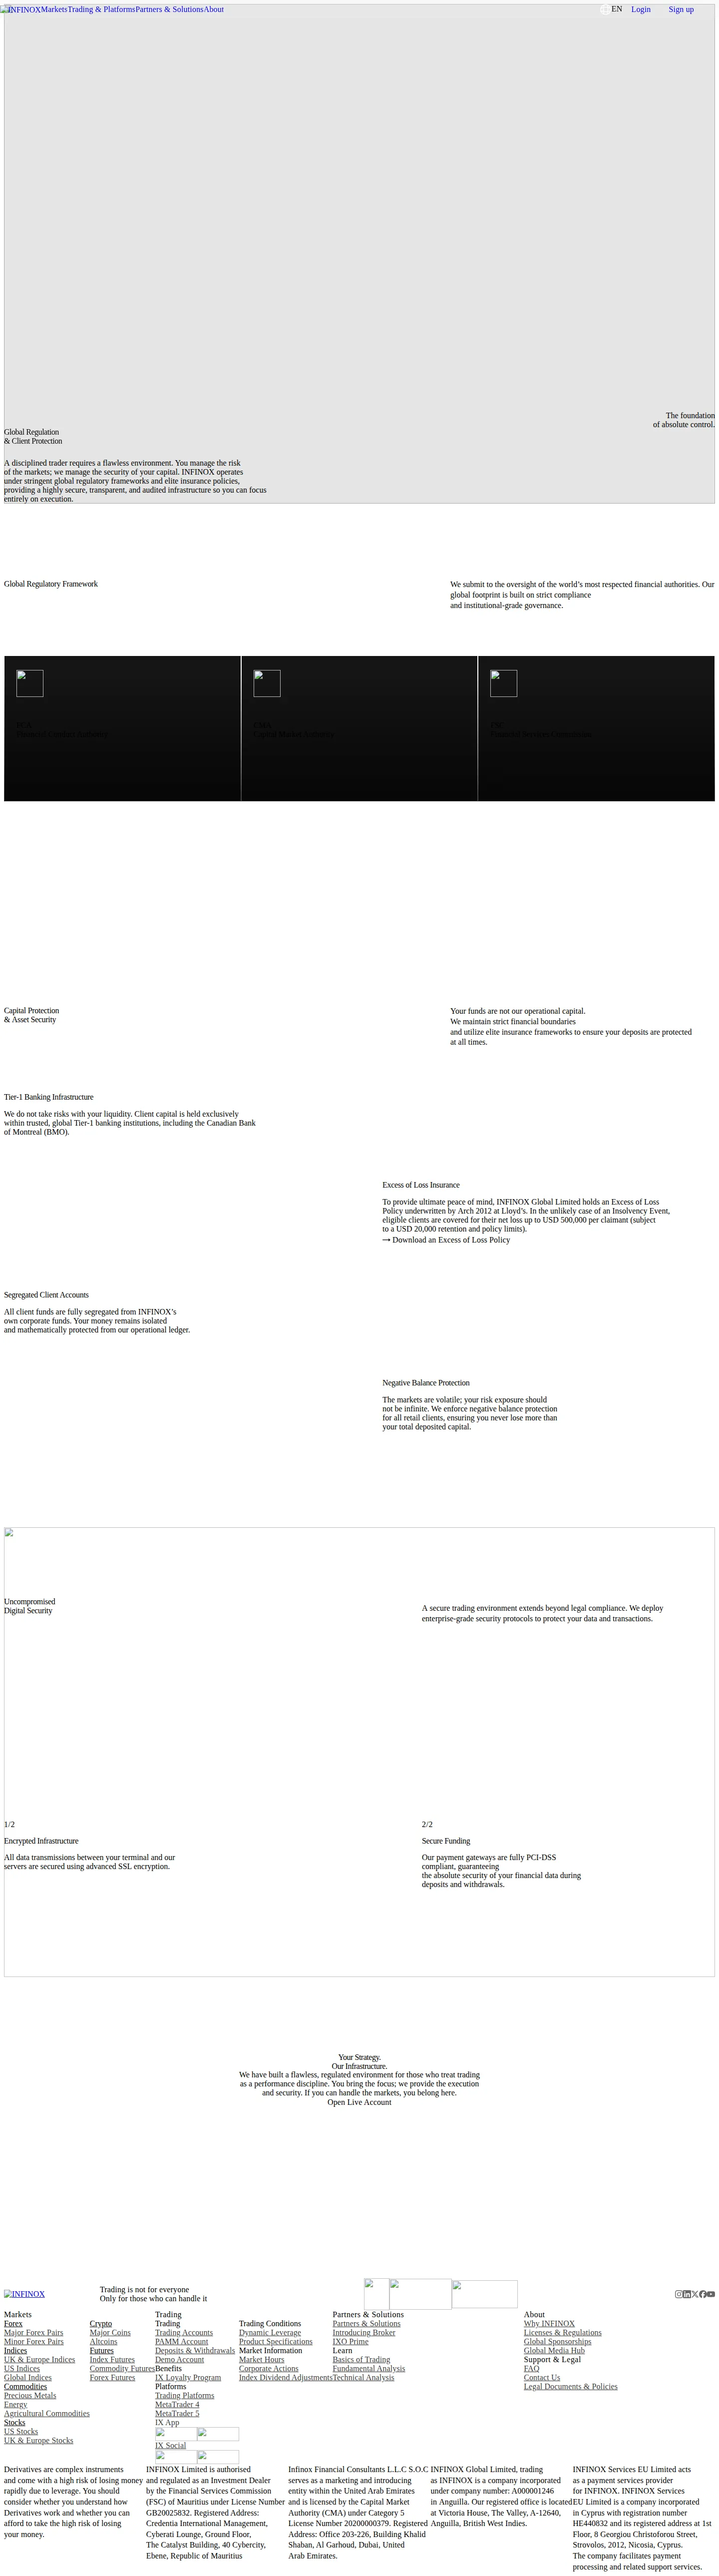
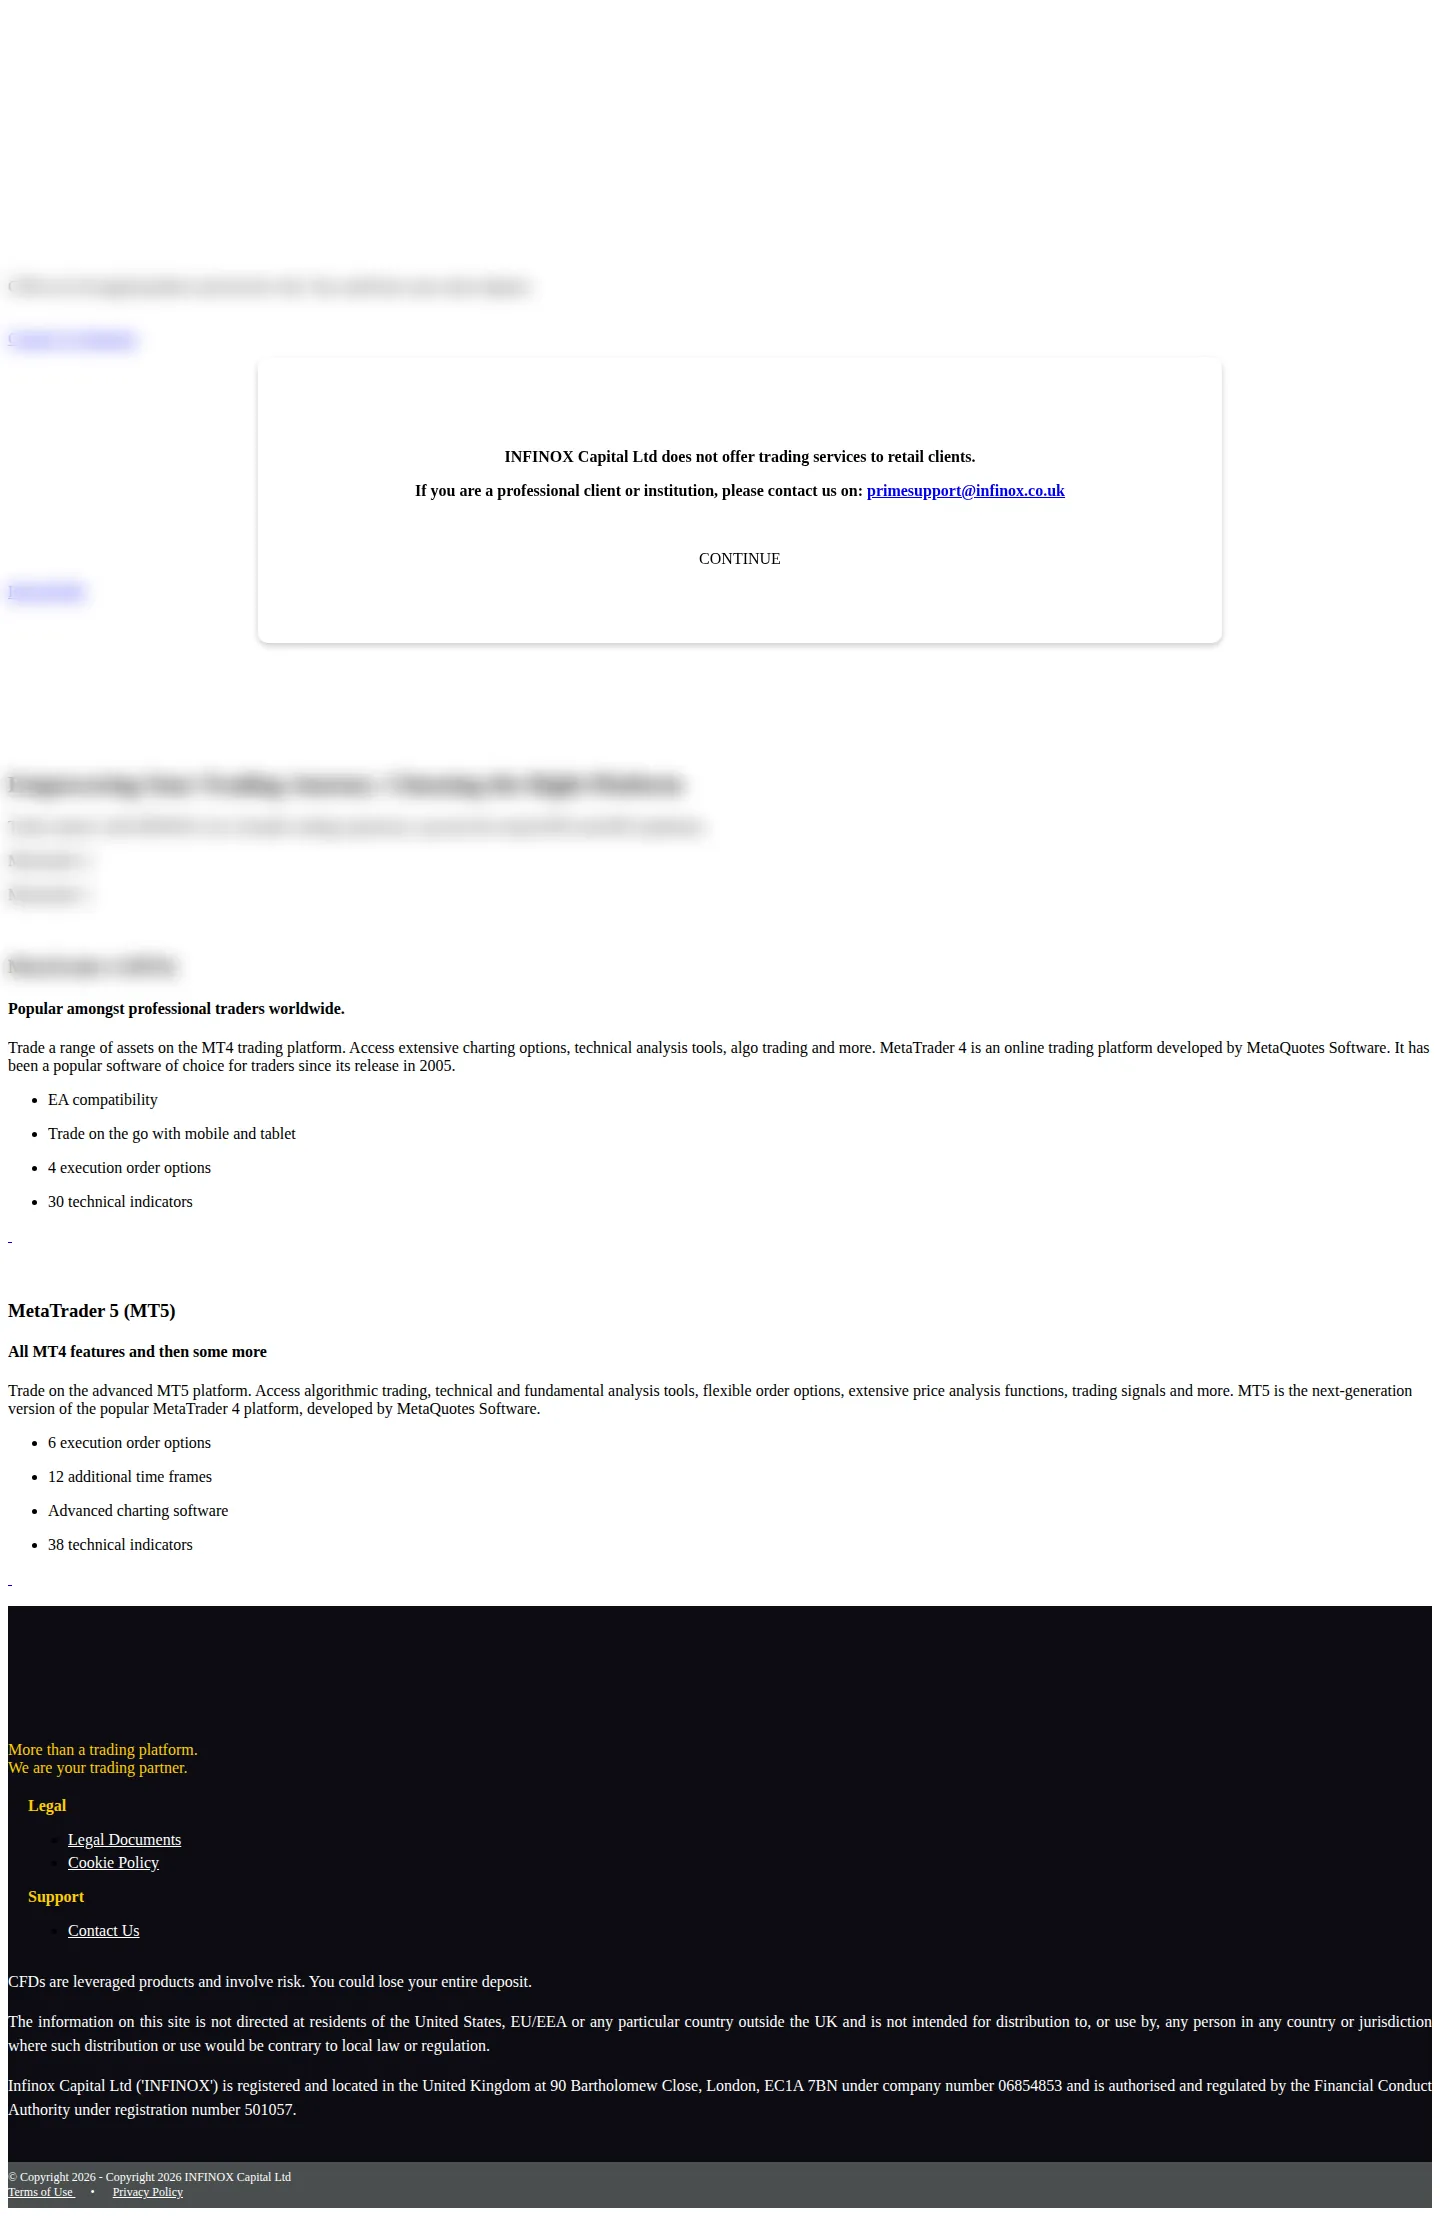
Pages captured from Infinox’s own site when this review was written. Brokers change their terms; these are what we read.
Score history
Recomputed daily; every move is on the record. The current score is always the latest row.
| Date | Score | Move |
|---|---|---|
| 2026-09-29 | 6.5 | ▲ |
| 2026-07-25 | 6.2 | ▼ |
| 2026-07-18 | 6.4 | ▲ |
| 2026-07-11 | 6.3 | · |
FAQ
Is Infinox regulated?
Yes. Infinox Capital Ltd holds FCA licence 501057, and Infinox Limited holds an FSC Mauritius Investment Dealer licence.
Which entity do retail clients actually trade with?
Retail clients are onboarded through Infinox Limited in Mauritius, not the FCA-regulated Infinox Capital Ltd, which does not take retail clients.
What protection do Infinox clients get if the firm becomes insolvent?
Mauritius clients are covered by private Lloyd’s insolvency insurance with a $20,000 retention, not a statutory compensation scheme.
What does Infinox charge to trade EURUSD?
A published ‘from’ spread of USD 9.00 round turn on 1 lot EURUSD on the STP Account.
What trading platforms does Infinox offer?
MetaTrader 4, MetaTrader 5, its own mobile app, and copy trading through IX Social via the IX App.
Is Infinox's UAE licence verified?
No. The CMA UAE licence number could not be matched on the regulator’s register, and that entity only covers marketing, not trading.
How this review works
Track Infinox live: score moves and red notices, in your pocket.