STOCK · CHECKED 12 OCT 2026
Huatai International review.
Hong Kong brokerage arm of Huatai Securities, with an SFC licence confirmed under its subsidiary's name
RISKY
OUT OF 10
Huatai International is the Hong Kong arm of Huatai Securities, a Chinese broker listed in Shanghai, Hong Kong and London. SFC licence AOK809 is confirmed on the register, held by Huatai Financial Holdings (Hong Kong) Limited, and covers seven regulated activities with no disciplinary record. Support runs by phone, fax and live chat in business hours. The main reservation is cost: no trading fees we could read first-hand are published for a retail account.
Each criterion is scored 1 to 10 from primary sources. The overall score is their unweighted mean. How scoring works.
| Founded | 2006 |
|---|---|
| Headquarters | HK |
| Minimum deposit | $0 |
| Account opening | 1-3 |
- SFC licence AOK809 confirmed on the register for Huatai Financial Holdings (Hong Kong) Limited
- Licence covers seven regulated activities, with no public disciplinary action
- Parent Huatai Securities is listed in Shanghai, Hong Kong and London
- Phone, fax and live chat support for Hong Kong and Mainland China
- Not on the CySEC, FCA or FSC Mauritius warning lists we searched
- The licence sits with a subsidiary, not the holding company named in our earlier review
- No trading costs we could read first-hand for a retail account
- The $0 minimum deposit and the ZhangLe Global platform come from our earlier review, not the firm's pages
- Support is staffed in business hours only
- Own Android app rated 3.2 across 183 ratings, and no Trustpilot profile
- Website content is limited to Hong Kong residents by its own terms
Overview
TrueBroker is a free broker safety checker, and this page is our review of Huatai International, scored 5.2 out of 10 across regulation, fees, platform, support and reviews. TrueBroker scored this firm 4.1 out of 10 in an earlier review; this review restates that score at 5.2 out of 10 from current evidence, not because the firm has changed. The move rests mainly on two checks: the Hong Kong Hong Kong public register of licensed persons register we searched confirms an active regulated-activity licence, carrying 9 licensing conditions and no recorded disciplinary action, held by the group’s Hong Kong operating subsidiary, and a search of 1441 warning-list entries mirrored from CYSEC, the FCA and FSC Mauritius returned no match for the firm.
Who actually holds the licence at Huatai International
The group’s own about page describes a two-tier Hong Kong structure: Huatai International Financial Holdings Company Limited (華泰國際金融控股有限公司) is the Hong Kong holding company for the group’s overseas platform, a wholly-owned subsidiary of Huatai Securities Co., Ltd. The Securities and Futures Commission licences sit one level down, with the operating subsidiary Huatai Financial Holdings (Hong Kong) Limited (華泰金融控股(香港)有限公司, also styled 華泰金控), incorporated in Hong Kong in November 2006. We searched the SFC’s Public Register of Licensed Persons and Registered Institutions directly and confirmed that CE reference AOK809 belongs to Huatai Financial Holdings (Hong Kong) Limited, licensed for Type 1 (Dealing in Securities), Type 2 (Dealing in Futures Contracts), Type 3 (Leveraged Foreign Exchange Trading), Type 4 (Advising on Securities), Type 6 (Advising on Corporate Finance), Type 7 (Providing Automated Trading Services) and Type 9 (Asset Management), each shown as active, with 9 licensing conditions attached and no public disciplinary action recorded. The same register search contradicts an earlier claim, carried over from the previous review, that CE AOK809 belongs to “Huatai International Financial Holdings Company Limited”: the SFC register attributes that licence number to the operating subsidiary, Huatai Financial Holdings (Hong Kong) Limited, not to the holding company. A reader checking the licence should look up Huatai Financial Holdings (Hong Kong) Limited on the SFC register, not the holding-company name the firm markets under.
The parent, Huatai Securities Co., Ltd, was founded in 1991 and is triple-listed: A-shares on the Shanghai Stock Exchange (601688.SH) since 26 February 2010, H-shares on the Hong Kong Stock Exchange (6886.HK) since 1 June 2015, and GDRs on the London Stock Exchange (HTSC.L) since 17 June 2019, the group’s about page states it was the first Chinese company listed via the Shanghai-London Stock Connect mechanism. The same page reports that Standard & Poor’s assigned the group a BBB+ long-term issuer rating and an A-2 short-term issuer rating in 2024. Outside Hong Kong, the group also runs Huatai Securities (USA), which obtained a broker-dealer licence in 2019, and a Singapore subsidiary established in September 2022 as a regional hub for Southeast Asia, which the firm’s own page describes as still “continuously obtaining” local licences rather than fully licensed there.
Overview Table
| Headquarters | Room 4201, 53/F, 5808-12/F and whole floors 62 & 69, The Center, 99 Queen’s Road Central, Hong Kong |
| Established | Huatai Securities Co., Ltd, the parent company, was founded in 1991; its operating subsidiary, Huatai Financial Holdings (Hong Kong) Limited, was incorporated in Hong Kong in November 2006. |
| Countries Served | Not stated; the firm’s own terms limit the website’s content to persons resident in or businesses based in Hong Kong SAR. |
| Regulated By | Huatai Financial Holdings (Hong Kong) Limited, the group’s subsidiary, is licensed under CE reference AOK809 by the Securities and Futures Commission (SFC) of Hong Kong. |
| Minimum Deposit | $0 for the Standard Account, per the earlier review this piece updates; the firm’s own pages do not confirm this figure. |
| Maximum Leverage | Not stated |
| Total Instruments | Not stated |
| Platforms | ZhangLe Global (漲樂全球通) per the earlier review this piece updates, offered across mobile, web and API access. |
| Customer Support | A phone switchboard plus separate customer service and quick order hotlines for Hong Kong and Mainland China, along with fax and live chat, staffed 9:00 AM-12:00 PM and 1:00 PM-6:00 PM. |
| Languages | Chinese and English, per the firm’s contact page; the earlier review this piece updates also lists these as the ZhangLe Global platform’s interface languages. |
Facts List
- The group’s overseas platform sits under the Hong Kong holding company Huatai International Financial Holdings Company Limited, which is wholly owned by Huatai Securities Co., Ltd.
- The SFC regulated-activity licences are held by the operating subsidiary Huatai Financial Holdings (Hong Kong) Limited, incorporated in Hong Kong in November 2006, not by the holding company.
- The SFC register we searched shows CE AOK809, held by Huatai Financial Holdings (Hong Kong) Limited, licensed for Types 1, 2, 3, 4, 6, 7 and 9, each active, carrying 9 licensing conditions, with no public disciplinary action recorded.
- The same register search contradicts an entity attribution carried over from the earlier review: CE AOK809 belongs to the Hong Kong operating subsidiary, not to “Huatai International Financial Holdings Company Limited” as that review stated.
- Parent company Huatai Securities Co., Ltd was founded in 1991 and is triple-listed in Shanghai (601688.SH, since 26 February 2010), Hong Kong (6886.HK, since 1 June 2015) and London (HTSC.L GDRs, since 17 June 2019).
- Standard & Poor’s assigned the group a BBB+ long-term and A-2 short-term issuer rating in 2024.
- We searched 1441 warning-list entries mirrored from CYSEC, the FCA and FSC Mauritius and found no match for this firm, running a positive control on the registers first to confirm the search itself works.
- The group also operates Huatai Securities (USA), which obtained a broker-dealer licence in 2019, and a Singapore subsidiary established in September 2022 that is, per the firm’s own page, still obtaining local licences rather than fully licensed there.
- A restricted-country list attributed to this firm in a prior review could not be traced to anything the firm publishes; a check of the firm’s homepage, legal, terms and legal-documents pages found no published restricted-country list.
- The firm’s terms of use, read directly, disclaim liability for site or platform malfunction, require the client to indemnify the firm for claims tied to the client’s own use of the site, and put disputes over website use under Hong Kong law and the non-exclusive jurisdiction of the Hong Kong courts.
Key Takeaways
This review scores Huatai International 5.2 out of 10, up from the 4.1 we gave it previously. That is our assessment moving, not the firm’s conduct changing: this pass checked the Hong Kong SFC register directly, ran a positive control to make sure an empty result would mean something, and searched 1,441 warning-list entries mirrored from CYSEC, the FCA and the FSC Mauritius, none of which name this firm. Those checks pull the regulation score to 6 and the warning-list result is clean, but the fee picture rests on unverified figures carried over from an earlier review, which is why fees still scores only 3.
What the SFC register actually shows about Huatai International
- The earlier review’s claim that CE reference AOK809 on the Hong Kong SFC Public Register of Licensed Persons and Registered Institutions belongs to “Huatai International Financial Holdings Company Limited” is contradicted: the SFC register lists that reference under “Huatai Financial Holdings (Hong Kong) Limited (華泰金融控股(香港)有限公司)” instead, a different entity in the same group.
- Checked against the correct holder, the SFC register confirms Huatai Financial Holdings (Hong Kong) Limited under AOK809 for Type 1, 2, 3, 4, 6, 7 and 9 regulated activities (dealing in securities, dealing in futures, leveraged foreign exchange trading, advising on securities, advising on corporate finance, providing automated trading services, and asset management), all shown as active, with no public disciplinary action recorded and 9 licensing conditions attached to the licence.
- The earlier review’s own licence-type list (1, 2, 4, 5, 6, 9) does not match what the SFC register shows: it includes a Type 5 the register does not, and omits the Types 3 and 7 the register does carry. It also names a licence number the firm’s own about page never states.
- The firm’s about page describes the Hong Kong regulated entity as Huatai Financial Holdings (Hong Kong) Limited, incorporated in Hong Kong in November 2006, and gives no licence number of its own for readers to check against the register directly.
- Outside Hong Kong, the group’s about page states that Huatai Securities (USA) obtained a broker-dealer licence in 2019, and that a Singapore subsidiary set up in September 2022 is still obtaining local licences; neither of those was a register we checked in this pass.
Fees and account tiers
- The account structure, as carried over from the earlier review, runs four tiers: a Standard account with no stated minimum deposit, a Premium account requiring HKD 100,000, a qualification-based Professional account, and a negotiable Institutional account, with commission rates, support level and API access all said to scale up the tiers.
- The earlier review also describes a new-client promotion of commission-free trading on HK and US stocks for three months, plus a trading credit of HKD 500-2,000 tied to the size of the initial deposit, and states that most deposit methods carry no deposit fee.
- None of these figures come from a page this pass fetched directly, so they carry the same unverified status as the licence details above; the low fees score reflects that the pricing and promotional detail cannot yet be checked against the firm’s own site.
Platform, instruments and support at Huatai International
- The primary platform named in the earlier review is ZhangLe Global (漲樂全球通), covering mobile, web and API access with over 50 technical indicators and streaming quotes in Chinese and English; this was not independently verified in this pass.
- Instrument range as described by the earlier review spans A-shares via Stock Connect, HK H-shares, US equities, government and corporate bonds, equity derivatives, major FX pairs including onshore and offshore renminbi, and alternative investments such as private equity and hedge funds.
- The contact page we fetched lists a Hong Kong switchboard, separate customer-service and quick-order hotlines for mainland China and Hong Kong, a fax number, and an office at The Center, 99 Queen’s Road Central, with office hours of 9:00 AM to 12:00 PM and 1:00 PM to 6:00 PM, and customer-service hours of 9:00 AM to 6:00 PM Monday to Friday. The listed email for general securities services is hkinfo@htsc.com.
- Live chat, described by the earlier review as available 9 AM to 6 PM Hong Kong time with a stated response time under five minutes, was not something this pass could check directly.
Terms that bind a client
- Under Liability (責任), Huatai International disclaims liability, including for consequential or incidental damages such as lost profits, arising from use of the website or reliance on its content, except where a separate product agreement says otherwise.
- Under Investment Risk (投資風險), if margin falls to or below the maintenance level the client must top up or reduce holdings without waiting for a demand from the firm, and Huatai International can close out open positions without further notice, with the client responsible for the resulting loss.
- Under System Failure (系統故障), the firm accepts no liability for malfunctions, server or connection failures, viruses or transmission errors connected to a client’s use of the website or online services, even where it had been notified such issues might occur.
- Under Copyright and Ownership (版權及擁有權), any data or material a client submits through the website is licensed to the firm worldwide, royalty-free and in perpetuity, for any purpose the firm deems appropriate.
- Under Website Information and Terms Amendment (網站資訊與條款修訂), the firm can change site content or the terms of use at its own discretion without prior notice, and under Jurisdiction (司法管轄權) disputes over website use fall under Hong Kong law and the non-exclusive jurisdiction of the Hong Kong courts.
What is missing
- A restricted-country list attributed to this broker in a prior version of this review could not be traced to anything the firm publishes; a check of the homepage, legal, terms and legal-document pages found no such list, so no assumption should be made about which countries this firm serves.
- The terms we read state that the website’s content is directed only at persons resident in, or businesses based in, Hong Kong SAR, and that continuing to browse represents the reader is not resident outside Hong Kong.
Licenses & Regulation
Huatai International Financial Holdings Company Limited is not, on the record we checked, the entity that holds the Hong Kong licence the earlier review attributed to it. We searched the Securities and Futures Commission’s Public Register of Licensed Persons and Registered Institutions directly (running a positive control against a firm known to be listed first, so an empty result would mean absence rather than a broken search), and CE reference AOK809 belongs to a different company in the group: Huatai Financial Holdings (Hong Kong) Limited ( ), not “Huatai International Financial Holdings Company Limited” as the figure from our earlier review claimed. That licence covers Type 1, Type 2, Type 3, Type 4, Type 6, Type 7 and Type 9 activities (Dealing in Securities; Dealing in Futures Contracts; Leveraged Foreign Exchange Trading; Advising on Securities; Advising on Corporate Finance; Providing Automated Trading Services; Asset Management), all shown as active, and carries nine licensing conditions on the register. The register shows no public disciplinary action against it.
Which Huatai entity actually holds the SFC licence
Huatai International’s own about page names the same subsidiary, Huatai Financial Holdings (Hong Kong) Limited (華泰金控), incorporated in Hong Kong in November 2006, as the SFC-licensed operating company, and lists the same seven licence types the register shows. That page gives no licence number of its own, so the AOK809 figure could only be checked against the SFC register directly, where it confirmed the entity but contradicted the name the earlier review had attached to it. The distinction matters for a client working out who they would actually be contracting with: Huatai International Financial Holdings Company Limited is described on the same page as the Hong Kong holding company and a wholly-owned subsidiary of the mainland-listed Huatai Securities Co., Ltd, while the licensed dealing, futures, leveraged forex, advisory, corporate finance, automated trading and asset management activities sit with the operating subsidiary underneath it.
Two other pieces of the earlier review’s licence claim could not be checked at all. It names no authority for one figure and no licence number for the Hong Kong company incorporation it cites, so there was no register entry to look either up against; that is a gap in what was claimed, not a finding about the firm. The group’s other regional arms sit outside what we could verify here: the firm’s own page says Huatai Securities (USA) obtained a broker-dealer licence in 2019, and that a Singapore subsidiary set up in September 2022 is still, in the firm’s own words, in the process of obtaining local licences, but neither page names the licensing authority in a form we hold a register for.
Warning-list search and the parent’s listings
We searched 1,441 warning-list entries mirrored from CySEC, the FCA and the FSC Mauritius, and Huatai International appears on none of them. That is a genuine clean result, though it only covers the three regulators we mirror, not a global sweep. Separately, the firm’s own page states that the parent, Huatai Securities Co., Ltd, is listed on the Shanghai Stock Exchange (601688.SH) since 26 February 2010, the Hong Kong Stock Exchange (6886.HK) since 1 June 2015, and as GDRs on the London Stock Exchange (HTSC.L) since 17 June 2019 as the first Chinese company listed through the Shanghai-London Stock Connect mechanism. A public listing on three exchanges is a disclosure obligation in itself, but it is not a substitute for the SFC’s regulated-activity licence that actually governs a Hong Kong brokerage relationship.
What Huatai International’s own terms say binds a client
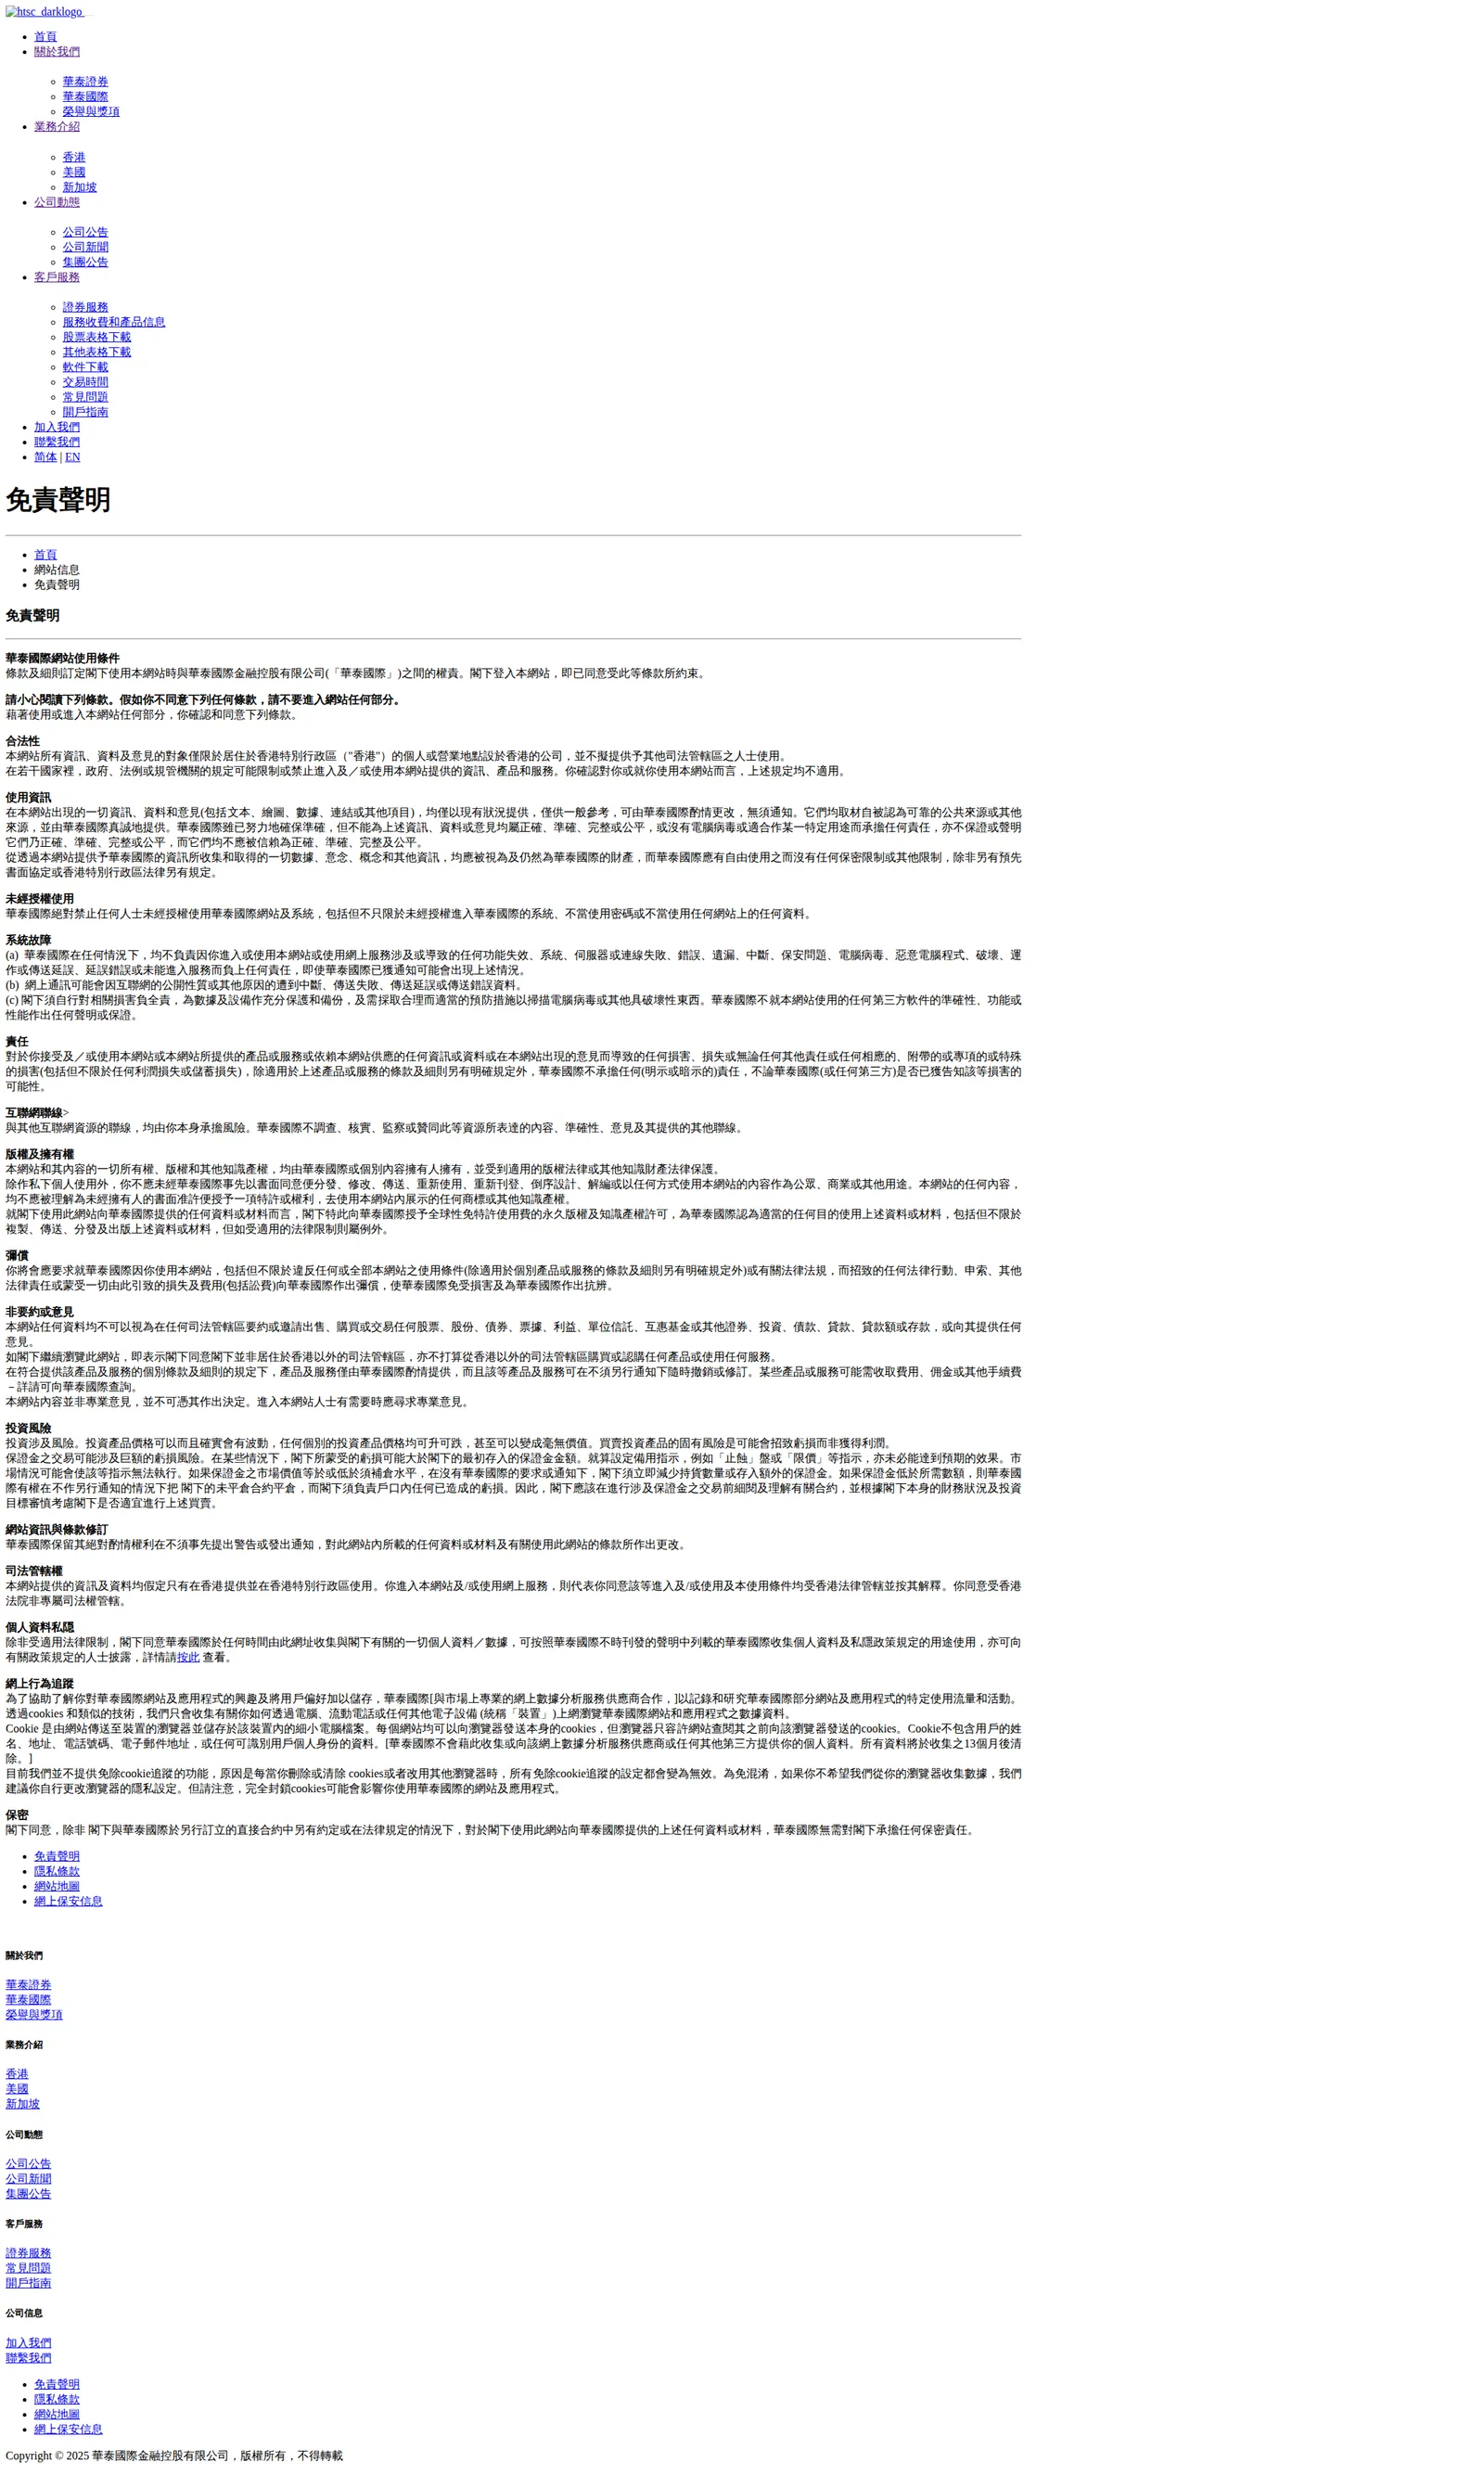
The terms of use we read state, under Jurisdiction (司法管轄權), that access to the website and online services is governed by Hong Kong law and that the client submits to the non-exclusive jurisdiction of the Hong Kong courts. Under System Failure (系統故障), the firm disclaims liability for any malfunction, server or connection failure, error, security issue, virus or delay connected to a client’s use of the website or online services, even where Huatai International had been notified such issues might occur. Under Liability (責任) the firm disclaims liability, including for consequential or incidental damages such as lost profits, arising from use of the site or reliance on its content, except where a specific product agreement says otherwise; under Indemnity (彌償) the client must indemnify the firm, on request, against claims and legal costs arising from the client’s own use of the site. Under Investment Risk (投資風險), if margin falls below the maintenance level the client must top it up without waiting for a demand from the firm, and Huatai International may close out open positions without further notice, with the client responsible for any resulting loss. The same terms page also states that the site’s information and products are directed only at Hong Kong residents and Hong Kong-based businesses, and that continuing to browse represents that the visitor is not resident elsewhere.
This review scores the broker 5.2 overall, up from the 4.1 our previous review gave it. The regulation criterion here lands at 6 out of 10: the register work confirms a real, actively licensed operating entity behind the group with no adverse disciplinary record and a clean result across the warning lists we searched, which supports a mid-range score, but it also surfaces a licence-number and entity mismatch in the previous write-up, unverifiable claims about the US and Singapore arms, and contract terms that put jurisdiction, system failure and margin-call risk squarely on the client. This review restates the score from what the register and the firm’s own terms currently show, not from any change at the firm.
How to Trade
Our earlier review described Huatai International’s trading stack in some detail, and we are restating those points as reported rather than as anything we read on the firm’s own pages. That earlier review reported the firm’s platform as ZhangLe Global (漲樂全球通). It runs on iOS and Android, in a web version, and through an API aimed at algorithmic traders, bundling in real-time streaming quotes, integrated research and more than 50 technical indicators, with the interface offered in both Chinese and English.
What Huatai International lets a client trade
The earlier review’s instrument list covers five broad groups. Equities span Shanghai and Shenzhen A-shares reached through Stock Connect, Hong Kong-listed H-shares, red chips and blue chips, plus the major US markets. Fixed income covers government and corporate bonds and structured products, both offshore and onshore Chinese bonds. The derivatives group includes options on equities and futures tied to major indices and single stocks, alongside futures markets in commodities and currencies. Foreign exchange covers major pairs and crosses alongside offshore (CNH) and onshore (CNY) renminbi trading. A fifth category, alternative investments, covers private equity through what the earlier review called Private Capital Investment, plus mutual funds, hedge funds and structured products. None of this instrument list comes from a page we fetched ourselves, so a client who needs to confirm a specific market or contract is available should check it against the firm’s own product pages before funding an account.
Account tiers change what a client can actually do, not just the commission
The earlier review set out four tiers. A Standard account needs no minimum deposit and carries standard commission, standard support, basic research, margin trading and limited API access. A Premium account needs HKD 100,000 and adds reduced commission, priority support, enhanced research and API access. A Professional account is qualification-based rather than a fixed deposit figure, and adds an institutional commission rate, a dedicated relationship manager, fuller research and enhanced margin terms. An Institutional account is negotiable across the board: commission, support, research and margin are all described as customized or negotiated rather than fixed. The practical effect, as reported, is that API access and margin terms both scale with account tier rather than being switched on uniformly, so a client trading through the API or relying on margin should expect the Standard tier to be the most limited of the four.
The terms that bind a position
We read Huatai International’s own terms of use, and the clause headed Investment Risk (投資風險) sets out what happens once a position is on margin: if the market value of the margin falls to or below the required maintenance level, the client must, without any demand or notice from the firm, immediately reduce holdings or deposit additional margin. If margin falls short, Huatai International has the right to close out the client’s open positions without further notice, and the client is responsible for any resulting losses in the account. That is a standard margin-call structure, but it is worth stating plainly: the firm does not commit to notifying a client before force-closing a position.
A separate clause headed System Failure (系統故障) says the firm is not liable under any circumstances for malfunction, system, server or connection failure, error, omission, interruption, security issue, computer virus, malicious program, sabotage, or delay or error in operation or transmission connected to a client’s access to or use of the website or online services, even where the firm had been notified such issues might occur. Combined with the Liability (責任) clause disclaiming liability for loss arising from use of the website or reliance on its content unless a specific product agreement says otherwise, a client has little contractual recourse if an order fails to execute because of a platform outage.
Who a client is actually trading with, and where that entity sits
The firm’s own about page describes a group structure in which the Hong Kong SFC licences sit with the operating subsidiary, Huatai Financial Holdings (Hong Kong) Limited, incorporated in Hong Kong in November 2006, under the Hong Kong holding company Huatai International Financial Holdings Company Limited. The same page states the group also runs a US entity, Huatai Securities (USA), which obtained a broker-dealer licence in 2019, and a Singapore subsidiary set up in September 2022 that the page describes as still continuously obtaining local licences. Which of these entities a given client actually contracts with, and which regulator therefore stands behind that account, depends on the client’s region and which entity onboarded them; the group’s own page does not resolve that question for a reader in general.
The terms of use we read also restrict who the site is meant for: the stated information, products and opinions are directed only at persons resident in Hong Kong SAR or businesses based in Hong Kong, and by continuing to browse, a user represents that they are not resident outside Hong Kong and do not intend to buy or subscribe to products or services from outside Hong Kong. A client based elsewhere should not assume the platform and account tiers described above are open to them on that basis alone.
Where this review’s assessment moved
Our previous review of Huatai International scored 4.1 out of 10 overall; this review scores 5.2. The platform criterion here scores 6, reflecting a multi-channel setup, as reported by the earlier review, spanning mobile, web and API access with algorithmic-trading support, set against the force-close and no-notice liability terms we read directly in the firm’s own terms of use. The move is our assessment being restated against the current evidence, not a claim that the firm’s trading offering itself has changed.
Account Types
Huatai International’s own pages that we fetched describe the group’s structure, licensing and contact details, but say nothing about account tiers, minimum deposits or commission schedules. Everything below on account types and pricing comes from our earlier review, restated in our own words rather than quoted, since we did not read the account-opening or fee-schedule documents it describes.
The four tiers the earlier review describes
The earlier review lists four account tiers. A Standard Account carries no stated minimum deposit and comes with standard commission rates, standard support, basic research, margin trading, and limited API access. A Premium Account requires a stated minimum deposit of HKD 100,000 and is described as carrying reduced commission, priority support, enhanced research, margin trading, and API access. A Professional Account has no fixed deposit figure attached to it; the earlier review describes its minimum as qualification-based, paired with institutional-rate commission, a dedicated relationship manager, fuller research, enhanced margin terms, and full API access. An Institutional Account is described the same way, with a negotiable deposit and negotiated commission, team support, tailored research, prime-brokerage margin terms, and customized API access.
None of these four descriptions comes with an actual commission rate, spread, or fee schedule attached to it in the material available to us. What the earlier review hands down is the tier structure and the qualitative features tied to each rung, not the numbers a trader would need to compare Huatai International against another broker on cost.
Sign-up terms the earlier review reports
The earlier review also describes two new-client offers: a period of commission-free trading on HK and US stocks lasting three months, and a trading credit of HKD 500 to HKD 2,000 sized to the client’s initial deposit. It separately reports that deposit fees are not charged for most methods. We have no firm page in front of us that states any of these three figures, so they stand as the earlier review’s account of Huatai International’s terms rather than as something we verified against the broker’s own pricing page.
Which entity actually holds the account
The tier descriptions above are attributed to “Huatai International” generically. The broker’s own about page names a specific operating subsidiary, Huatai Financial Holdings (Hong Kong) Limited, as the entity holding the Hong Kong regulated-activity licences that dealing and advisory activity would run under, while the SFC register confirms that same subsidiary, not the holding company Huatai International Financial Holdings Company Limited, at CE reference AOK809. A client opening any of the four tiers above should expect the contracting entity to be the licensed subsidiary rather than the parent named in the tier descriptions, though the pages we fetched do not spell out which entity signs the account agreement for a given client’s region.
Why this section’s fee score stayed low
Our previous review scored this broker 4.1 out of 10 overall; this review scores it 5.2 out of 10. The fees criterion specifically sits at 3 out of 10 here, and the account-tier and promotional pricing above is the reason: none of it is drawn from a page we fetched ourselves, so we can report the structure the earlier review describes but cannot independently confirm a single commission rate, spread, or promotional figure against Huatai International’s own published pricing. The overall score moved because this review rests on a different evidence set and a different scoring pass than the 4.1 figure did, not because anything about the broker’s pricing changed between the two reviews.
Negative Balance Protection
The clearest statement we found on what happens when a position moves against a client sits in the website terms of use published under Huatai International’s Hong Kong pages, in the clause headed Investment Risk (投資風險). It says that if the market value of margin falls to or below the required maintenance level, the client must, without any demand or notice from Huatai International, immediately reduce holdings or deposit additional margin, and that if margin falls below the required amount Huatai International has the right to close out the client’s open positions without further notice. The same clause makes the client responsible for any resulting losses in the account. That is a standard margin-call-and-liquidation mechanism, but it is written entirely from the firm’s side: notice is explicitly not owed to the client at either the call or the liquidation stage, and the loss from a forced close-out lands on the client regardless of how fast the market moved.
What Huatai International’s terms say about the firm’s own liability
Two further clauses in the same terms of use bear directly on who absorbs a loss once it happens. Under Liability (責任), Huatai International disclaims liability, express or implied, for damage, loss or other liability, including consequential, incidental or special damages such as loss of profits or savings, arising from acceptance or use of the website, its products or services, or reliance on any information or opinion published on it, except where a specific product or service agreement expressly says otherwise. Under System Failure (系統故障), the firm states it is not liable under any circumstances for malfunction, system, server or connection failure, error, omission, interruption, security issue, computer virus, malicious program, sabotage, or delay or error in operation or transmission connected to a client’s access to or use of the website or online services, even where it had been notified such issues might occur. Read together with the Investment Risk clause, a client who is stopped out during an outage or a data delay has, on the wording of these terms, no recourse against the firm for the technical failure itself, on top of already bearing the loss from the liquidation.
No stated cap on losses
The terms of use we read describe a margin call, a right to liquidate without notice, and client responsibility for the resulting loss. They say nothing about a cap on how far a client’s account can run negative, and nothing about the firm crediting back a shortfall if losses exceed the funds on deposit. That silence is what the page we fetched contains, not a finding that no such protection exists elsewhere: Huatai International operates through several separately regulated entities by region, and the account-opening agreement a client actually signs with the Hong Kong-licensed subsidiary, Huatai Financial Holdings (Hong Kong) Limited, was not among the documents in our evidence. The four account tiers described to us, Standard, Premium, Professional and Institutional, are each said to offer margin trading, with the Professional and Institutional tiers described as carrying “enhanced margin trading” and “prime brokerage margin terms” respectively, but nothing in what we reviewed sets out loss limits or drawdown thresholds specific to any one tier.
Which entity actually carries the leveraged-trading licence
The Hong Kong SFC Public Register of Licensed Persons and Registered Institutions shows CE reference AOK809, covering Types 1, 2, 3, 4, 6, 7 and 9, including Type 3, Leveraged Foreign Exchange Trading, and Type 9, Asset Management, as held by Huatai Financial Holdings (Hong Kong) Limited (華泰金融控股(香港)有限公司), each shown active and carrying nine licensing conditions, with no public disciplinary action recorded against it. An earlier version of this review had attributed that same CE reference to “Huatai International Financial Holdings Company Limited,” the Hong Kong holding company one tier up; the SFC register does not support that attribution, and the licensee of record for leveraged trading is the operating subsidiary, not the parent. That matters for margin handling specifically, because it is this subsidiary’s licence, not the holding company’s, that covers leveraged foreign exchange trading, and the counterparty enforcing a margin call or liquidation on a leveraged position would be the licensed entity rather than the group holding company whose website terms we read above.
What we did not find
We did not find, on the pages in our evidence, a client trading or margin agreement separate from the general website terms of use, a published maximum-loss or negative-balance policy, or any disclosure of how quickly a margin call escalates to forced liquidation in practice. The website terms describe the mechanism and the allocation of liability; they do not describe numeric thresholds, grace periods, or what happens to an account that goes negative after a fast market move. A prospective client trading on margin through Huatai International would need the account-opening agreement itself, rather than the general terms of use, to see those numbers.
Trading Instruments
What Huatai International is described as offering spans five broad groups: equities (Shanghai and Shenzhen A-shares via Stock Connect, Hong Kong-listed H-shares, red chips and blue chips, plus major US markets), fixed income covering government and corporate bonds and structured products in both offshore and onshore Chinese paper, derivatives including equity options and futures on major indices, individual stocks, commodities and currencies, foreign exchange in major pairs plus offshore CNH and onshore CNY renminbi trading, and alternative investments such as private equity through Private Capital Investment, mutual funds, hedge funds and further structured products. None of this instrument list comes from a page we fetched ourselves; it reached us from the earlier published review, and we report it here restated in our own words rather than as anything Huatai International’s own site told us.
What the SFC licence actually covers
The one place we can check part of this claim against a firsthand source is the licence itself. The SFC register shows Huatai Financial Holdings (Hong Kong) Limited (華泰金融控股(香港)有限公司) holding Type 1, Type 2, Type 3, Type 4, Type 6, Type 7 and Type 9 regulated activities, all active: dealing in securities, dealing in futures contracts, leveraged foreign exchange trading, advising on securities, advising on corporate finance, providing automated trading services and asset management. That licensed activity list is broadly consistent with the equities, futures/derivatives, foreign exchange and asset-management lines our earlier review describes, and Huatai International’s own about page names the same seven activity types for the same subsidiary. But the earlier review attributed a different licence number (AOK809) and a different, shorter activity list (Types 1, 2, 4, 5, 6, 9, with no Type 3 or 7 but an extra Type 5) directly to “Huatai International” itself. The register puts AOK809 on Huatai Financial Holdings (Hong Kong) Limited, not on Huatai International Financial Holdings Company Limited as the claim from our earlier review states, and Type 5 (advising on futures contracts) does not appear on the register entry at all. A reader who wants to check what a given asset class is actually licensed for needs to look at the operating subsidiary’s SFC record, not the holding company name the earlier review used.
Fixed income and the private-equity and hedge-fund line under “alternative investments” would sit under Types 1 and 9 on their face, but we have no page of Huatai International’s own describing how those products are structured, custodied, or which entity in the group actually books them.
Huatai International’s platform and account tiers
ZhangLe Global (漲樂全球通) is the trading platform our earlier review names; it is said to run on mobile and web and to offer API access for algorithmic trading, along with more than 50 technical indicators, live streaming quotes and research content integrated in both Chinese and English. The same source describes four account tiers: a Standard Account with $0 minimum deposit and standard commission; a Premium Account requiring HKD 100,000 with reduced commission, priority support and API access; a Professional Account with a qualification-based minimum offering institutional-rate commission and a dedicated relationship manager; and an Institutional Account with a negotiable minimum and negotiated commission. None of the platform description or these four tiers comes from a Huatai International page we read; both are the earlier review’s account structure and platform description, carried over and restated rather than confirmed against the firm’s own site.
Who can actually access these assets
Huatai International’s own terms page states that the site’s information, products and opinions are directed only at persons resident in Hong Kong SAR or businesses based there, and that by continuing to browse, a visitor represents they are not resident outside Hong Kong and do not intend to purchase or subscribe to products or services from outside Hong Kong. That is a real constraint on the asset list above: whatever mix of A-shares, US equities, bonds, derivatives, FX and alternative investments is on offer, the firm’s own terms frame it as built for Hong Kong-resident clients, not a global retail base. The group’s other regulated entities sit elsewhere in the structure: Huatai Securities (USA), which obtained a broker-dealer licence in 2019, and a Singapore subsidiary established in September 2022 that Huatai International’s own about page says is still in the process of obtaining local licences. Which entity a given client actually contracts with, and which asset classes that entity is licensed to offer them, depends on where the client is based, and the evidence available here does not tell us how that routing works in practice.
Education & Analysis
Huatai International’s own pages that we fetched, the corporate profile, the contact page and the Hong Kong terms of use, describe the group’s licensing, its office and its liability clauses. None of those three pages describes a trading platform, a charting package or a research terminal. Everything below on that front traces back to our earlier review, not to anything we read ourselves, and we say so at each point rather than letting it read as our own testing.
What the earlier review reported about Huatai International’s platform
The earlier review described a single primary platform called ZhangLe Global (漲樂全球通), offered on mobile (iOS and Android), on the web, and via an API for algorithmic trading, with an interface in both Chinese and English. It reported more than 50 technical indicators, real-time streaming quotes and research built into the same platform. We have not opened this platform, run its charting tools, or confirmed the indicator count against any page of Huatai International’s own, so this description should be read as what the earlier review found, not as something our review process verified.
Instrument range said to sit behind the platform
That earlier-review material also sets out, market by market, what the platform is said to support: on the equities side, major US markets alongside blue chips, red chips and Hong Kong H-shares, plus Shanghai and Shenzhen A-shares accessed through Stock Connect; for fixed income, structured products together with onshore and offshore government and corporate bonds; in derivatives, commodity and currency futures alongside futures and equity options on individual stocks and major indices; for foreign exchange, both offshore (CNH) and onshore (CNY) renminbi together with major currency pairs; and under alternative investments, structured products, hedge funds, mutual funds and private equity. As with the platform description itself, this is what the earlier review recorded, and we have not fetched an instruments or markets page from Huatai International to check it against.
Account tiers and how the earlier review said tooling is gated
The earlier review also tied platform features to account tier. Its Standard Account, opened with no stated minimum, is described as carrying standard commission, basic research and limited API access. Its Premium Account, put at a HKD 100,000 minimum, is described as adding priority support, enhanced research and API access. Its Professional Account, gated by an unspecified qualification rather than a fixed deposit, is described as adding a dedicated relationship manager, fuller research and full API access. Its Institutional Account, with a negotiable minimum, is described as adding team support, tailored research and customised API access. If accurate, this means the algorithmic-trading API the earlier review attributes to ZhangLe Global is not available on the entry tier at all, and expands in stages as a client moves up the account structure, but we did not read an account-comparison page of Huatai International’s own to confirm the tiering.
What Huatai International’s own terms say about platform failure
The one platform-adjacent material we did read directly is the liability language in the Hong Kong terms of use. Under the clause headed System Failure (系統故障), Huatai International states it is not liable under any circumstances for malfunction, system, server or connection failure, error, omission, interruption, security issue, computer virus, malicious program, sabotage, or delay or error in operation or transmission connected to a client’s access to or use of the website or online services, and the terms state this holds even where Huatai International had been notified such issues might occur. A separate clause, headed Website Information and Terms Amendment (網站資訊與條款修訂), reserves the firm’s discretion to change any information or material on the website, and the terms of use themselves, without prior warning. Read together, a client using the website or an online service has no recourse under these terms for an outage, a data error or a security incident on the platform side, and cannot rely on the terms describing that platform staying fixed from one day to the next.
What we did not find
None of the pages we fetched from Huatai International, corporate profile, contact details, terms of use, carries a demo account, a downloadable platform brochure, or a description of the charting package, order types or research feed that a client would actually see inside ZhangLe Global. That is a gap in what we fetched, not a finding that these features are absent, and a prospective client would need to open an account or request a platform walkthrough directly from Huatai International to see the tooling described in the earlier review for themselves.
This review’s platform score of 6 out of 10 reflects that split: a multi-channel platform with a reported indicator set and API access is a reasonable base, but nothing in it rests on a page we opened ourselves, and the terms we did read place the failure risk squarely on the client. This review scores Huatai International 5.2 out of 10 overall, against 4.1 out of 10 in our previous review; that move is this review’s own reassessment against the evidence gathered this time, including the platform description above, and is not a claim that the firm’s platform has changed.
Special Offers
Two promotional claims appear in the material for this review, both flagged there as coming from an earlier published review of Huatai International rather than from a page our review process fetched itself: a commission-free trading period of three months on Hong Kong and US stocks for new clients, and a trading credit worth HKD 500 to HKD 2,000, scaled to the size of a client’s initial deposit. We report both here as what that earlier review said, not as something read off the firm’s own site, because the pages we did fetch for this rewrite (Huatai International’s about pages, its contact page, its terms of use) contain no promotions section and say nothing about either offer.
What the earlier review reported about Huatai International’s offers
The three-month commission-free window is described as applying specifically to HK and US stock trading for new clients, with no expiry date, deposit threshold or renewal condition attached in the material available to us. The trading credit is described only in the range HKD 500 to HKD 2,000, tied to “initial deposit amount” without the earlier review specifying the deposit tiers that map to each credit level. Neither the percentage or fixed-amount structure of the credit, nor whether it is paid in cash, added as trading credit, or subject to a minimum holding period before withdrawal, is stated anywhere in the evidence we hold. A reader who wants those mechanics would need to get them from Huatai International directly; this review cannot supply what it was not given.
The same earlier-review material also lists deposit fees as “none stated for most methods,” and the payment detail we do hold is consistent with that: Hong Kong FPS deposits are listed as instant and free, and bank wire deposits carry bank fees rather than a fee charged by the broker itself. None of this is presented as a promotion in the material we hold, only as the ordinary cost of moving money in, but it means a new client is not paying to fund the account before any commission-free period or credit applies.
Why any of this could change without notice
Huatai International’s own terms of use, which we did read directly, include a section headed Website Information and Terms Amendment (網站資訊與條款修訂). It reserves to the firm absolute discretion to change any information or material on the website, and the terms of use themselves, without prior warning or notice. That clause is not written with promotions in mind specifically, but it covers all website content, and an advertised offer is website content. A client who signs up on the strength of a stated three-month commission-free period or a stated credit range has no contractual footing in these terms to insist those figures stay fixed between the day they read them and the day they open an account.
We searched 1,441 warning-list entries mirrored from CYSEC, the FCA and the FSC Mauritius, and Huatai International does not appear on any of them; that result covers conduct warnings, not promotional terms, and is noted here only because it is the one first-hand check our review process ran that touches the broader question of whether to trust the firm’s marketing. It does not confirm or extend to the commission-free offer or the trading credit, which remain unverified against anything Huatai International itself publishes.
Opening an Account
Huatai International does not publish an account-opening walkthrough in the pages our review process fetched, so our review process cannot report signup steps or a verification checklist the firm names itself. What the evidence supports is who the firm says it will and won’t deal with, which entity actually signs the client up, and the tier structure an earlier published review reported.
Who Huatai International will actually let open an account
The firm’s own terms page states that its website information, products and opinions are directed only at persons resident in Hong Kong SAR or businesses based in Hong Kong, and are not intended for people in other jurisdictions. By continuing to browse, a visitor represents that they are not resident outside Hong Kong and do not intend to purchase or subscribe to products or services from outside Hong Kong. That is a narrower gate than a broker with a genuinely international onboarding flow would set, and it means a prospective client based outside Hong Kong is, on the firm’s own wording, not the audience these pages are written for.
The group does operate outside Hong Kong through other entities: the firm’s own about page describes a US entity, Huatai Securities (USA), that obtained a broker-dealer licence in 2019, and a Singapore subsidiary set up in September 2022 that the firm describes as still continuously obtaining local licences. Neither of those pages describes an account-opening path for a retail client reaching the firm through those entities, so what onboarding into the US or Singapore business looks like is not something these pages say.
Which entity actually signs the client up
This matters at account opening because it decides which regulator and which protections apply to the contract. The firm’s own about page states that the regulated-activity licences are held by a subsidiary, Huatai Financial Holdings (Hong Kong) Limited (華泰金融控股(香港)有限公司), incorporated in Hong Kong in November 2006, and that this subsidiary currently holds Type 1, 2, 3, 4, 6, 7 and 9 regulated-activity licences with the SFC. The Hong Kong SFC Public Register of Licensed Persons and Registered Institutions confirms this: CE reference AOK809 on that register belongs to Huatai Financial Holdings (Hong Kong) Limited, licensed for Type 1, Type 2, Type 3, Type 4, Type 6, Type 7 and Type 9 activities, each shown as active, with no public disciplinary action recorded and 9 licensing conditions attached to the licence.
An earlier published review of this firm, which this catalogue is rewriting, had instead attributed licence number AOK809 directly to “Huatai International” and listed a different set of licence types. Checked against the SFC register, that attribution does not hold: AOK809 belongs to the Hong Kong subsidiary, not to the parent holding company the earlier review named, and the subsidiary’s licensed activities include Types 3 and 7, which that earlier review omitted, while the earlier review’s Type 5 does not appear on the register at all. A client opening an account should expect to be contracting with the Hong Kong-licensed subsidiary, Huatai Financial Holdings (Hong Kong) Limited, rather than with the holding company whose name appears on the group’s marketing pages.
The tier structure an earlier review reported
An earlier published review of Huatai International, rather than the firm’s own pages, described four account tiers. As that review reported it: a Standard Account with no stated minimum deposit, standard commission and basic research access; a Premium Account requiring HKD 100,000, with reduced commission and priority support; a Professional Account with a minimum that depends on meeting a qualification rather than a fixed deposit figure, offering institutional-rate commission and a dedicated relationship manager; and an Institutional Account with a negotiable minimum and negotiated commission. Because this tier breakdown reached this catalogue from that earlier review rather than from a page our review process fetched directly, it should be treated as reported rather than as verified against the firm’s current account-opening pages.
What signing up binds a client to
The firm’s terms of use, read directly for this review, attach several conditions that apply to using the website and, by extension, to the account relationship. Under the Investment Risk (投資風險) clause, if the market value of margin falls to or below the required maintenance level, the client must reduce holdings or deposit additional margin without waiting for a demand or notice from Huatai International, and if margin falls below the required amount the firm has the right to close out the client’s open positions without further notice, with the client responsible for any resulting loss. Under Liability (責任), the firm disclaims liability, including for consequential or incidental losses such as lost profits, arising from use of the website or reliance on its content, except where a separate product-specific agreement says otherwise. Under Indemnity (彌償), the client must indemnify the firm against claims and costs, including legal costs, arising from the client’s own use of the site. Under System Failure (系統故障), the firm accepts no liability for platform outages, connection failures, viruses or transmission errors even where it had been notified such issues might occur. Under Jurisdiction (司法管轄權), the terms of use are governed by Hong Kong law and the client agrees to the non-exclusive jurisdiction of the Hong Kong courts. And under Website Information and Terms Amendment (網站資訊與條款修訂), the firm reserves absolute discretion to change these terms without prior warning, so a client cannot rely on the version in force at signup staying fixed.
A check of 1,441 warning-list entries mirrored from CYSEC, the FCA and the FSC Mauritius turned up no match for this firm, run with a positive control against a known-listed firm on the two registers checked directly so that a clean result reflects an actual absence rather than a broken search.
Deposits & Withdrawals
Huatai International runs its payments through Hong Kong Feature: bank wire, the Hong Kong Faster Payment System (FPS), and check deposits, according to the earlier review of this broker. Availability and rails are typical of a Hong Kong securities house, but they come with real waiting periods and, on one channel, real fees.
What Huatai International charges to move money
The earlier review reported bank wire deposits landing in one to two days and withdrawals taking two to three days, with bank fees applying. It did not report the size of those fees, so the actual cost of wiring money in or out is not something we can put a number on.
Hong Kong FPS fared better in the same source: instant deposits, withdrawals within 24 hours, and no fee. For a Hong Kong resident able to use FPS, that is the fastest and cheapest rail the earlier review recorded.
Check was listed for deposits only, taking two to three days with no fee. The earlier review marked withdrawal by check as not applicable, so a client who wants cash out has FPS or bank wire, not check.
What we can’t confirm from what we hold
None of the pages we fetched from Huatai International’s own site cover deposit or withdrawal mechanics, minimums, or fee schedules. What we have on payments comes entirely from the earlier review being rewritten, not from a page we read ourselves, so treat the method list, timelines, and “no fee” claims above as second hand rather than verified against the firm’s current terms. The fee list the earlier review carried is thin too: it names a new client promotion (three months commission free on HK and US stock trading) and a deposit sized trading credit of HKD 500 to 2,000, plus a general note that most deposit methods carry no stated fee. None of that tells a client what a wire actually costs after their bank takes its cut, what happens to unused promotional credit, or whether there is a minimum withdrawal amount or a cap on how often funds can be pulled.
The account tiers carried over from the earlier review give a sense of who these rails serve: the Standard account needs no minimum deposit, Premium sits at HKD 100,000, and Professional and Institutional are qualification based or negotiable. None of the four tiers comes with a stated withdrawal fee or cycle of its own in the material we hold, so the payment terms above appear to be firm wide rather than tier specific, so far as we can tell.
One document we did read directly is Huatai International’s website terms, and while it does not touch deposits or withdrawals, it is worth flagging here because it governs how a client’s relationship with the firm can change. Clause Website Information and Terms Amendment (網站資訊與條款修訂) reserves the firm absolute discretion to change any information or material on the website, and the terms of use themselves, without prior warning or notice. A client relying on today’s stated payment timelines or fee treatment has no contractual guarantee those stay put.
We searched 1,441 warning list entries mirrored from CySEC, the FCA, and the FSC Mauritius, and Huatai International appears on none of them. That is a clean result on the lists we cover, though it says nothing about payment handling specifically and covers only those three regulators’ published lists, not every authority that might weigh in on a firm’s money handling.
Why this score moved</h3
Our previous review scored Huatai International 4.1 out of 10; this one scores 5.2. The fees criterion here sits at 3, which is low and reflects a genuine gap: we have no firm published page on deposit or withdrawal costs, only the earlier review’s account of bank fees on wire transfers (unquantified) and a no fee claim on FPS and check deposits that we could not check against Huatai International’s own terms. The overall score moved because this review rests on a different evidence base than the last one, including a live SFC register check and a warning list search that the earlier review did not have, not because anything about the firm’s payment handling has changed.
Customer Support
Huatai International’s contact page lists several direct phone lines rather than a single support number. A general switchboard runs on (852) 3658 6000, which doubles as the fax line. A dedicated customer service hotline is split by market: (86) 400 8818 456 for callers in Mainland China and (852) 3658 6288 for Hong Kong. A separate quick order hotline exists for trade instructions specifically, again split by market: (86) 400 1200 608 for Mainland China and (852) 3658 6138 for Hong Kong. The same page lists an email contact under both a media-enquiries heading and a general securities-service heading, with hkpublicrelations@htsc.com for media enquiries and hkinfo@htsc.com for general securities services.
Where Huatai International actually sits
The contact page gives a physical office at Room 4201, 53/F, 5808-12/F and the whole of floors 62 and 69, The Center, 99 Queen’s Road Central, Hong Kong, alongside the corporate site address www.htsc.com.hk. There is no separate walk-in or branch listing beyond this one Hong Kong address on the page we fetched.
When the phones and chat are staffed
The contact page sets two different windows depending on what a client wants. General office hours run 9:00 AM to 12:00 PM and 1:00 PM to 6:00 PM. Customer service specifically is listed as Monday to Friday, 9:00 AM to 6:00 PM, with the page stating it is closed Saturday, Sunday and public holidays. Our earlier review also described a live chat channel available 9AM-6PM HKT in Chinese and English with a stated response time under five minutes; that detail did not come from a page we fetched ourselves, so we are restating it as something the prior review reported rather than something Huatai International’s own site told us.
What Huatai International’s terms do to a client who has a dispute
The firm’s own terms of use, which we read directly, set several conditions that matter more once something has gone wrong than they do on a normal trading day. Under the Liability (責任) clause, Huatai International disclaims liability, express or implied, for damage, loss or other liability arising from use of the website or reliance on information or opinions on it, including consequential or incidental losses such as lost profits, unless a specific product or service agreement says otherwise. The Indemnification (彌償) clause runs the other way: on request, the client must indemnify Huatai International against legal actions, claims and other liabilities, including the firm’s own legal costs, arising from the client’s use of the website or breach of its terms. Under System Failure (系統故障), the firm states it is not liable under any circumstances for malfunctions, server or connection failures, errors, security issues, viruses, malicious programs or delays connected to a client’s access to or use of the website or online services, even where it had been notified such issues might occur. A client whose complaint stems from a platform outage or a lost order during a system fault has, on the wording of this clause, no recourse against the firm for that failure.
Two further clauses shape how a complaint plays out procedurally. The Website Information and Terms Amendment (網站資訊與條款修訂) clause reserves Huatai International absolute discretion to change the website’s content and its terms of use without prior warning or notice, so the terms a client agreed to at signup are not guaranteed to be the terms in force when a dispute arises. The Jurisdiction (司法管轄權) clause puts access to and use of the website, and the terms of use themselves, under Hong Kong law, with the client agreeing to the non-exclusive jurisdiction of the Hong Kong courts, which is where a complaint that cannot be resolved through the firm’s own channels would end up. The Confidentiality (保密) clause adds that, absent a separate direct contract or a legal requirement, Huatai International owes no duty of confidentiality over information or material a client submits through the website, and the Copyright and Ownership (版權及擁有權) clause has the client granting the firm a worldwide, royalty-free, perpetual licence to use any data or material submitted via the site for any purpose the firm deems appropriate, including reproduction and distribution. None of these clauses are specific to a complaints procedure, but they all bear on what a client who submits documents or evidence through the site in the course of a dispute can expect to happen to that material afterward.
Who the service is offered to
Separately, the same terms state that the website’s information, products and opinions are directed only at persons resident in Hong Kong SAR or businesses based there, and that by continuing to browse, a user represents they are not resident outside Hong Kong and do not intend to purchase or subscribe to the firm’s products or services from outside it. A client contacting support from outside Hong Kong is, per this wording, outside the audience the site is written for in the first place.
Prohibited Countries
Huatai International’s own terms of use, the page we actually read at the firm’s UAE terms page, narrow the intended audience directly rather than listing barred countries. It states that the information, products and opinions on the site are directed only at people resident in Hong Kong SAR or businesses based in Hong Kong, and are not meant for people in any other jurisdiction. By continuing to browse, a visitor is treated as representing that they are not resident outside Hong Kong and do not intend to buy or subscribe to any product or service from outside Hong Kong. That is the only geographic gate this firm’s own published page puts in front of a prospective client: a residency representation extracted by the act of browsing, not a published list of excluded countries.
Which Huatai entity a client actually deals with
The group is not one legal entity. Huatai International Financial Holdings Company Limited is the Hong Kong holding company; the regulated-activity licences from the Securities and Futures Commission sit with its operating subsidiary, Huatai Financial Holdings (Hong Kong) Limited, incorporated in Hong Kong in November 2006, according to the firm’s own about page. The same page describes a separate US entity, Huatai Securities (USA), which obtained a broker-dealer licence in 2019, and a Singapore subsidiary set up in September 2022 that the page says is still in the process of obtaining local licences. Which of these entities actually onboards a given client, and so which regulator and which country’s rules apply to that client, depends on the client’s region, and the public pages we fetched do not spell that routing out for a prospective client outside Hong Kong.
The SFC’s own Public Register of Licensed Persons and Registered Institutions adds a specific correction here: CE reference AOK809 belongs to Huatai Financial Holdings (Hong Kong) Limited, not to “Huatai International Financial Holdings Company Limited” as an earlier version of this review had it. The register shows that licence active for Type 1, Type 2, Type 3, Type 4, Type 6, Type 7 and Type 9 activities, with no public disciplinary action recorded and nine licensing conditions attached. A reader trying to work out whether they can be serviced from outside Hong Kong needs to be dealing with the right entity’s paperwork, and the SFC register names a different one than the earlier review did.
The restricted-country list we could not confirm
An earlier version of this review carried a list of countries said to be off-limits to Huatai International, typically naming Iran, North Korea, Syria and Cuba among others. We are not repeating that list here. The earlier review made the same admission: it could find no connection between that list and anything the firm actually publishes, noting that it had examined htsc.com.hk’s homepage, legal, terms and legal-documents pages, accessed via an Indonesian exit node on 27 July 2026, and found none of them carrying a published restricted-country list. We have not re-run that check ourselves and cannot vouch for it directly, but we are passing on what the earlier review reported rather than repeating a country list with no current source behind it. A reader should not treat their own country’s absence from that old list as confirmation they are accepted; the honest position is that no restricted-country list currently traces to anything this firm publishes on the pages fetched.
What the terms bind a client to instead
Rather than a country list, the terms of use page put the governing-law and dispute-forum question in its “Jurisdiction (司法管轄權)” section: Access to or use of the website and online services, and these terms of use, are governed by and construed according to the law of Hong Kong. The client agrees to submit to the non-exclusive jurisdiction of the Hong Kong courts. Combined with the residency representation described above, a client who is not resident in or based in Hong Kong is, by the terms’ own wording, using a site that was not written with them as the intended audience, and any dispute defaults to Hong Kong law and Hong Kong courts regardless of where that client is actually based.
Set against that, our own warning-list search covering 1,441 entries mirrored from the CYSEC, FCA and FSC Mauritius warning lists returned no match for this firm, run with a positive control against a firm known to be listed so an empty result means absence rather than a broken search. That says nothing about which countries this firm will or won’t onboard; it only says the firm does not appear on the three warning lists we mirror.
Conclusion
Huatai International scores 5.2 out of 10 here, up from the 4.1 this catalogue gave it previously. That move is our assessment, not a change in how the broker operates: this review ran checks the earlier one didn’t have, a direct search of the Hong Kong Securities and Futures Commission register, a warning-list search across three regulators, and a read of the firm’s own terms of use, and those checks land differently than the unverified figures the earlier review worked from.
What the SFC register actually shows about Huatai
The licence number carried over from the earlier review, AOK809 attributed to “Huatai International Financial Holdings Company Limited,” does not check out under that name. The Hong Kong SFC Public Register of Licensed Persons and Registered Institutions shows CE reference AOK809 belongs instead to Huatai Financial Holdings (Hong Kong) Limited, a separate entity within the same group. Under its correct name, the SFC register confirms that licence as active for Type 1, Type 2, Type 3, Type 4, Type 6, Type 7 and Type 9 activities, covering dealing in securities, dealing in futures contracts, leveraged foreign exchange trading, advising on securities, advising on corporate finance, providing automated trading services and asset management, with nine licensing conditions attached and no public disciplinary action on record. That is a real, checkable licence, just not held by the name the earlier review used. We also searched 1,441 warning-list entries mirrored from CYSEC, the FCA and FSC Mauritius, running a positive control first so an empty result means absence rather than a broken search, and Huatai does not appear on any of them. That clean result, and the confirmed licence once matched to the right entity, is most of what moved the regulation reading in this review.
The group behind the licence
Huatai International Financial Holdings Company Limited is the Hong Kong holding company for a group whose parent, Huatai Securities Co., Ltd, is triple-listed: A-shares on the Shanghai Stock Exchange since 26 February 2010, H-shares on the Hong Kong Stock Exchange since 1 June 2015, and GDRs on the London Stock Exchange since 17 June 2019, the first Chinese company listed through the Shanghai-London Stock Connect mechanism. The firm’s own about page states Standard & Poor’s assigned Huatai International a BBB+ long-term and A-2 short-term issuer rating in 2024. The same page describes separate regulated entities by region: the SFC-licensed Hong Kong subsidiary, a US entity that obtained a broker-dealer licence in 2019, and a Singapore subsidiary set up in September 2022 that the firm describes as still obtaining local licences. Which of these a given client actually contracts with, and what protections follow from that, depends on region and which entity onboarded them.
Fees Huatai International doesn’t publish where we could check
Every commission figure, account minimum and promotional credit in this review, the three-month commission-free window on HK and US stock trades, the HKD 500 to 2,000 trading credit tied to deposit size, and the four account tiers running from a $0 minimum up to a negotiable institutional threshold, comes from the earlier published review rather than from a page our review process fetched. We could not verify any of it against Huatai’s own site. The only firm-published, fee-adjacent detail sits in the payments table, also carried over from the earlier review, showing free instant Hong Kong FPS transfers against a two-to-three day bank wire withdrawal with bank fees applying. A fees score of 3 reflects that the pricing a reader would need before opening an account was not something this review confirmed first hand.
Platform, support, and what binds a client
The trading platform, ZhangLe Global, and its mobile, web and API access, is likewise carried over from the earlier review rather than confirmed on Huatai’s own pages this pass. Support fares better on firsthand evidence: the contact page lists a Hong Kong switchboard, separate customer-service and quick-order hotlines for mainland China and Hong Kong, a fax number, and office hours of 9am to 6pm on weekdays, closed weekends and public holidays, and a general securities-service email, hkinfo@htsc.com. Huatai’s own terms of use, read directly, disclaim liability for losses from use of the website or its content, require the client to indemnify the firm for claims tied to the client’s own use of the site, permit Huatai to force-close margin positions without notice once maintenance levels are breached, and place disputes under Hong Kong law and the non-exclusive jurisdiction of Hong Kong courts, while reserving the right to change the terms themselves without warning.
Huatai International holds a genuine, active Hong Kong SFC licence once matched to its Huatai Financial Holdings (Hong Kong) Limited entity, and a clean result across three mirrored warning lists, but its fees and platform details still rest on an earlier review our review process could not independently confirm. Huatai International scores 5.2 out of 10.
What we saw
Pages captured from Huatai International’s own site when this review was written. Brokers change their terms; these are what we read.
Score history
Recomputed daily; every move is on the record. The current score is always the latest row.
| Date | Score | Move |
|---|---|---|
| 2026-09-29 | 5.2 | ▲ |
| 2026-07-25 | 4.1 | ▼ |
| 2026-07-18 | 4.2 | ▼ |
| 2026-07-11 | 4.4 | · |
FAQ
Is Huatai International regulated?
Yes. SFC licence AOK809 is confirmed on the Hong Kong register, held by Huatai Financial Holdings (Hong Kong) Limited, a subsidiary in the group.
Who owns Huatai International?
Huatai Securities Co., Ltd, founded in 1991 and listed in Shanghai, Hong Kong and London.
What is the minimum deposit at Huatai International?
Our earlier review reported $0 for the Standard Account. The firm’s own pages do not confirm that figure.
What trading platform does Huatai International use?
Our earlier review describes ZhangLe Global (漲樂全球通) on mobile, web and API. We did not confirm it on the firm’s own pages.
How can I contact Huatai International?
By phone, fax and live chat, staffed 9:00 to 12:00 and 13:00 to 18:00, with separate hotlines for Hong Kong and Mainland China.
How this review works
Track Huatai International live: score moves and red notices, in your pocket.