STOCK · CHECKED 12 OCT 2026
SPDB International review.
Hong Kong securities arm of SPD Bank, with three SFC-licensed entities and few published fees
RISKY
OUT OF 10
SPDB International is the Hong Kong arm of Shanghai Pudong Development Bank. Three of its subsidiaries hold active SFC licences (BKW389, BFY108, BFZ375), all confirmed on the register with no disciplinary record. It offers a mobile app, a desktop application and web trading, and Hong Kong clients activate an account with HKD 10,000. The main reservation is cost: beyond a HKD 100 IPO handling fee, its commission schedule was not available to read.
Each criterion is scored 1 to 10 from primary sources. The overall score is their unweighted mean. How scoring works.
| Founded | 2015 |
|---|---|
| Headquarters | HK |
| Minimum deposit | HKD 10,000 |
| Account opening | 1-3 |
| Platforms | 浦银财富通 (mobile app), 电脑应用程式 (desktop application), 互联网交易 (internet/web trading platform) |
- Three SFC licences confirmed on the register: BKW389, BFY108 and BFZ375
- No public disciplinary action recorded against any of the three entities
- Own mobile app, desktop application and web trading login
- Account activation from HKD 10,000 for Hong Kong clients
- Not on the CySEC, FCA or FSC Mauritius warning lists we searched
- Commission schedule and ongoing account fees were not available to read
- Support is split across several phone lines and two email addresses, with no response times stated
- Impersonators use the SPDBI name, and the firm's own site carries a fraud warning
- A claimed HKEX exchange participant status could not be checked
- No Trustpilot profile found for spdbi.com
Overview
TrueBroker is a free broker safety checker, and this page is our review of SPDB International, scored 5.2 out of 10 across regulation, fees, platform, support and reviews. Our previous review of this firm scored 4.2/10; this rewrite scores it 5.2/10, and the move is ours, not the firm’s: this pass checked the Hong Kong SFC register directly and found three separately licensed subsidiaries with active status, and it found the firm’s own site publishing a mobile app, a desktop application and a web trading login, which raised the regulation score to 7.4 and the platform score to 7.4. Fees (3), support (3.8) and reviews (4.4) stay low because the evidence for them is thin or absent.
“SPDB International” is not one licensed entity but a group. SPDB International Holdings Limited (SPDBI) is the Hong Kong holding company, and its parent is Shanghai Pudong Development Bank Co., Ltd. (SPD Bank), the Mainland Chinese bank. Underneath SPDBI sit three subsidiaries we could match to the Hong Kong Securities and Futures Commission (SFC) register by CE reference: SPDB International Securities Limited (CE BKW389, Type 1 and Type 4, dealing in and advising on securities), SPDB International Investment Management Limited (CE BFY108, Type 4 and Type 9, advising on securities and asset management), and SPDB International Capital Limited (CE BFZ375, Type 1 and Type 6, dealing in securities and advising on corporate finance). The SFC register shows all three as active and records no public disciplinary action against any of them. A fourth licence claim carried over from an earlier review, describing an unnamed “parent entity” with no CE reference, could not be matched to a single register entry, so we are not carrying it forward as confirmed; that is a gap in the claim, not a finding about the firm. We also could not check a claimed Stock Exchange of Hong Kong (HKEX) registration or a Shanghai ICP filing (沪ICP备05022859号-12) against any register we hold, for the same reason.
Overview Table
| Headquarters | 33/F, SPD Bank Tower, One Hennessy, 1 Hennessy Road, Hong Kong |
|---|---|
| Established | Not stated |
| Countries Served | Not fully stated; the online account-opening flow is built for Mainland China and Hong Kong individual clients, and our evidence drew separate contact and warning pages for an Australia site and an Indonesia site |
| Regulated By | Hong Kong Securities and Futures Commission (SFC), across three separately licensed subsidiaries (CE BKW389, BFY108, BFZ375) |
| Minimum Deposit | HKD 10,000 (Hong Kong client account activation deposit) |
| Maximum Leverage | Not stated (Professional Investor Account terms mention “negotiated leverage” with no figure given) |
| Total Instruments | Not stated as a count; categories on the firm’s pages include Hong Kong equities, Mainland A-shares via Stock Connect, funds, bonds, ETPs and REITs |
| Platforms | SPDB Wealth mobile app (浦银财富通), desktop application (电脑应用程式), web trading login (互联网交易) |
| Customer Support | Email (cs@spdbi.com, enquiry@spdbi.com); phone lines for the securities division, other divisions and a Mainland China division |
| Languages | Simplified and Traditional Chinese (stated for the desktop application) |
Facts List
- SPDB International Securities Limited holds SFC CE reference BKW389 for Type 1 and Type 4 activities, shown active with no recorded disciplinary action.
- SPDB International Investment Management Limited holds SFC CE reference BFY108 for Type 4 and Type 9 activities, shown active with no recorded disciplinary action.
- SPDB International Capital Limited holds SFC CE reference BFZ375 for Type 1 and Type 6 activities, shown active with no recorded disciplinary action.
- We searched 1,441 warning-list entries mirrored from CYSEC, the FCA and the FSC Mauritius, and this firm appears on none of them; that check covers only the lists we mirror, not every regulator.
- The firm’s account-opening guide states a Hong Kong client account is activated only once a deposit of not less than HKD 10,000, sent from a Hong Kong-licensed bank account in the client’s own name, is confirmed.
- The firm’s fee page states a new-share (IPO) subscription handling fee of HKD 100, applying whether the client subscribes by cash or by margin financing, and describes financing of up to 90% of the subscription amount.
- The account-opening guide states that clients with no prior derivatives experience, and no documented self-education on derivatives recorded in the risk questionnaire, cannot have derivatives trading enabled on their account.
- The firm’s securities page states that odd-lot (碎股) trading is available only by telephone order through the client’s assigned relationship manager, not through the online platforms.
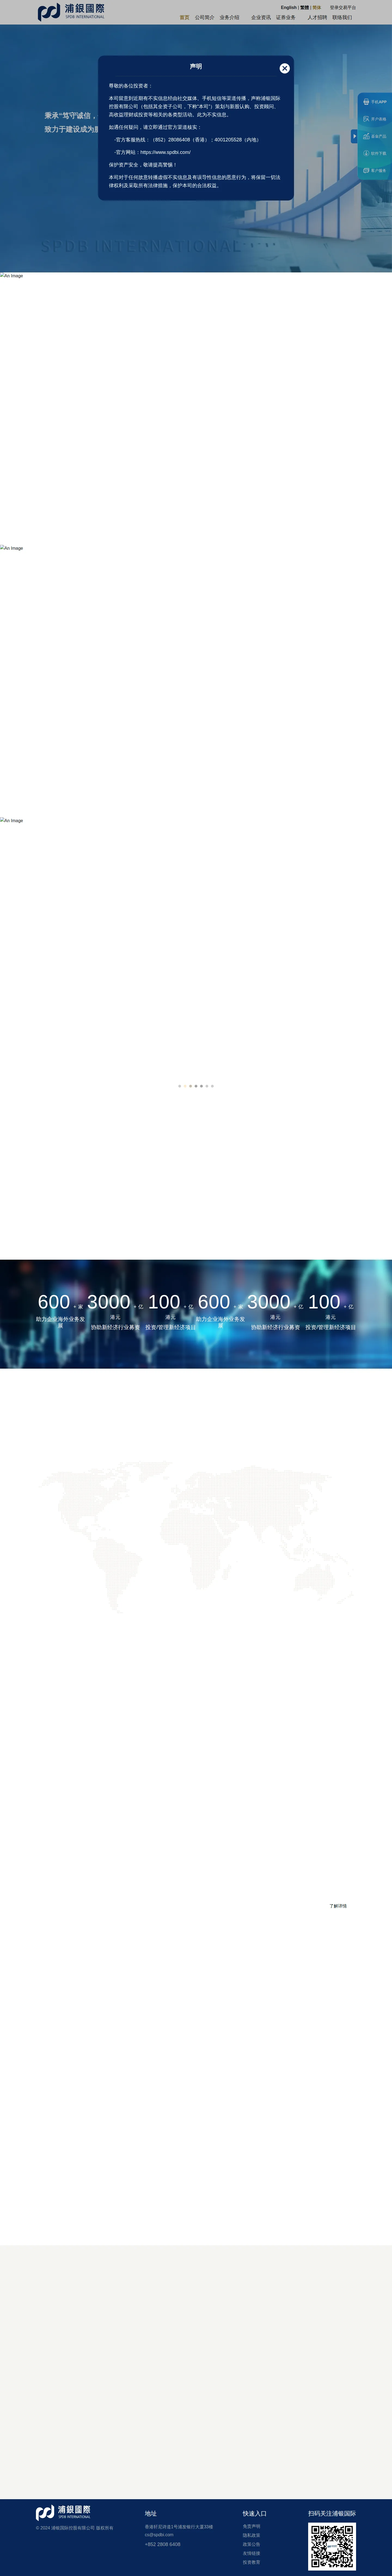
- SPDBI’s own site carries a fraud warning stating that false information has circulated via social media and SMS claiming to be SPDBI activity on new share subscriptions, advisory or wealth management, and directs readers to verify via its official hotlines and website.
- A Shanghai ICP filing number (沪ICP备05022859号-12) appears on the firm’s site; this is a website registration, not a financial-services licence, and we hold no register to check it against.
What SPDB International actually publishes, versus what the earlier review claimed
Our earlier review asserted that the genuine SPDBI runs no trading platform or app of any kind, and used that absence as a test for spotting clone firms. Reading the firm’s own pages directly, we found the opposite: a web trading login (“登录交易平台”), a branded mobile app (浦银财富通) on the Apple App Store, Google Play and as a standalone APK for Mainland Android, and a downloadable desktop application in both Simplified and Traditional Chinese. A reader who applied the earlier review’s “no platform means legitimate” test to SPDBI’s own website would draw the wrong conclusion. This gap between the earlier claim and what we could read first-hand is the main reason the platform and regulation scores moved between our two reviews of this firm; it reflects a correction in our own assessment, not any change at the firm.
Where SPD Bank’s oversight stops
The earlier review reported that Hong Kong Monetary Authority oversight attaches to the Mainland parent, Shanghai Pudong Development Bank, as a bank regulator, separately from the SFC’s oversight of SPDBI’s own Hong Kong securities, asset-management and corporate-finance subsidiaries. We did not read a document confirming this ourselves, so we are restating it as what the earlier review reported rather than as a fact drawn from the firm’s own pages.
Key Takeaways
The SFC licences behind SPDB International
- The Hong Kong SFC Public Register of Licensed Persons and Registered Institutions confirms three separate operating subsidiaries, each with an active licence and no recorded disciplinary action: SPDB International Securities Limited under CE reference BKW389, licensed for Type 1 (Dealing in Securities) and Type 4 (Advising on Securities); SPDB International Investment Management Limited under BFY108, licensed for Type 4 (Advising on Securities) and Type 9 (Asset Management); and SPDB International Capital Limited under BFZ375, licensed for Type 1 (Dealing in Securities) and Type 6 (Advising on Corporate Finance).
- The firm’s own securities page states the same Type 1/Type 4 activities for the securities arm, which matches what the SFC register shows for BKW389.
- Before treating any of this as confirmed, we ran a positive control on all four SFC lookups, checking a firm already known to be listed, so a clean or empty result reflects the register and not a broken search on our end.
What the register could not settle
- One licence claim in the material we reviewed names no CE reference and describes the licence holder only as “the parent entity,” without making clear whether that means SPDBI or SPD Bank itself. The SFC’s name search returned no single corporation matching that description, so this claim is unchecked. That is a gap in the claim or in our matching, not a finding about the firm.
- A claim that SPDB International Securities Limited is a registered HKEX exchange participant also carries no licence number, and we hold no register entry for the Stock Exchange of Hong Kong to check it against, so it is unchecked.
- The Shanghai ICP filing number quoted on the firm’s own FAQ page, 沪ICP备05022859号-12, is a website registration rather than a financial licence, and we hold no register for that authority either, so it is likewise unchecked.
Warning-list search
We searched 1,441 warning-list entries mirrored from CySEC, the FCA and the FSC Mauritius, and SPDB International appears on none of them. That covers only the three lists we mirror, not every regulator worldwide, but it is a clean result worth recording on its own terms.
What SPDB International charges
- The firm’s securities page sets a new-share (IPO) subscription handling fee of HKD 100, charged whether the client subscribes in cash or through margin financing, with financing available up to a 90% ratio of the total subscription amount.
- Its account-opening guide requires a minimum activation deposit of not less than HKD 10,000 for Hong Kong clients, transferred in the client’s own name from a Hong Kong-licensed bank account to SPDBI’s client funds deposit account; the account activates only once that deposit is confirmed.
- Beyond these three figures, the standard commission schedule, spreads and ongoing account fees were not available to us: several fee, account and terms pages across the geo variants of the site failed to render in this crawl, so most of what a trading fee comparison would need was simply not there to read.
The platforms it actually publishes
- The firm’s own pages describe three access routes: a mobile app, Puyin Caifu Tong (浦银财富通), on the Apple App Store, Google Play for Hong Kong/overseas, and a standalone APK for Mainland Android; a downloadable desktop application in both Simplified and Traditional Chinese; and a web login, “log in to trading platform” (登录交易平台), used to place Hong Kong stock orders and reset passwords.
- Our earlier review asserted that the genuine SPDBI runs no trading platform or app of any kind, and used that absence as a test for spotting clone firms. The firm’s own pages describe an app, a desktop client and a web login, which does not match that description.
- Separately, SPDBI’s own site carries a fraud warning about false information circulated via social media and SMS impersonating SPDBI on new-share subscriptions, investment advisory and wealth management, directing users to verify through the firm’s official hotlines and website. That is the firm’s own acknowledgment that impersonation is a live risk, independent of the platform question above.
Support and the terms that bind a client
- Published contact points are a securities-division phone line, a separate Mainland China phone line, two email addresses (cs@spdbi.com and enquiry@spdbi.com), and a Hong Kong office address; there is no live chat or stated response-time commitment in what we read.
- The account-opening flow requires a FATCA tax-residency declaration; if a client is identified as a US person or holds a US beneficial interest, their account data may be reported to the US Internal Revenue Service.
- A client with no prior derivatives experience and no documented self-education on derivatives, as recorded in the risk questionnaire, will not have derivatives trading enabled, regardless of stated wealth.
- Odd-lot trading is only available by phone through the client’s assigned relationship manager, not through either the app, the desktop application or the web platform.
The score move, 4.2 to 5.2
This review scores SPDB International 5.2/10, up from our previous 4.2/10. That change reflects this review’s assessment against the evidence gathered now, not a claim that the firm’s licensing or charges have changed since the last review. Regulation lands at 7.4 on the strength of three separate active SFC licences with no disciplinary record between them. Platform lands at 7.4 because the firm’s own pages show an actual app, desktop client and web login, contradicting our earlier review’s no-platform test. Fees stay weak at 3 because most of the standard fee schedule pages did not render for us and only three isolated figures were available. Support sits at 3.8 on a plain list of phone and email contacts with no stated service commitments, and reviews sits at 4.4, weighed down by an source from our earlier review whose central platform claim does not match what the firm’s own site shows.
Licenses & Regulation
SPDB International’s regulatory footprint sits in Hong Kong, split across three separately licensed subsidiaries of the same holding group. We checked all three against the SFC’s own register, and every licensed activity on them shows as active. Unlike BOCOM International, which we also review and whose futures company on the same register lists no current activities, SPDB International has no dormant licence in its structure.
What the SFC register shows for SPDB International
SPDB International Securities Limited holds CE reference BKW389 on the Hong Kong Securities and Futures Commission’s Public Register of Licensed Persons and Registered Institutions, licensed for Type 1 (dealing in securities) and Type 4 (advising on securities), both shown as active, with no public disciplinary action recorded against it. This is the entity whose own website we read for the firm’s fee and platform detail, and it is the one HKEX-facing brokerage a reader opening an account through spdbi.com’s securities pages would actually be dealing with.
Two related entities carry their own separate SFC licences. SPDB International Investment Management Limited holds CE reference BFY108, licensed for Type 4 and Type 9 (advising on securities; asset management), active, no public disciplinary action recorded. SPDB International Capital Limited holds CE reference BFZ375, licensed for Type 1 and Type 6 (dealing in securities; advising on corporate finance), active, no public disciplinary action recorded. All three checks came from the SFC register directly, and we ran a positive control against the same register first, searching for a firm known to be listed, so an active result here means the register actually returned one rather than the search silently failing.
A fourth licensing claim in our source material, describing licences for corporate finance advice, securities advice and asset management dated 30 December 2015 and attributed to “the parent entity,” named no CE reference and no single corporation the SFC’s name search could match. That is a gap in the claim itself, not a finding about the firm, and we are not treating it as either confirmed or a black mark.
What sits outside the SFC’s remit
The group’s structure separates a Hong Kong-licensed securities and asset management business from a Mainland Chinese banking parent, Shanghai Pudong Development Bank Co., Ltd. (SPD Bank). Our earlier review described the Hong Kong Monetary Authority as providing additional oversight of that parent bank, separate from the SFC’s oversight of the Hong Kong securities and asset management subsidiaries; we have not verified this against the HKMA’s own register, so we report it as what the earlier review said rather than as something we confirmed. A registered exchange participant status with the Stock Exchange of Hong Kong for SPDB International Securities Limited was raised the same way, again unverified against HKEX’s own listing and carrying no licence number to check. Separately, the firm’s site carries a Shanghai ICP filing (沪ICP备05022859号-12) for the holding company; that is a website registration with Chinese internet authorities, not a financial-services licence, and we have not checked it against any register.
Warning-list and clone-firm exposure
We searched 1,441 warning-list entries mirrored from CySEC, the FCA and the FSC Mauritius, and SPDB International appears on none of them. That covers only the three regulators we mirror, not a global sweep, but it is a clean result worth stating plainly. More notable is that SPDB International’s own homepage carries a fraud warning of its own: it states that false information has circulated via social media and SMS claiming to represent SPDBI-related activity on new share subscriptions, investment advisory, or high-yield wealth management, and it directs users to verify via the firm’s official hotlines and website. That is the firm itself flagging clone-firm impersonation as a live risk, from its own published page rather than from any third party.
Separately, our earlier review asserted that the genuine SPDBI runs no proprietary trading platform, no MetaTrader support, and no mobile or web trading interface, treating any such platform as proof of impersonation. That does not match what SPDBI’s own pages show: the firm’s site includes a login for its own trading platform, a branded mobile app, Puyin Caifutong (浦银财富通), distributed on the Apple App Store, Google Play, and as a standalone APK for Mainland Android, and a downloadable desktop application. A reader relying on the earlier review’s test would misjudge the firm’s own site as a clone.
What we could not check
Several pages that would normally carry account, fee, risk-disclosure and terms detail did not render in our crawl of this firm’s non-Hong Kong regional pages. Claims drawn from the earlier review, including the HKD 8 million professional-investor portfolio threshold and negotiated leverage and commission terms, could not be cross-checked against the firm’s own account or terms pages on this pass.
Our previous score for this firm was 4.2 out of 10; this review scores it 5.2. Regulation is the strongest of the five criteria we score here, at 7.4, and that is carried by three separate active SFC licences confirmed directly against the register plus a clean result across the three mirrored warning lists, set against fees, support and reviews scores that remain low. We are restating the regulation picture from what the SFC register and the firm’s own pages show now, not describing any change at the firm.
How to Trade
SPDBI’s own securities pages describe an online trading login (“登录交易平台”), a branded mobile app called Puyin Caifutong (浦银财富通), available on the Apple App Store, Google Play, and as a standalone APK for Mainland China Android, plus a downloadable desktop application in both Simplified and Traditional Chinese. That matters here because the earlier review this catalogue previously relied on claimed the genuine SPDBI runs no trading platform or app of any kind, and used that absence as its test for spotting clone firms. The firm’s own site contradicts that description directly: a reader applying our earlier review’s test to SPDBI’s real pages would flag the genuine site as suspicious. We report this as a correction to what the material from our earlier review claimed, not as a judgment on trading conditions.
What SPDB International lists for instruments
The firm’s business pages describe Hong Kong equities (香港股票) traded on HKEX through its own platforms, Stock Connect access to eligible Mainland China A-shares via the Shanghai and Shenzhen Hong Kong Stock Connect programmes (沪股通、深股通), resale of third-party fund houses’ products across asset classes and global markets (基金), and buy/sell dealing in bonds (债券) including high-grade issues across a range of tenors and currencies aimed at medium- to long-term investors. Our earlier review also lists Exchange Traded Products and REITs as part of the securities brokerage offering alongside equities on HKEX; we have not independently confirmed those two from the firm’s own pages in our evidence, so we flag them as carried over rather than freshly read.
How an order actually gets placed
Standard Hong Kong stock orders go through SPDBI’s own channels: the internet trading login reached via “登录交易平台” on the site, the 浦银财富通 mobile app, or the desktop application. One order type sits outside that self-directed flow entirely: the firm’s own business page states that odd-lot (碎股) trading is available only by telephone order through the client’s assigned relationship manager, not through the online platforms. A client trading odd lots is therefore routed to a person, not a screen, regardless of which app or terminal they otherwise use.
New share subscriptions and financing
For IPO subscriptions, the firm’s business page sets a new share (IPO) subscription handling fee of HKD 100, charged whether the client subscribes with cash or through margin financing. The same page describes IPO subscription financing of up to a 90% financing ratio, meaning the loan amount can reach 90% of the total subscription amount, pitched as a way to increase allotment chances. Neither the loan’s cost (interest rate) nor its repayment terms appear in the material we fetched.
Account types and what gates access
During the online account-opening flow, Mainland and Hong Kong individual clients select between a margin account (保证金账户) and a cash account (现金账户); the firm’s page describing this step does not give a minimum deposit for either. Separately, our earlier review describes a Professional Investor Account requiring a portfolio of at least HKD 8 million for individuals, or a portfolio of HKD 8 million or total assets of HKD 40 million for corporations, with negotiated leverage and commission; we could not check that tier against the firm’s own account or fee pages, since our evidence’s failure log records that several account and fee pages for our evidence did not render on the crawl, so this figure is repeated from the earlier review rather than confirmed here.
Access to derivatives trading is gated by a risk questionnaire completed during account opening: the firm’s account-opening guide states that clients with no prior derivatives investment experience who have not completed self-directed education on derivatives, as recorded in that questionnaire, will not have derivatives trading enabled on their account. Wealth alone does not appear to override this; the gate is tied to declared experience and education, not portfolio size.
Funding the account
For Hong Kong clients, the account-opening guide requires an activation deposit of not less than HKD 10,000, transferred in the client’s own name from an account at a Hong Kong-licensed bank to SPDBI’s client funds deposit bank account. The account is only activated once that specific deposit is confirmed, so the transfer’s source account and the name on it are checked before the account goes live, not just the amount.
Regulatory standing behind the trading entities
We searched the Hong Kong SFC’s Public Register of Licensed Persons and Registered Institutions directly and confirmed three of the group’s operating entities there: SPDB International Securities Limited holds CE reference BKW389, licensed for Type 1 and Type 4 regulated activities (dealing in securities; advising on securities), both shown active with no public disciplinary action recorded. SPDB International Investment Management Limited holds CE reference BFY108 (Type 4 and Type 9: advising on securities; asset management), also active with no public disciplinary action recorded, and SPDB International Capital Limited holds CE reference BFZ375 (Type 1 and Type 6: dealing in securities; advising on corporate finance), likewise active with no public disciplinary action recorded. A fourth licence our earlier review attributed to an unnamed “parent entity” quoted no CE reference and the SFC register’s name search returned no single matching corporation, so that one is unchecked; it is a gap in the claim we were given, not a finding about the firm. We also checked this firm’s name against 1,441 warning-list entries mirrored from CYSEC, the FCA and the FSC Mauritius, and it appears on none of them.
Our previous review of this broker scored 5.2 overall, revised from 4.2. That move reflects this review’s own assessment against current evidence, not a change in the firm; regulation now scores 7.4 on the strength of the three confirmed SFC licences above, none of which carry any disciplinary flag on the register, while fees stays at 3 because the material we could actually fetch covers a narrow set of specific charges (the HKD 100 IPO handling fee, the 90% financing ratio, the HKD 10,000 activation deposit) without the account and fee pages needed to see the fuller cost picture.
Account Types
SPDB International sells access through two distinct routes: an online, self-directed account opened by individuals in Hong Kong or Mainland China, and a negotiated, high-minimum Professional Investor Account aimed at wealthy clients. The firm’s own account-opening pages describe the first route; the second comes only from our earlier review and we could not check it against SPDBI’s own current pages because several of the firm’s account and fee pages failed to load during this crawl, per our evidence’s failures log.
Two ways in: self-directed accounts and the Professional Investor tier
SPDB International’s online account-opening flow, aimed at Mainland and Hong Kong individual clients, has the applicant choose between a cash account (现金账户) and a margin account (保证金账户) as part of signing up. That page does not give a minimum deposit figure for either choice.
Our earlier review reported a separate Professional Investor Account, pitched at individuals with a securities and cash portfolio of at least HKD 8 million, or at corporations with a portfolio of HKD 8 million or total assets of HKD 40 million. The same source described that tier as carrying negotiated leverage, negotiated commission and a dedicated relationship manager rather than published rates. We restate that as what the earlier review found, not as something SPDBI’s own pages currently show us: the account and fee pages that would confirm or update those figures did not render on this crawl.
What SPDB International charges to open and fund an account
SPDBI’s own account-opening guide sets a Hong Kong activation deposit of not less than HKD 10,000, which has to be wired from an account in the client’s own name at a Hong Kong-licensed bank into SPDBI’s client funds deposit bank account. The account is only switched on once that transfer is confirmed, so a client cannot trade on the strength of a pending wire.
Once an account is open, the firm’s securities business page sets a flat HKD 100 handling fee for subscribing to a new share (IPO) offer, charged the same whether the client pays cash or uses margin financing for the subscription. The same page describes IPO subscription financing of up to 90% of the total subscription amount, sold as a way to raise the odds of getting an allotment rather than as a cost figure in its own right; SPDBI does not publish, on the pages we read, what that financing costs to draw down.
What an account can actually trade
Two conditions in the account-opening flow gate what a live account can do. SPDBI’s risk questionnaire records whether a client has prior derivatives experience or has completed the firm’s self-directed education on derivatives; without one of those on file, the firm does not activate derivatives trading on that account, regardless of how much the client deposits. Separately, the securities business page states that odd-lot (碎股) trades are not available through SPDBI’s online platforms at all and have to be placed by phone through the client’s assigned relationship manager.
Where this leaves the score
Our previous review of SPDB International scored it 4.2 out of 10; this review scores it 5.2. That move is ours, set by a rescoring against current evidence rather than any change at the firm. On the regulation side, the Hong Kong SFC register confirms active Type 1 and Type 4 licences for SPDB International Securities Limited under CE reference BKW389, and the firm does not appear on any of the 1,441 warning-list entries we mirror from CYSEC, the FCA and the FSC Mauritius. Against that, the fee and account material available to us stays thin: activation deposit and IPO handling fees are published, but the commission, spread and financing-rate figures that would let a prospective client actually price a trade are not on the pages we could read, and the Professional Investor Account’s terms come to us only secondhand. That gap is the main reason the fee score sits low despite the regulatory confirmation.
Negative Balance Protection
SPDB International’s own products page lists securities services and no leveraged CFDs, so the usual retail negative-balance question, what happens when a margin call is missed and a position runs into debit, has to be answered from what the firm’s own pages actually publish about margin, financing and account terms, rather than from a template protection clause. On that measure the pages we fetched give us fragments, not a policy.
Margin and financing exposure we did find
SPDB International’s online account-opening flow lets a Mainland or Hong Kong individual client choose between a margin account (保证金账户) and a cash account (现金账户) at the point of opening, according to the account-opening guide page. The same guide does not carry the margin account’s collateral, call or close-out terms on that page.
The firm’s securities business page describes IPO subscription financing of up to 90% of the total subscription amount, sold as a way to increase allotment chances, alongside a flat HKD 100 handling fee for a new share subscription whether paid by cash or by margin financing. Financing 90% of a subscription is itself a leverage exposure, but the page that states the ratio does not go on to describe what happens if the stock allots and falls, or if the client cannot cover the financed portion.
An earlier review of this firm, which we are restating here rather than re-verifying against SPDB International’s own pages, described a Professional Investor Account with negotiated leverage and negotiated commission, open to individuals with a securities and cash portfolio of at least HKD 8 million, or to corporations with a portfolio of HKD 8 million or total assets of HKD 40 million. That same earlier review is the only source we have for the account’s leverage terms; we did not find an SPDB International account-tier or fee page that confirmed or described them.
What SPDB International’s own terms don’t tell us here
The account-opening guide does gate one product on risk profile: a client with no prior derivatives experience, and no documented self-education on derivatives recorded in the risk questionnaire, will not have derivatives trading enabled on their account. That is a restriction on who can trade derivatives at all, not a rule about what happens to an open position that moves against a client, so it doesn’t answer the negative-balance question either.
A Customer Agreement (客户协议), stated as effective from 20 December 2024, is listed as a downloadable form on SPDB International’s forms page, but only its existence and effective date are published there; the clause text itself, including whatever it says about margin calls, forced liquidation, debit balances or client liability for a shortfall, is not shown on that page and we have not read it.
More broadly, our evidence’s own failures log records that several pages which would normally carry this detail, including fee, account, risk-disclosure and terms-and-conditions pages across multiple regional versions of the site, failed to render for our evidence. We can’t quote a negative-balance or margin-call clause from a page we could not read, and a missing page is a gap in what we fetched, not a finding about what SPDB International does or doesn’t promise its clients.
The activation deposit, for context
Separately from margin terms, SPDB International’s Hong Kong account-opening guide requires a client funds deposit of not less than HKD 10,000, transferred in the client’s own name from a Hong Kong-licensed bank account to SPDB International’s client funds deposit account, before the account is activated. That’s an opening threshold, not a loss limit, but it’s the only hard figure on client money the guide itself discloses.
Taken together, what SPDB International’s own pages give us is evidence that leveraged products exist, margin accounts, IPO financing up to 90%, negotiated leverage for large portfolios, without the accompanying pages on what happens when that leverage moves against a client. Anyone opening a margin or Professional Investor account here would need to ask for the Customer Agreement’s actual clauses on margin calls, forced liquidation and debit-balance liability before relying on the account-opening pages alone.
Trading Instruments
SPDB International’s securities arm publishes an actual list of what a client can trade through it, and the list is unusually specific about mechanics as well as tickers. The firm’s own products page describes Hong Kong equities (香港股票) traded on HKEX through its trading platforms, plus Shanghai/Shenzhen-Hong Kong Stock Connect access (沪股通、深股通) to eligible Mainland China A-shares. The same page lists funds (基金), described as resale of third-party fund houses’ products across asset classes and global markets, and bonds (债券), described as buy/sell of high-grade issues across tenors and currencies aimed at medium- to long-term investors. An earlier review of the firm, which we are restating rather than quoting, also listed exchange-traded products and REITs as part of the HKEX securities brokerage offering; we have not read a page of the firm’s own that confirms this, so treat it as the earlier review’s account rather than SPDBI’s.
New share subscriptions at SPDB International
The firm’s business page sets out IPO mechanics in more detail than most brokers publish: a HKD 100 handling fee applies to new share (IPO) subscriptions whether the client subscribes by cash or by margin financing, and the firm offers financing of up to 90% of the total subscription amount specifically to increase allotment chances. Neither the interest rate on that financing nor its term is in the material we fetched.
Stock Connect and the A-shares gap
The Stock Connect access is worth reading carefully rather than skimming past. It is described on the firm’s products page as access to “eligible” A-shares, not the full Shanghai and Shenzhen boards, which is how Stock Connect actually works everywhere it is offered; SPDBI is not unusual here, but the eligibility limit is real and matters to anyone assuming they can buy any Mainland-listed name through this route.
What we could not check against SPDBI’s own pages
A number of pages that would normally carry account, fee, and product detail for other markets, listed in our evidence’s failures log as covering the gb, ae, id and au regions, did not return usable text on this crawl. That means the Professional Investor account’s HKD 8 million portfolio threshold, and the claim that this tier carries negotiated leverage and negotiated commission with full institutional research access, come from the earlier review rather than from a page of SPDBI’s own that we read; we could not cross-check them. The account-opening guide we did fetch shows a second axis entirely: Mainland and Hong Kong individual clients opening online select between a margin account (保证金账户) and a cash account (现金账户), with no minimum deposit figure attached to either in that flow.
Gating that limits who can actually trade what
The account-opening guide describes a real restriction on derivatives access: clients with no prior derivatives investment experience who have not completed self-directed education on derivatives, as recorded in the risk questionnaire, cannot have derivatives trading enabled on their account. This sits alongside a separate restriction on execution itself: odd-lot (碎股) trading is available only by telephone order through the client’s assigned relationship manager, not through either of the firm’s online platforms.
Platform access for the instruments on offer
Trading these instruments runs through three channels the firm’s own pages describe: an internet trading login reached via “Log In to Trading Platform” (登录交易平台) on the site, a branded mobile app (浦银财富通) on the Apple App Store, Google Play for Hong Kong and overseas users, and as a standalone APK for Mainland China Android, and a downloadable desktop application offered in both Simplified and Traditional Chinese. This is worth stating plainly because our earlier review asserted the opposite: that the genuine SPDBI runs no trading platform or app of any kind, using any online platform as a marker of a clone-firm scam. SPDBI’s own pages contradict that description of SPDBI itself, whatever value the test has for spotting impersonators. Separately, SPDBI’s own homepage does carry a fraud warning about false information circulated via social media and SMS claiming to be SPDBI activity around new share subscriptions, investment advisory, or high-yield wealth management, and it directs users to verify through the official hotlines and site rather than through whatever channel the message arrived on.
Our previous score for this broker was 4.2 out of 10; this review scores it 5.2 out of 10. That change reflects this review’s own assessment against the current criteria, not any change at the firm. The regulation score of 7.4 is carried by three confirmed SFC entries, for SPDB International Securities Limited (BKW389, Type 1 and Type 4), SPDB International Investment Management Limited (BFY108, Type 4 and Type 9) and SPDB International Capital Limited (BFZ375, Type 1 and Type 6), each active with no public disciplinary action recorded, plus a clean result against the 1,441 warning-list entries we mirror from CYSEC, the FCA and the FSC Mauritius. The fees score of 3, and the reviews score of 4.4, sit against the asset picture above: what we could verify came from the securities business page and the account-opening guide, not from the account-tier and fee pages that failed to render for our evidence.
Education & Analysis
Our previous review scored SPDB International 4.2 out of 10 overall; this review scores it 5.2, with platform assessed at 7.4. That movement is our assessment, not a change at the firm: it reflects current evidence, including firm pages our review process fetched directly, set against an earlier published review that reached different conclusions about what SPDBI runs.
What SPDB International’s own pages show
The firm’s customer-service pages describe three ways clients reach the market: a mobile app called Puyin Caifutong (浦银财富通), distributed on the Apple App Store, on Google Play for Hong Kong and overseas users, and as a standalone APK for Mainland China Android devices; a downloadable desktop application, offered in both Simplified and Traditional Chinese; and a web login reached through a “Log In to Trading Platform (登录交易平台)” link on the site, which the firm’s FAQ page describes as used for placing Hong Kong stock orders and resetting login passwords. The mobile app is described as covering quotes, account enquiry and Hong Kong stock trading.
Where our earlier review and SPDBI’s own pages disagree
Our earlier review asserted that the genuine SPDBI runs no trading platform or app of any kind, and treated the presence of any online trading platform as a sign of a clone-firm scam. The pages we fetched directly from the firm’s own site describe an online trading login, a branded mobile app on two app stores plus an Android APK, and a downloadable desktop application in two Chinese scripts. A reader applying our earlier review’s test literally would misjudge SPDBI’s own website. Separately, and worth reporting because it comes from the firm’s own page rather than a third party, SPDBI’s homepage carries a fraud warning stating that false information has circulated via social media and SMS claiming to be SPDBI-related activity on new share subscriptions, investment advisory or high-yield wealth management, and it directs users to verify through the official hotlines (852)28086408 / 4001205528 and the site spdbi.com. So clone-firm impersonation of SPDBI is something the firm itself acknowledges as live, even though its own platforms are not the fictional set our earlier review described.
What can be traded through these platforms
The firm’s business page describes Hong Kong equities traded on HKEX through its trading platforms, and its products page describes access to eligible Mainland China A-shares through the Shanghai and Shenzhen Stock Connect schemes (沪股通, 深股通). The business page also describes resale of third-party funds across asset classes and global markets, and trading in bonds including high-grade issues across tenors and currencies aimed at medium- to long-term investors. Our earlier review additionally listed Exchange Traded Products and REITs as part of the securities brokerage offering on HKEX; we have not independently confirmed those two from a page we fetched.
Access is not uniform across order types or account tiers
The business page states that odd-lot (碎股) trading is available only by telephone order through a client’s assigned relationship manager, not through the online platforms described above, so the web login, app and desktop software do not cover that order type. On the account side, our earlier review describes a Professional Investor Account, gated at an HKD 8 million portfolio for individuals or a portfolio of HKD 8 million or total assets of HKD 40 million for corporations, as running on negotiated leverage, institutional pricing and a dedicated relationship manager rather than the self-directed platform access described for other clients; institutional research access is included. We could not cross-check that account tier against a fee or account page fetched directly from the firm, since several of those pages did not return usable text on this crawl.
Gaps in what we could check
A number of pages that would normally carry platform detail for other regions covered by our evidence, including GB and AE platform pages, returned little to no text, according to our evidence’s own failures log. What is written above about Puyin Caifutong (浦银财富通), the desktop application and the web login comes from the firm’s Hong Kong-facing customer-service and business pages, which did render; we cannot say from this crawl whether the same three platforms are offered, described differently, or absent on the regional pages that failed to load.
Special Offers
The pages we fetched for SPDB International Securities Limited carry no promotions page, no bonus schedule and no discount-code terms. What the firm’s own business and account-opening material does show are financing and fee mechanics around new share subscriptions, which is the area where a broker in this space would normally advertise a sign-up incentive if it ran one.
What SPDB International’s own pages describe instead of an offers page
The firm’s customer service FAQ sets a new share (IPO) subscription handling fee of HKD 100, charged whether the client subscribes with cash or through margin financing. Its securities business page describes IPO subscription financing of up to a 90% financing ratio, framed as a way to increase the loan amount available against the total subscription amount and so improve allotment chances, not as a promotional credit or cashback. Separately, the account-opening guide sets a Hong Kong client account activation deposit of not less than HKD 10,000, which must be transferred from an account the client holds at a Hong Kong-licensed bank, in the client’s own name, into SPDBI’s client funds deposit bank account before the account is activated. That deposit is an activation threshold, not a matched or bonus deposit.
None of this material labels the IPO financing ratio or the handling fee as a limited-time or promotional term, and we found no page describing a welcome bonus, a deposit match, a referral credit or a fee waiver period. Our evidence’s own failures log records that several pages that would normally carry account, fee and terms detail for other regions (fees pages for GB, AE, ID and AU; the GB accounts page; risk and terms pages for GB, AE and ID) returned little or no text on this crawl. So this section reflects what the Hong Kong-facing securities and account-opening pages we did retrieve say, and says nothing about whatever those unretrieved pages might contain.
Fake “offers” circulating under the SPDBI name
SPDB International’s own site carries a fraud warning stating that false information has circulated through social media and SMS, claiming to be SPDBI-related activity on new share subscriptions, investment advisory, or high-yield wealth management. The warning directs anyone who encounters this to verify it against the official hotlines, (852) 28086408 and 4001205528, and the official site at spdbi.com. That warning is about impersonators using SPDBI’s name to push offers the firm did not make, not a promotion SPDBI itself runs, and it is worth flagging precisely because “new share subscription” incentives are the kind of claim this section would otherwise be reporting as a genuine offer.
Our warning-list search covered 1,441 entries mirrored from the CYSEC, FCA and FSC Mauritius lists, and SPDB International does not appear on any of them. That check does not extend to marketing or promotional-offer complaints specifically, only to the regulators mirrored, so it should not be read as clearing the firm on offer-related conduct one way or the other.
Opening an Account
SPDB International Securities Limited runs its retail onboarding as an online application, not a walk-in or paper-only process. The firm’s account-opening guide describes a flow for Mainland and Hong Kong individual clients in which the applicant selects an account type as part of the application: a margin account (保证金账户) or a cash account (现金账户). The guide does not publish a minimum deposit tied to either account type itself; the deposit requirement that is published attaches to activation, covered below.
Steps in SPDB International’s online application
Two stages of the application feed directly into what the client can later do on the account. The first is a tax-residency declaration: the applicant must state their US-person status and declare all tax residencies as part of the basic information (基本资料) step; SPDBI’s guide states that where a client is identified as a US person or holds a US beneficial interest, their account data may be reported to the US Internal Revenue Service under FATCA. The second is a risk and investment-experience questionnaire, filed under investment experience and risk assessment (投资经验及风险测评) in the same guide. That questionnaire is not a formality: SPDBI ties it directly to product access, covered below.
The account only becomes usable once an activation deposit clears. For Hong Kong clients, SPDBI’s account-opening guide sets that deposit at not less than HKD 10,000, and specifies how it must arrive: transferred, in the client’s own name, from an account at a Hong Kong-licensed bank, into SPDBI’s client funds deposit bank account. The guide states the account is activated only once that deposit is confirmed, meaning a client cannot fund it from a third party’s bank account or from a bank outside Hong Kong’s licensed banking system and expect the account to go live.
A separate downloads page lists a Customer Agreement said to take effect from 20 December 2024, alongside other account-opening forms. That page gives us the agreement’s name and effective date only; it does not publish the clause text itself, so we cannot report what the agreement binds the client to beyond the fact that one exists and when it took effect.
What gates derivatives trading at SPDB International
The risk questionnaire is not just recorded for file; SPDBI’s guide states that a client with no prior derivatives investment experience, who has not also completed self-directed education on derivatives as recorded in that questionnaire, cannot have derivatives trading enabled on their account. In practice this means two applicants who pass activation identically can still end up with different product access, depending on what they declared and whether SPDBI accepts that declaration as sufficient self-education. The same guide notes a related restriction that sits at the trading stage rather than account opening: odd-lot (碎股) orders are not available on SPDBI’s online platforms at all and can only be placed by phone through the client’s assigned relationship manager.
The higher account tier and who qualifies for it
An earlier published review of SPDBI, which we are restating here rather than quoting since we have not read the underlying document ourselves, described a Professional Investor Account sitting above the standard retail tiers. According to that earlier review, individual applicants need a securities or cash portfolio of at least HKD 8 million to qualify, while corporate applicants must show a portfolio of at least HKD 8 million, or total assets of at least HKD 40 million. The same source describes this tier as running on negotiated leverage, institutional pricing and negotiated commission through a relationship manager, with no self-directed platform access laid out for it and no demo account offered. We were not able to check these figures against SPDBI’s own account or fee pages: several pages that would normally carry that detail did not return usable text on this crawl, so the HKD 8 million and HKD 40 million thresholds rest on the earlier review’s reporting rather than on a page we fetched ourselves.
Where account-opening sits on SPDB International’s own footprint
The activation mechanics above apply to SPDB International Securities Limited, the entity holding SFC licence BKW389 for Type 1 and Type 4 regulated activities. SPDBI’s group also includes SPDB International Investment Management Limited (SFC licence BFY108) and SPDB International Capital Limited (SFC licence BFZ375), but the account-opening guide we read is written for the securities arm specifically; we found no separate published onboarding flow for the asset management or corporate finance subsidiaries in our evidence.
Deposits & Withdrawals
What it costs to open the tap: SPDB International’s activation deposit
SPDB International’s own account-opening guide sets a minimum activation deposit of not less than HKD 10,000 for Hong Kong clients. The guide requires that deposit to be transferred from an account at a Hong Kong-licensed bank, held in the client’s own name, into SPDBI’s client funds deposit bank account, and it states the account is activated only once that transfer is confirmed. That is the only funding rail the account-opening guide describes: a same-name bank transfer, in Hong Kong dollars, into a specified client-funds account, with activation gated on confirmation rather than on the transfer being merely sent.
Where the evidence runs out
Our evidence that fed this review notes that a number of pages which would normally carry fee schedules, account terms and legal disclosures failed to render on this crawl, including the fee pages for the UK, UAE, Indonesian and Australian sites, the UK account page, the UK/UAE/Indonesian risk and terms pages, and the legal pages across the UK, UAE, Indonesian and Australian sites. We have no withdrawal fee, no processing-time figure, no minimum withdrawal amount, and no list of accepted withdrawal methods beyond the bank-transfer rail the account-opening guide describes for funding. We are not asserting SPDBI charges nothing to withdraw, or that a fee schedule doesn’t exist somewhere on its site; we are saying the pages our evidence fetched did not return that content, and the failures log records why.
Fees tied to trading activity
SPDB International Securities Limited’s customer service FAQ sets a new share (IPO) subscription handling fee of HKD 100, and states this applies whether the client subscribes with cash or through margin financing. Its securities business page describes IPO subscription financing of up to a 90% financing ratio, meaning the loan can cover up to nine-tenths of the total subscription amount, marketed as a way to increase allotment chances rather than as a deposit or withdrawal mechanism in its own right. Beyond these two items and the HKD 10,000 activation deposit, the fee material we read does not give a commission schedule, custody fee, or inactivity charge.
Account tiers and the deposit thresholds attached to them
An earlier review of this firm, which this rewrite draws on for figures we could not independently verify against SPDBI’s own pages, described a Professional Investor Account requiring a securities and cash portfolio of at least HKD 8 million for individuals, or a portfolio of HKD 8 million or total assets of HKD 40 million for corporate applicants. That same earlier review described this tier as carrying negotiated leverage and negotiated commission rather than a published rate card. We restate this as what the earlier review reported, not as something SPDBI’s own site told us directly. Separately, the account-opening guide we did read lets Mainland and Hong Kong individual applicants choose between a margin account (保证金账户) and a cash account (现金账户) during the online opening flow, without a minimum deposit figure attached to either.
Conditions that gate what a client can move or trade
The account-opening guide ties derivatives access to the risk questionnaire: a client with no prior derivatives experience who has not completed self-directed education on derivatives, as recorded on that questionnaire, will not have derivatives trading enabled, regardless of the size of any deposit already placed. The same guide requires a tax-residency declaration under FATCA during opening; a client identified as a US person, or as holding a US beneficial interest, has their account data made reportable to the US Internal Revenue Service. Odd-lot trading, per the business page, is not available through SPDBI’s online platforms at all and has to go through the client’s relationship manager by phone, which functions as another gate on how a position is unwound rather than a deposit or withdrawal rail as such.
What we checked and found clean
We searched 1,441 warning-list entries mirrored from CySEC, the FCA and the FSC Mauritius, and SPDB International does not appear on any of them. We also searched the Hong Kong SFC’s Public Register of Licensed Persons and Registered Institutions directly and confirmed CE references BKW389, BFY108 and BFZ375 as active licences held by SPDB International Securities Limited, SPDB International Investment Management Limited and SPDB International Capital Limited respectively, with no public disciplinary action recorded against any of the three. None of that register data describes a client-money segregation rule or a compensation scheme applying to deposits; it confirms licensing status, not fund-handling terms.
Why the score moved
TrueBroker’s previous score for this firm was 4.2 out of 10; this review scores it 5.2. That change is our assessment being restated against current evidence, not a claim that the firm’s own terms changed. Regulation now scores 7.4, built on the three confirmed active SFC licences above and a clean result across the 1,441 mirrored warning-list entries. Fees still scores only 3 out of 10, because beyond the HKD 100 IPO handling fee, the up to 90% subscription financing ratio and the HKD 10,000 activation deposit, the pages that would normally carry a withdrawal fee schedule or a full commission table did not render for our evidence.
Customer Support
SPDB International’s contact page lists two email addresses, cs@spdbi.com and enquiry@spdbi.com, alongside several phone numbers spread across what the page labels as separate divisions: +852 2808 6408, 400 120 5528 and +852 2887 9331 for the securities division, +852 2809 0300 and +852 2793 2272 under a second contact block the page does not clearly name, and +86 21 6161 6202 for the Mainland China division. The same page gives a Hong Kong office address at 33/F, SPD Bank Tower, One Hennessy, 1 Hennessy Road. That is the full set of channels the contact page gives us; it lists email and phone numbers and says nothing about opening hours, live chat, or a ticketing system.
Reaching SPDB International by phone or email
The split between a “securities division” block and a second, unlabelled block of numbers on the same contact page makes it hard to say from the page alone which line a general enquiry should go to versus which one handles the securities business specifically. A client with a dealing or account problem has the 400 120 5528 and +852 2808 6408 numbers the page assigns to securities, plus a Mainland China line for that market; anyone unsure which block covers their issue is working from a contact page that does not sort itself out for them.
A fraud warning on SPDB International’s own homepage
SPDBI’s own homepage carries a warning that false information has circulated by social media and SMS, claiming to be SPDBI activity around new share subscriptions, investment advisory, or high-yield wealth management. The page directs anyone contacted this way to verify through the official hotlines, (852) 28086408 and 4001205528, and the official site at spdbi.com. This is the firm telling its own site visitors, in its own words, that people impersonating it are an active problem, and pointing them back to the same phone numbers listed on the contact page above for verification.
What the site tells a client before they rely on it
SPDBI’s disclaimer states, in the original Chinese, that SPDB International Securities Limited’s website content has not been reviewed by the SFC (“浦银国际证券有限公司的网站内容尚未经证监会检视”), and separately that information on this site is for reference only and does not constitute an offer, solicitation, or investment advice (“本网站所载的信息仅供参考之用,并不构成任何投资产品之要约、要约招揽或任何投资建议”). Read together, a client who later disputes a trade or decision made on the strength of something published on the site is on notice, from the site itself, that the content was never vetted by the regulator and was never advice in the first place; any complaint grounded in “the website told me” runs into that disclaimer directly.
The account-opening flow adds two further points a complaining client would need to reckon with. It requires a tax-residency declaration under FATCA, including US-person status, and warns that a client identified as a US person, or holding a US beneficial interest, may have their account data reported to the US Internal Revenue Service. It also ties derivatives trading to a risk questionnaire: a client with no prior derivatives experience and no documented self-education on derivatives will not have derivatives trading activated on their account, regardless of how much they hold elsewhere. A client escalating a complaint about being unable to trade derivatives would be pointed back to this questionnaire step rather than to a support agent’s discretion.
The agreement governing the relationship
The forms-download page names a Customer Agreement (客户协议), effective from 20 December 2024, as the document governing the client relationship. That page gives only the form’s existence and effective date; it does not publish the clause text, so what the agreement says about complaints handling, liability, or dispute resolution is not something we can quote or summarise from what we fetched. A client wanting to know how a dispute with SPDB International actually gets resolved would need to pull that document directly rather than rely on the contact or disclaimer pages covered here.
Odd-lot trading is also gated in a way that touches support directly: the fee page states this order type is available only by telephone through the client’s assigned relationship manager, not through the online platforms, so a client without a working phone line to their manager cannot place that order type at all.
Prohibited Countries
SPDBI publishes no country restriction list in the material our review process fetched. The account opening guide names a Hong Kong bank transfer requirement and a Hong Kong client activation deposit, and the firm’s contact page lists Hong Kong and Mainland China phone lines, but none of the pages we read state a nationality bar or a list of excluded jurisdictions.
What the SPDBI pages we read actually gate
The restrictions we can point to are eligibility thresholds and product gating, not geography. Our earlier review’s account tier data describes a Professional Investor Account requiring a securities or cash portfolio of at least HKD 8 million for individuals, or for corporations a portfolio of HKD 8 million or total assets of HKD 40 million. Because that figure comes from the earlier review rather than a page our review process fetched, we report it as what the earlier review found rather than as SPDBI’s own published wording.
The firm’s own account opening guide sets a Hong Kong activation condition: an account is only activated once a deposit of not less than HKD 10,000 has been confirmed, transferred in the client’s own name from an account at a Hong Kong licensed bank to SPDBI’s client funds deposit bank account. That is a funding channel requirement tied to a Hong Kong bank account, not a stated exclusion of clients from any other country.
The same account opening guide gates derivatives trading on documented experience rather than on residence. Clients with no prior derivatives investment experience who have not completed self directed education on derivatives, as recorded in the risk questionnaire, cannot have derivatives trading enabled on their account.
The account opening flow also carries a FATCA tax residency declaration. A client must declare US person status and all tax residencies during account opening, and if identified as a US person or holding a US beneficial interest, their financial account data may be reported to the US Internal Revenue Service. That is a reporting obligation attached to US tax status, not a statement that SPDBI refuses US clients.
What the evidence does not cover
Our evidence’s failures log records that several pages that would normally carry account, fee, risk disclosure and terms detail failed to render for this crawl, including gb, ae, id and au fee pages, the gb accounts page, and gb, ae and id risk and terms pages. A published country restriction list, if SPDBI maintains one, could sit on any of those pages and would not appear in what we fetched. We are not asserting SPDBI has no such list; we are reporting that the pages we read do not carry one.
Odd lot trading is restricted by channel rather than by country: it is available only via telephone order through the client’s assigned relationship manager, not through the online platforms. That is the one access restriction the business securities page states outright, and it applies to a trade type, not to a jurisdiction.
Scoring note
Our previous review scored SPDBI 4.2 out of 10. This review scores it 5.2 out of 10. That is our assessment changing, not the firm, because both the scoring criteria and the evidence base changed between the two reviews. The regulation score of 7.4 reflects three confirmed Hong Kong SFC licences among the entities we checked, CE references BKW389, BFY108 and BFZ375, each shown active on the SFC Public Register of Licensed Persons and Registered Institutions with no public disciplinary action recorded, plus a clean result from our search of 1441 warning list entries mirrored from CYSEC, the FCA and the FSC Mauritius, on which SPDBI appears on none. Fees score 3 and support scores 3.8, reflecting the gaps in published fee and account material described above rather than any prohibited country finding.
Conclusion
SPDB International scores 5.2 out of 10, up from the 4.2 this catalogue previously recorded for it. The move is our assessment, not a change in the firm: this review pulled licence data directly from the Hong Kong SFC Public Register rather than relying on our earlier review’s account, and regulation now sits at 7.4 on the strength of that register check, alongside fees at 3, platform at 7.4, support at 3.8 and reviews at 4.4.
What the SFC register confirms about SPDB International
The Hong Kong SFC Public Register of Licensed Persons and Registered Institutions shows three separate SPDB International entities as active. SPDB International Securities Limited holds CE reference BKW389, licensed for Type 1 and Type 4 activities, dealing in securities and advising on securities. SPDB International Investment Management Limited holds CE reference BFY108, licensed for Type 4 and Type 9, advising on securities and asset management. SPDB International Capital Limited holds CE reference BFZ375, licensed for Type 1 and Type 6, dealing in securities and advising on corporate finance. The register records no public disciplinary action against any of the three. We also searched 1,441 warning-list entries mirrored from CYSEC, the FCA and the FSC Mauritius, and SPDB International appears on none of them, a clean result that covers only the lists we mirror rather than every regulator worldwide.
One claim in our evidence, describing a fourth licence held by “the parent entity” for corporate finance, securities advisory and asset management activities granted 30 December 2015, could not be checked: it names no CE reference and the SFC name search returned no single matching corporation for that ambiguous description. That is a gap in the claim, not a finding against the firm. The same applies to a cited HKEX exchange-participant registration and a Shanghai ICP filing number, 沪ICP备05022859号-12: we hold no register to check either against, so both remain unverified rather than confirmed or denied.
Where the fee and support scores come from
Fees score 3. The firm’s own account-opening guide gives a Hong Kong client activation deposit of not less than HKD 10,000, transferred in the client’s own name from a Hong Kong-licensed bank account before the account is activated. The same securities page sets a new share subscription handling fee of HKD 100, cash or margin, and describes financing of up to 90% of a subscription amount to increase allotment chances. Beyond those figures, several pages that would normally carry fuller fee and commission detail did not render on this crawl, so the wider cost picture, including the Professional Investor account’s negotiated commission structure reported by the earlier review, is not something we read first-hand.
Support scores 3.8. The contact page lists two email addresses, cs@spdbi.com and enquiry@spdbi.com, alongside several phone lines split across securities, other divisions and Mainland China, plus an office address at 33/F, SPD Bank Tower, One Hennessy, Hong Kong. That is a working set of contact channels rather than a single unified support line, and we found no service-level detail, such as response times, attached to any of them.
SPDB International’s own platform, and a correction to our earlier review
Platform scores 7.4. The firm’s own pages describe an online trading login, a branded mobile app called Puyin Wealth Link (浦银财富通) on the Apple App Store, Google Play and as a standalone APK for Mainland Android, and a downloadable desktop application in both Simplified and Traditional Chinese. This directly contradicts our earlier review’s claim that the genuine SPDBI runs no proprietary platform and no mobile app: that claim, restated here rather than quoted, does not hold up against what the firm’s own site publishes, and a reader using “no platform” as a test for spotting clone firms would misjudge SPDBI’s own website on that basis. SPDBI’s own homepage separately carries a fraud warning about false SMS and social-media messages impersonating it around new share subscriptions and wealth management, directing users to verify through its official hotlines and site, which confirms clone-firm impersonation is a live, firm-acknowledged risk rather than something only our earlier review flagged.
What holds a client
The account-opening flow requires a FATCA tax-residency declaration; a client identified as a US person or holding a US beneficial interest has their account data reported to the US Internal Revenue Service. Derivatives trading is gated behind the risk questionnaire: without documented prior derivatives experience or completed self-directed education, SPDBI will not activate derivatives trading, regardless of the client’s stated wealth. A Customer Agreement effective from 20 December 2024 is listed on the firm’s forms page, though only the form’s existence and date are published there, not the clause text itself.
SPDB International holds three active Hong Kong SFC licences confirmed on the regulator’s own register and runs its own trading app, desktop platform and web login, but its published fee and support detail stays thin and its score sits at 5.2 out of 10.
What we saw
Pages captured from SPDB International’s own site when this review was written. Brokers change their terms; these are what we read.
Score history
Recomputed daily; every move is on the record. The current score is always the latest row.
| Date | Score | Move |
|---|---|---|
| 2026-10-12 | 5.2 | ▲ |
| 2026-07-25 | 4.2 | = |
| 2026-07-18 | 4.2 | ▼ |
| 2026-07-11 | 4.3 | · |
FAQ
Is SPDB International regulated?
Yes. Three subsidiaries hold active Hong Kong SFC licences, confirmed on the register: SPDB International Securities Limited (BKW389), SPDB International Investment Management Limited (BFY108) and SPDB International Capital Limited (BFZ375).
Does SPDB International have a trading app?
Yes. Its own pages describe a mobile app (浦银财富通, SPDB Wealth), a desktop application and a web trading login. Our earlier review said it had none, which was wrong.
What is the minimum deposit at SPDB International?
Hong Kong clients activate an account with a deposit of at least HKD 10,000, sent from a Hong Kong-licensed bank account in their own name.
What does SPDB International charge?
It publishes a HKD 100 handling fee for new share (IPO) subscriptions. Its standard commission schedule was not available for us to read.
How do I avoid fake SPDB International sites?
The firm’s own site warns of SMS and social media messages impersonating it. Check any contact against the official hotlines and website before sending money.
How this review works
Track SPDB International live: score moves and red notices, in your pocket.