STOCK · CHECKED 10 OCT 2026
EXANTE review.
Cyprus-based broker with CySEC, FCA run-off and SFC licences across group entities
OK-ISH
OUT OF 10
EXANTE is a multi-entity broker group whose Cyprus firm, EXT Ltd, holds a confirmed CySEC licence (165/12) with compensation cover to 20,000 EUR and negative balance protection. Its Hong Kong unit holds an active SFC licence that carries a June 2026 fine and reprimand, and current marketing names a separate entity, LHCM Ltd, as FCA regulated with no licence number, company number or address published.
Each criterion is scored 1 to 10 from primary sources. The overall score is their unweighted mean. How scoring works.
| Founded | 2011 |
|---|---|
| Headquarters | CY |
| Minimum deposit | Not stated |
| Platforms | Proprietary platform (desktop, web, mobile), FIX/HTTP API Integration, AI-Powered Pulse |
- CySEC licence 165/12 confirmed authorised for EXT Ltd
- CySEC cover includes compensation up to 20,000 EUR and an ombudsman
- Negative balance protection and 30:1 leverage cap on major FX under CySEC
- SFC Hong Kong licence BNN565 confirmed active for Type 1/2 dealing
- EURUSD round turn from USD 3.00 on 1 lot
- Support by email, live chat and phone, in the client's own language, around the clock
- FCA licence 589898 is a Supervised Run-Off, not open to new UK clients
- XNT Ltd's FCA listing carries no licence number
- Two of the four confirmed licences are in run-off and take no new clients
- SFC licence BNN565 carries a June 2026 fine and public reprimand
- LHCM Ltd markets itself as FCA regulated with no FRN, number or address published
- Minimum deposit not published
Overview
TrueBroker is a free broker safety checker, and this page is our review of EXANTE, scored 7.5 out of 10 across regulation, fees, platform, support and reviews. EXANTE is the trading brand of EXT LTD, a Cyprus limited liability company registered at 28 October Avenue, 365, Vashiotis Seafront Building, 3107, Limassol, Cyprus, and that entity appears as the contracting party in every one of the ten country footers we fetched. The brand is marketed alongside two other companies, LHCM LTD and XHK Limited, which we cover below because the marketing material blurs the line between them.
Overview Table
| Headquarters | Limassol, Cyprus (28 October Avenue, 365, Vashiotis Seafront Building, 3107, per the registered office listed in EXANTE’s own site footer) |
| Established | EXT LTD was registered as HE 293592 on 12 September 2011, per the Cyprus Registrar of Companies via the CyprusRegistry.com mirror |
| Countries Served | EXANTE’s own pages state it does not onboard residents of Russia, Singapore, the US, and other jurisdictions per internal policy |
| Regulated By | CySEC (Cyprus), Financial Conduct Authority register (UK), Securities and Futures Commission (Hong Kong), each detailed below |
| Minimum Deposit | Not publicly stated; EXANTE’s account material describes a single multi-currency account type with no published minimum |
| Maximum Leverage | Not stated |
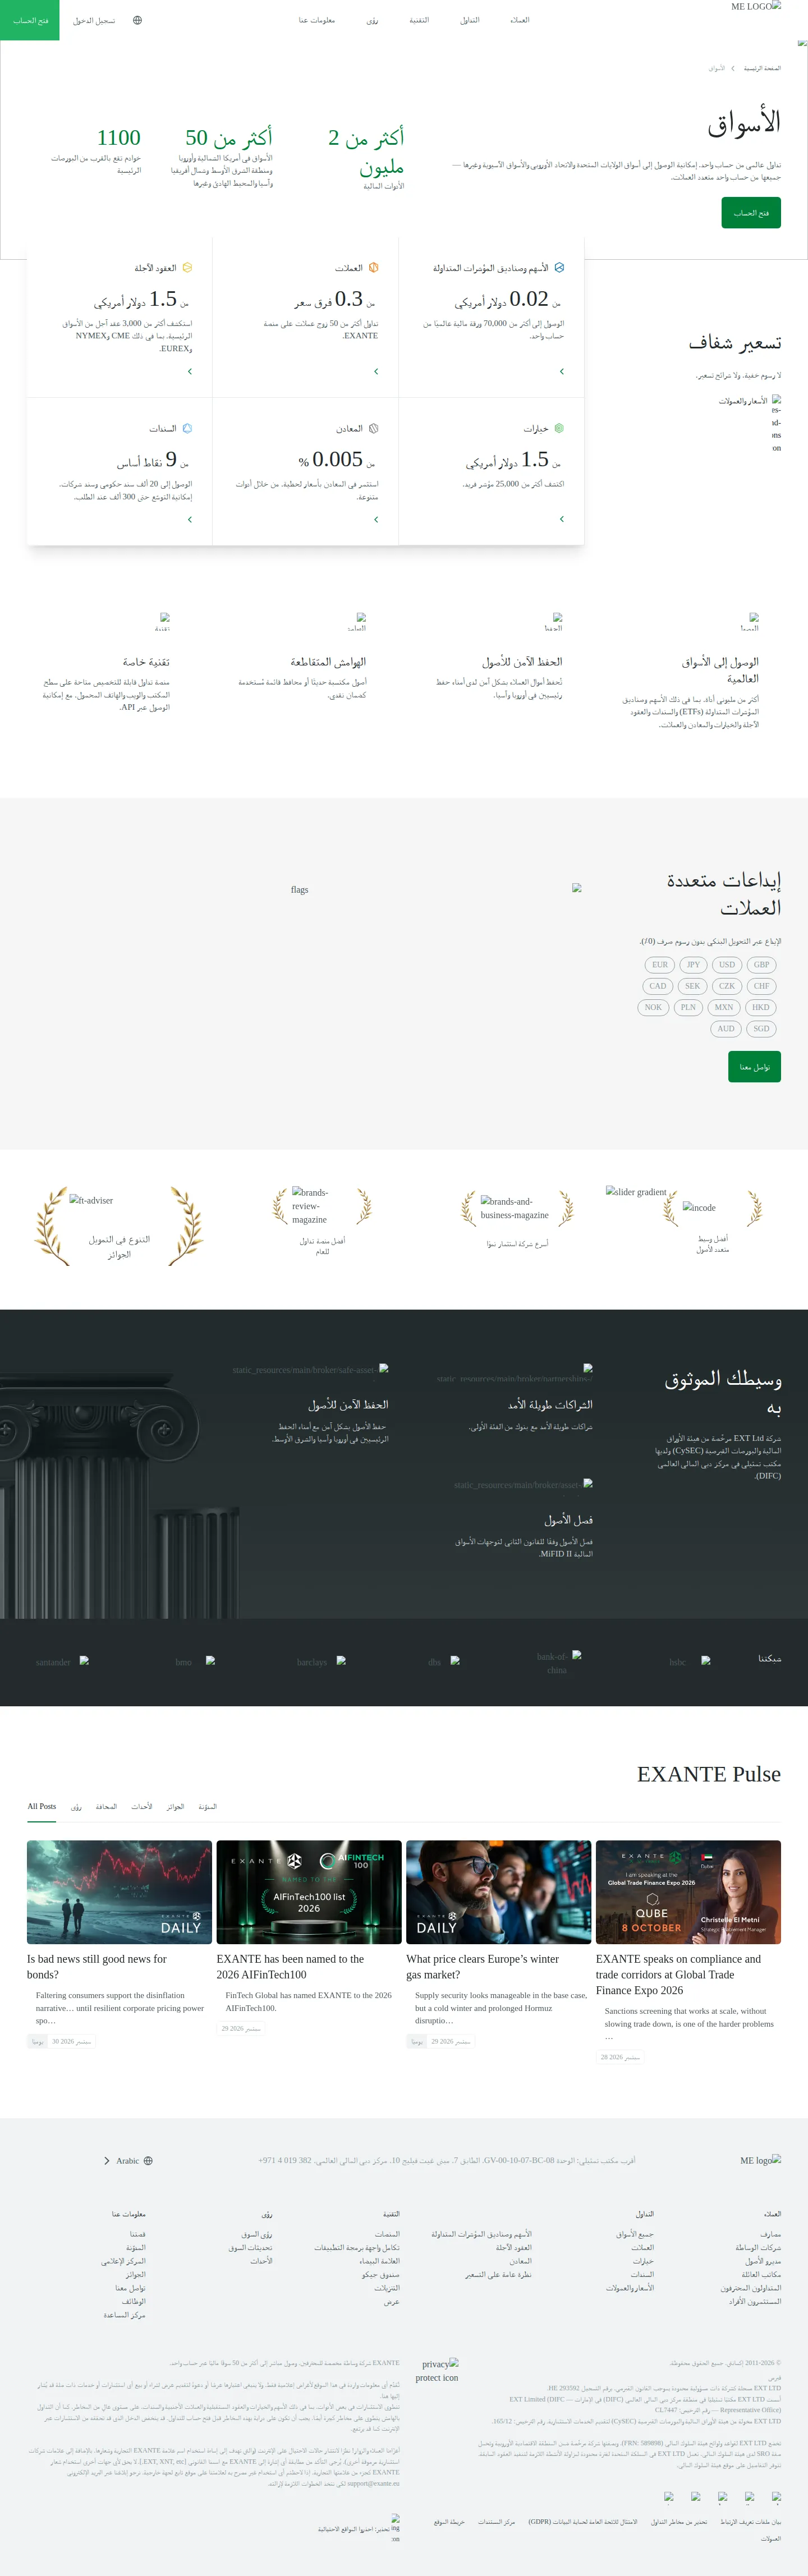
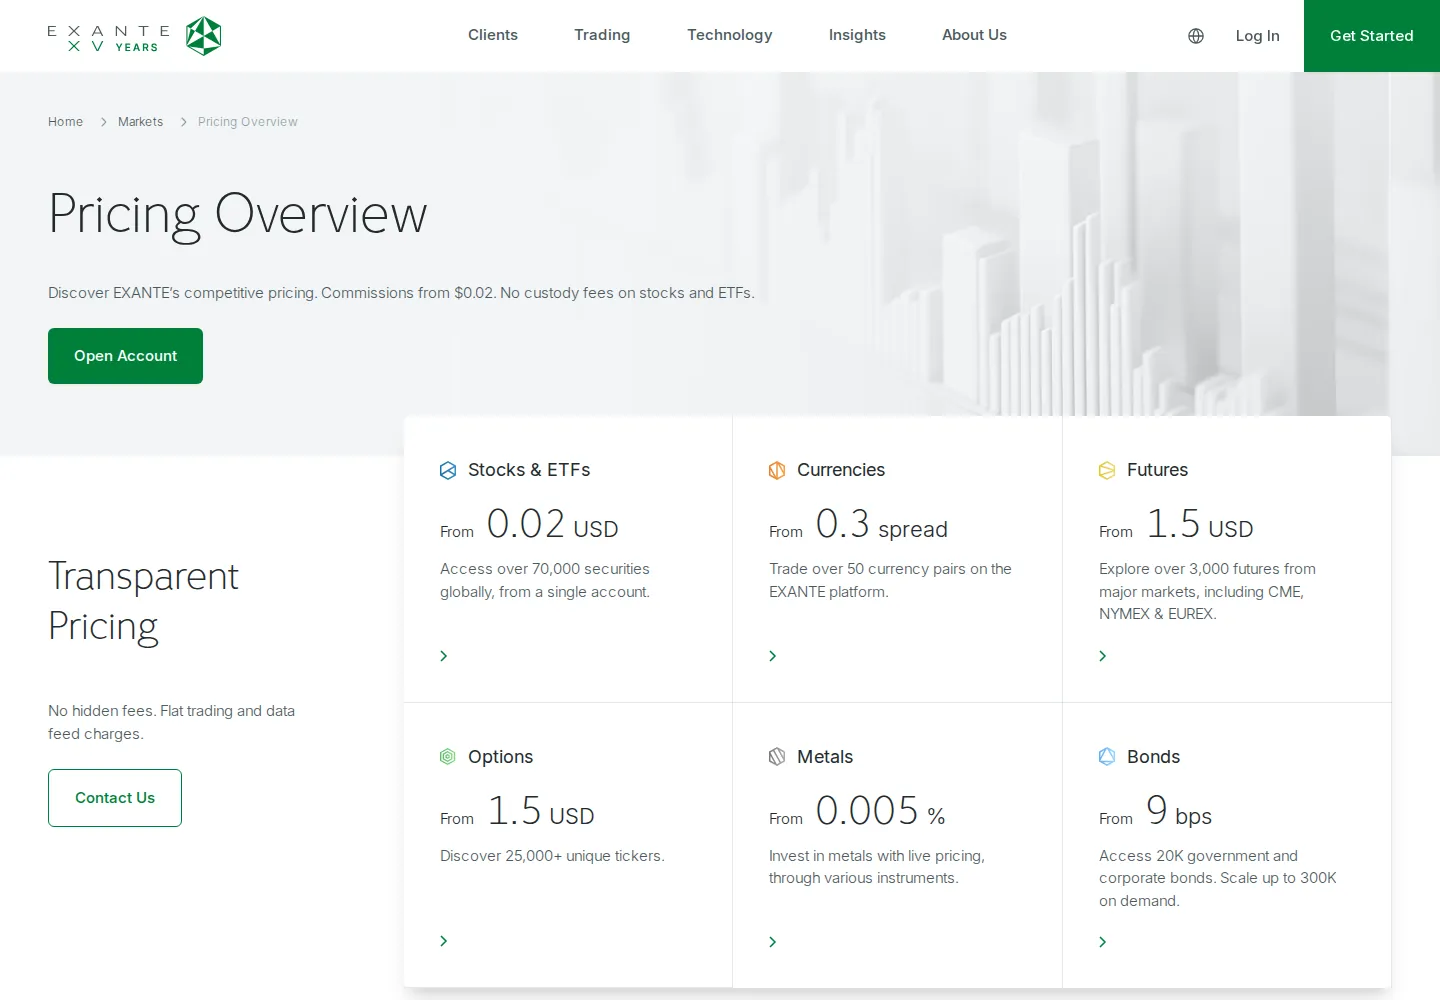
| Total Instruments | No single total is published. EXANTE’s markets page lists over 70,000 stocks and ETFs, over 50 currency pairs, over 3,000 futures, 25,000+ option tickers, and 20,000 bonds scalable to 300,000 on demand |
| Platforms | Proprietary platform across desktop, web and mobile; a FIX/HTTP API bridge for connecting existing infrastructure including Bloomberg EMSX; an AI curated news and sentiment tool called Pulse |
| Customer Support | Email (support@exante.eu), phone lines for Cyprus/EU, the UAE and Poland, live chat inside the client area, a help centre, and a dedicated relationship manager |
| Languages | Not stated |
Facts List
- The CySEC register confirms licence 165/12 for EXT LTD as an authorised Cypriot Investment Firm, which is a financial services permission rather than a plain company registration.
- Under FRN 589898, EXT LTD’s associated entity carries a “Supervised Run Off” status on the FCA register; that status only winds down contracts already in place and does not let the firm take on new UK retail clients.
- The FCA register separately shows FRN 620980, held by XNT Ltd, as “No longer authorised” since 31 December 2020. EXANTE’s own anti fraud notice names XNT as one of its legal names, tying a lapsed FCA registration to the active brand.
- The SFC register confirms CE number BNN565 for XHK Limited, licensed for Type 1 and Type 2 activities (dealing in securities, dealing in futures contracts), and also records two public disciplinary actions against it, a fine and a public reprimand, both dated 1 June 2026.
- We searched 1,444 warning list entries mirrored from CySEC, the FCA and the FSC Mauritius, and EXANTE appears on none of them.
- LHCM Ltd is marketed on EXANTE’s country pages as “regulated by FCA (UK),” but no FRN, company number or address is published for it anywhere on the site, so that claim cannot be checked against the register.
- The Cyprus Registrar of Companies, via the CyprusRegistry.com mirror, records HE 293592 for EXT LTD as an active limited company, but a company registry confirms incorporation, not a licence to deal in investments.
- According to the fee material, EXANTE charges 90 EUR for each trade executed via the dealing desk, another 90 EUR when a margin call triggers a manual close, and levies a rate equal to 100% a year on margin utilisation that exceeds 100%.
- An inactivity fee of 50 EUR per month applies only when all three conditions hold: no trade for 90 days, no open positions, and a balance under 5,000 EUR.
- Clients protected under the Cyprus Investor Compensation Fund can claim up to 20,000 EUR, well below the 85,000 GBP cap under the UK’s FSCS.
Who operates EXANTE
EXT LTD, Cyprus company number HE 293592, holds CySEC licence 165/12. The marketing material adds two more names to the “EXANTE” brand. LHCM LTD is described as “regulated by FCA (UK)” with no reference number given anywhere on the site, so a reader has nothing to look up against the FCA register. XHK Limited is described as licensed by the SFC in Hong Kong under CE number BNN565, and that number does check out on the SFC register, which also records two disciplinary actions against the firm. A fourth name, XNT Ltd, surfaces only in EXANTE’s own anti fraud notice, which asks visitors to “match any mention of EXANTE with our legal name [EXT, XNT, etc.].” The FCA register shows XNT Ltd’s FRN 620980 as no longer authorised since the end of 2020, so the firm’s own notice links its active brand to a lapsed UK registration that the marketing pages themselves don’t mention.
The regulatory picture behind EXANTE
EXT LTD’s CySEC authorisation, 165/12, is confirmed on the CySEC register of Cypriot Investment Firms. Its FCA entry, FRN 589898, is also confirmed, but the status is “Supervised Run Off” rather than full authorisation, meaning it exists to wind down pre existing contracts and is not a channel for onboarding new UK retail clients. A separate FCA record for XNT Ltd, FRN 620980, shows “No longer authorised” since 31 December 2020. On the Hong Kong side, the SFC register confirms XHK Limited’s CE number BNN565 as licensed for Type 1 and Type 2 activities, and it also lists a fine and a public reprimand against the firm, both dated 1 June 2026. Two further numbers on the site, a Hong Kong Companies Registry number (68841937) and a DIFC representative office reference (CL7447) with no named issuing authority, have not been checked against any register we hold; that’s a gap in our checking rather than a finding about the firm.
The one thing to know before funding an account with EXANTE
EXANTE positions itself toward professional and institutional traders rather than retail beginners, and its own disclosure material states that a client who agrees to be treated as professional loses negative balance protection, the retail leverage caps and the other MiFID safeguards that come with retail status. Combined with the FCA’s “Supervised Run Off” status on FRN 589898, which forecloses new UK retail business under that licence, and the lower Cyprus Investor Compensation Fund cap of 20,000 EUR against the UK’s 85,000 GBP FSCS cap, a prospective UK client is likely dealing with the Cyprus entity under Cyprus, not UK, protections. EXANTE’s own pages also state that it does not onboard residents of Russia, Singapore, the US and other jurisdictions determined by internal policy, and separately state it is not licensed, approved, registered or otherwise authorised by Singapore’s Monetary Authority.
Key Takeaways
What the registers actually confirm
The Cyprus Securities and Exchange Commission register lists licence 165/12 as authorised, and that entry also carries EXT LTD’s company registration number, 293592. The FCA register confirms FRN 589898 as held by EXT LTD, but the status it shows is Supervised run off, meaning the firm cannot take on new UK clients under this permission, only continue pre existing contracts. The FCA register also lists a second, similarly named entry, FRN 620980, held by XNT Ltd, with the status No longer authorised since 31 December 2020. EXANTE’s own anti fraud notice ties XNT to the same group of legal names as EXT, so a reader checking the FCA register alone could land on either number and needs to know both belong to the same brand, one active in run off and one lapsed. The Hong Kong SFC Public Register of Licensed Persons and Registered Institutions confirms XHK Limited holds CE reference BNN565, licensed for Type 1 and Type 2, dealing in securities and dealing in futures contracts, both active. That same register also records two public disciplinary actions against the firm: a fine and a public reprimand, both dated 1 June 2026.
Not every number on the page has been run against a register. The Cyprus Registrar of Companies entry for HE 293592 and the Hong Kong Companies Registry number 68841937 are both marked not checked in this pass, and the DIFC representative office number, CL7447, is listed against an authority that isn’t named on the site, so there is no register to check it against. A third marketed entity, LHCM Ltd, is described in the site’s own footer as regulated by FCA (UK), but no FRN, company number, or address is published for it anywhere in the fetched pages, so that claim sits outside anything the register search could confirm or refute.
Against the 1,444 warning list entries mirrored from CySEC, the FCA, and the FSC Mauritius, the firm’s names return no match. That is worth stating plainly because it covers only the three lists mirrored here, not every regulator worldwide.
What EXANTE charges
The cost and charges material we read prices stock and ETF custody at 0% and bond custody at 0.3% per year. An inactivity fee of 50 EUR per month applies only when all three conditions are met: no trade for 90 days, no open positions, and a balance under 5,000 EUR. A trade routed through the dealing desk costs 90 EUR, and a manual close triggered by a margin call carries the same 90 EUR charge, on top of whatever loss already occurred. Margin utilisation above 100% is billed at a rate equal to 100% a year on the amount above the line, a steep annualised rate on any client who breaches that line. Overnight financing is charged only on short positions and FX trades, and the applicable rates are disclosed exclusively within the client area, so prospective clients have no way to verify a public figure before funding an account. Deposits by bank transfer carry 0% exchange fees across the fourteen currencies listed on the site.
What binds a client who signs up
The site’s own disclosure states that opting into professional status removes negative balance protection, the retail leverage caps and the rest of the MiFID retail safeguards, a tradeoff worth weighing given the firm’s institutional and professional positioning. The Cyprus Investor Compensation Fund, which would apply to EXT LTD clients, caps eligible claims at 20,000 EUR per client, well below the 85,000 GBP ceiling under the UK’s FSCS. A UK based prospect relying on the FCA relationship should register that the applicable protection is the Cyprus scheme’s lower cap, not the UK one, since the FCA permission itself only covers pre existing contracts.
Gaps worth flagging
The pages fetched for this review describe a single multi currency account, spanning equities, ETFs, bonds, futures, options and currencies, with no published minimum deposit and no tiered retail account structure. They say nothing about deposit methods beyond bank transfer, and nothing about withdrawal fees or processing times, so a reader funding an account cannot confirm those terms from what was checked here. Support runs through email, phone lines in Cyprus, the UAE and Poland, live chat inside the client area, a help centre, and a named relationship manager, all listed on the firm’s own contact page.
Licenses & Regulation
EXT LTD, a limited liability company registered in Cyprus, trades as EXANTE, and our review of the country footers found it listed as the contracting entity in each one we retrieved. The brand is marketed more broadly than that one entity: country pages also name LHCM LTD and XHK Limited as firms “operating under the EXANTE brand,” and the firm’s own anti-fraud notice on its Australia-facing homepage ties a third legal name, XNT Ltd, into the same group, warning visitors to “match any mention of EXANTE with our legal name [EXT, XNT, etc.].” We checked five public registers directly against these names: CySEC, the FCA (twice, for two different firm numbers), the Hong Kong SFC, and the Cyprus Registrar of Companies. Before treating any blank result as an absence, we ran a positive-control search on six registers against a firm we already knew was listed, so a clean result means the name genuinely was not found rather than the search itself failing.
EXT LTD’s licence with CySEC
CySEC licence 165/12 is confirmed on the Cyprus Securities and Exchange Commission’s own register of authorised Cypriot Investment Firms. That register lists it as a CIF licence, a financial-services permission rather than a plain company registration, and the same entry carries Cyprus company registration number 293592 alongside the firm’s approved trade name.
EXANTE’s two FCA numbers in the UK
The FCA register shows two separate numbers worth keeping apart. FRN 589898 is held by EXT LTD; the register gives its status as “EEA Authorised,” records the Financial Conduct Authority as regulator with no termination date and an effective date of 01/04/2013, but its current status line reads “Supervised run-off” as of our check on 30 September 2026. A supervised run-off means EXT LTD is permitted to keep servicing pre-existing UK contracts but is not taking on new UK retail clients under this permission. The second number, FRN 620980, is held by XNT Ltd, the same legal name the firm’s own anti-fraud notice links to the EXANTE brand, and the FCA register gives its status as “No longer authorised,” effective 31 December 2020. A prospective UK client reading EXANTE’s marketing has no way to tell these two numbers apart without checking the register directly, since the site’s own disclosure text describes the run-off status but does not flag that a second, lapsed FCA entity shares the group’s name.
XHK Limited’s licence and disciplinary record with the SFC
The Hong Kong Securities and Futures Commission’s Public Register of Licensed Persons and Registered Institutions confirms CE reference BNN565 for XHK Limited, showing it licensed for Type 1 and Type 2 regulated activities, dealing in securities and dealing in futures contracts, both marked active. The same register entry also records two public disciplinary actions against the firm: a fine dated 1 June 2026 and a public reprimand dated the same day. Neither the nature of the underlying conduct nor the fine amount is part of what the register surfaced to us, so we report only that these two actions exist on the record.
LHCM LTD’s claimed FCA regulation cannot be checked
EXANTE’s own “Your Trusted Broker” marketing banner states that among the firms operating under the EXANTE brand, “LHCM LTD – regulated by FCA (UK).” No FRN, company number, or address for LHCM Ltd appears anywhere on the pages we fetched, and the name does not appear in any of the ten country legal footers we checked. Without a reference number there is nothing to look up on the FCA register, so this claim sits outside what we were able to verify.
Company registrations and the DIFC office
Cyprus company number HE 293592 is the number EXANTE’s own pages associate with EXT LTD, but we have not independently confirmed that pairing: a mirror of the Cyprus Registrar of Companies (via CyprusRegistry.com, a point-in-time copy rather than the live register) shows HE 293592 registered on 12/09/11 as a Limited Company with status Active, under the name M & L INVEST UNION MARKETS LTD rather than EXT LTD. That mirror can lag behind a change of name, so we are not reporting this as a different company, only as a check we have not resolved. Hong Kong company number 68841937, which the site associates with XHK Limited, has not been looked up at the Hong Kong Companies Registry at all; that registry only answers a person browsing it directly, and nobody has done so yet. The Dubai representative-office registration CL7447, attached to EXT Limited (DIFC Representative Office), names no issuing authority on the page itself, and we hold no register entry under that name to check it against. A representative office of this kind is not, on its face, a contracting entity authorised to deal in investments.
Warning-list search and compensation cover
We searched 1,444 warning-list entries mirrored from CySEC, the FCA, and the FSC Mauritius, and none of EXANTE’s names returned a match. That covers only the three regulators we mirror, not a global sweep, but it is a clean result across all of them. Separately, the Cyprus Investor Compensation Fund that would apply to EXT LTD’s CySEC-regulated business caps eligible claims at 20,000 EUR per client, well below the 85,000 GBP ceiling of the UK’s FSCS, a gap worth weighing against the FCA permission’s run-off status.
How to Trade
Rather than offering a tiered retail lineup, the firm runs a single multi-asset account: according to the pages we fetched, it gives direct market access to equities, ETFs, bonds, futures, options, commodities and currencies all from that one account, and no minimum deposit is published. EXANTE’s markets page lists over 70,000 stocks and ETFs, more than 50 currency pairs, over 3,000 futures from venues including CME, NYMEX and EUREX, 25,000-plus option tickers, metals, and 20,000 government and corporate bonds that the firm says it can scale up to 300,000 on demand.
How orders reach the market at EXANTE
Execution runs through a proprietary platform kept in sync across desktop, web and mobile, plus API access for anyone connecting their own infrastructure, according to EXANTE’s platforms page. The same page describes a FIX/HTTP API bridge pitched as low-latency connectivity that lets a client trade directly out of Bloomberg EMSX or other existing terminals rather than through EXANTE’s own interface. There is no MetaTrader option. The platforms page also lists an AI-curated feature called Pulse, built in to surface news and sentiment signals alongside the trading screens.
Some orders do not go straight to market. Our earlier review reported a 90 EUR fee for a trade placed through the dealing desk, separate from ordinary platform execution, and that detail is not something we independently confirmed from a page we fetched.
The rules that bind a position
Margin is where EXANTE’s costs turn punitive rather than incidental. According to the earlier review, once margin utilisation passes 100% the excess is charged at an annualised rate equivalent to 100%, and if a margin call forces a manual close, that triggers a separate 90 EUR fee on top of any loss already sustained. Neither figure comes from a page our review process fetched directly.
Overnight financing applies only to short positions and to FX; the earlier review noted that these rates are disclosed only inside the client area and never appear on a public page, meaning a prospective client has no public figure to check before opening an account. Custody is the one place the account is cheap to hold: stocks and ETFs carry 0% custody, while bonds are charged 0.3% a year, again per the earlier review.
Dormancy is charged too. The earlier review reported an inactivity fee of 50 EUR per month, but only when all three conditions hold together: no trade in 90 days, no open positions, and a balance under 5,000 EUR. A funded, open position or a balance above that threshold avoids it entirely.
Categorisation changes what protection a client keeps
EXANTE’s audience, per the earlier review, is professional and institutional rather than first-time retail traders, and that framing carries a contractual edge: a client who accepts professional categorisation loses negative balance protection, the retail leverage caps and other retail safeguards under MiFID II, as the earlier review described it. That trade-off sits alongside the compensation regime itself. EXT LTD’s CySEC authorisation (165/12) puts it under the Cyprus Investor Compensation Fund, where eligible claims are capped at €20,000 per client, a materially lower ceiling than the UK’s FSCS cap of £85,000, per the earlier review.
Currencies a deposit can move in
EXANTE’s own page lists bank transfer in GBP, USD, JPY, EUR, CHF, CZK, SEK, CAD, HKD, MXN, PLN, NOK, SGD and AUD, with 0% exchange fees on deposit and on multi-currency transfers generally. Deposit methods beyond bank transfer, and withdrawal fees and processing times, were not something we could verify from any primary source page in this fetch, so a client funding an account should confirm those directly with EXANTE before relying on them.
Account Types
EXANTE does not sell a lineup of account tiers. Instead of Standard, Gold or VIP grades, our earlier review describes one multi-currency, multi-asset account offering direct access to stocks, ETFs, bonds, options, futures, currencies and commodities through a single login; no minimum deposit appears anywhere in that review’s source material. Whatever the entity, EXT LTD, XNT Ltd or XHK Limited, a client ends up with, the account itself is structurally the same instrument, not a graded product.
What one EXANTE account covers
The firm’s own Australia-facing markets page backs up the single-account claim with scale: over 70,000 stocks and ETFs, more than 50 currency pairs, over 3,000 futures from exchanges including CME, NYMEX and EUREX, more than 25,000 option tickers, metals priced live, and access to 20,000 government and corporate bonds that the page says can scale up to 300,000 on demand. None of that is gated behind a higher account tier in the material we fetched; it sits inside the one account described above.
What the earlier review says the account costs to run
Because no opening deposit figure was found, the costs that can actually be reported are the running fees the earlier review listed, and they are worth taking at face value rather than rounding into a single “low cost” line. That review lists an inactivity fee of 50 EUR per month, but only when three conditions are all true at once: no trade for 90 days, no open position, and a balance under 5,000 EUR. A separate charge of 90 EUR applies to each trade routed through the dealing desk, and that same 90 EUR figure is billed again when a position is manually closed following a margin call, so a client whose position is force closed owes this fee in addition to any loss the closure itself locks in. On custody, the review reports 0% for stocks and ETFs but 0.3% per year for bonds, and on margin it reports a specific penalty: utilisation above 100% is billed at a rate equal to 100% a year on the amount above the line, not a modest overdraft-style rate.
Financing costs that EXANTE does not publish
The same review notes that overnight financing applies only to short positions and to FX, and that the rate for it is published solely inside the client area rather than on any public page, so nothing here can independently confirm a number for it. Everything else in the account, on that review’s account, carries no overnight charge at all. A prospective client comparing this against a competitor’s published swap rate would have to open an account first to see the figure.
Funding the account
Away from the trading fees, EXANTE’s own Australia root page states that bank transfer deposits carry 0% exchange fees across thirteen currencies it lists by name: GBP, USD, JPY, EUR, CHF, CZK, SEK, CAD, HKD, MXN, PLN, NOK and SGD, plus AUD. That page does not say anything about withdrawal fees or processing times for the account, and the earlier review flags that gap directly: deposit methods aside from bank transfer, and any withdrawal fee schedule, could not be verified from a primary source page in that review’s fetch either. Anyone opening the account should confirm withdrawal terms before funding it rather than assume they mirror the 0% deposit figure.
Negative Balance Protection
EXANTE does not publish a blanket negative-balance-protection guarantee on the pages we fetched, and the only description of what happens at the edge of a margin account comes from the earlier review of this firm that we are updating here, not from a document we read directly. Restated in our own words, that earlier review found a Cost and Charges Disclosure setting out two separate consequences for a client who runs margin too hard.
Negative balance protection depends on client category
Under MiFID II, the most material finding from the earlier review on this topic is that accepting professional categorisation costs a client negative balance protection as well as leverage limits and several other retail safeguards. Restated plainly: whatever protection a retail client has against owing EXANTE more than they deposited is not something a professional client keeps. EXANTE’s positioning throughout the pages we fetched is toward professional and institutional traders rather than first-time retail traders, which matters here because that audience is the one most likely to be offered, or to request, the professional categorisation the earlier review describes as trading away this protection. Nothing in the evidence we hold states what negative balance protection actually consists of for a retail client who does not opt into professional status, so we are not able to describe its terms beyond reporting that the earlier review found it is conditional on category.
What the CySEC and FCA licences cover here
Our evidence’s summary of the country footers records EXT LTD as the contracting entity in all ten. The Cyprus Securities and Exchange Commission register confirms EXT Ltd holds CIF licence 165/12, a financial-services permission rather than a mere company listing, on CySEC’s list of authorised Cypriot investment firms. That Cyprus authorisation is the one under which EXT LTD actually deals with clients. EXT LTD also appears on the FCA register under FRN 589898, where its status is Supervised run-off. According to the earlier review, the firm’s disclosure states that this permission only covers completion of contracts already in place; it does not give new retail customers in the UK a way to open an account, and nothing in the FCA register disputes that description. A prospective UK client reading about FCA regulation on this site is not, on this evidence, someone the FCA permission is currently available to onboard. The FCA register also lists a second, similarly named entity, XNT Ltd, FRN 620980, with the status No longer authorised since 31 December 2020; EXANTE’s own anti-fraud notice on the pages we fetched ties XNT to the same group of legal names the brand uses, so a reader checking “EXANTE” against the FCA register needs to know which of the two FRNs they are looking at before drawing any conclusion about current UK protection.
Compensation if EXANTE fails
The earlier review reported that eligible claims under the Cyprus Investor Compensation Fund, the scheme that sits behind a CySEC-licensed firm such as EXT LTD, are capped at €20,000 per client. That is materially lower than the £85,000 cap under the UK’s Financial Services Compensation Scheme, which is the comparison point the earlier review draws for a client weighing EXANTE against a UK-authorised alternative. Since the FCA permission held by EXT LTD is restricted to pre-existing contracts rather than open to new UK business, a new client’s compensation position, on this evidence, sits with the Cyprus fund and its lower cap rather than with the FSCS.
Trading Instruments
EXANTE markets a single multi-currency account giving direct market access across asset classes rather than the tiered retail accounts most brokers use. The firm’s markets page claims access to over 70,000 securities globally from that one account, more than 50 currency pairs, over 3,000 futures from major markets including CME, NYMEX and EUREX, more than 25,000 unique options tickers, metals through various instruments, and 20,000 government and corporate bonds, with the page stating this can scale to 300,000 on demand.
What EXANTE’s own fee pages say about carrying these assets
The cost disclosure the firm publishes prices custody by asset class rather than folding it into a flat platform fee. Stocks and ETFs carry 0% custody, while bonds are charged at 0.3% per year. That split matters for anyone building a account weighted toward fixed income rather than equities, since the two halves of a “stocks and bonds” account are priced on different bases.
Trading itself is not commission-free across the board. EXANTE’s own pricing overview lists stock and ETF commissions from 0.02 USD, which the earlier review recorded as per share per side on US equities; compared with Interactive Brokers, which we also review and which charges USD 0.005 per share under IBKR Pro, that entry price is four times higher. Placing a trade via the dealing desk costs 90 EUR, and that same 90 EUR charge is levied for a manual close triggered by a margin call. Where margin utilisation exceeds 100%, the excess is billed at an annualised rate equivalent to 100%, a figure the cost and charges disclosure treats as an ongoing, standing charge rather than something billed once. None of the fee material we read prices these charges differently by asset class, so the same dealing-desk and margin figures appear to apply whether the position is in equities, futures, options or bonds.
Overnight financing is the one cost the published material does not put a number on. Per the cost disclosure, this fee only applies to short positions and FX, with the actual rates published exclusively within the client area; as a result, anyone without a funded account has no way to check the overnight cost of a short or FX position before they open one.
Platform access to the asset range
The platforms page describes a proprietary desktop, web and mobile platform kept synchronised across all three, with API access alongside it, and no MetaTrader. For firms and traders already running their own infrastructure, the same page describes a FIX/HTTP API integration, including execution directly from Bloomberg EMSX and other terminals via a FIX API Bridge. The platforms page also lists an AI-curated news and sentiment feature it calls Pulse, built into the platform alongside the trading tools.
Where EXANTE’s own pages are silent
The evidence we hold does not include a published minimum deposit for the account, and the account material we read describes one multi-currency account rather than separate tiers with separate asset access, so there is nothing in the pages fetched that ties a specific minimum balance or account tier to access to any particular asset class. The instrument counts above come from EXANTE’s own markets page; we did not independently verify the 70,000 securities, 3,000 futures, 25,000 options tickers or 20,000 bonds figures against an exchange listing or a trade confirmation, so they are reported here as the firm’s own claim rather than as something we tested by placing a trade.
Education & Analysis
EXANTE runs its own platform rather than a licensed one. The firm’s platforms page describes a single proprietary system synchronised across desktop, web and mobile, with API access built in, and states plainly that there is no MetaTrader on offer. The earlier review of this broker noted that EXANTE offers one multi-asset, multi-currency account instead of the tiered retail account types other brokers use, and that matches how the rest of the offering is built: every instrument the firm lists as tradable runs through a single login and a single order book.
What EXANTE’s platform connects to
The same platforms page describes a FIX/HTTP API Integration, pitched as low-latency connectivity for a client’s existing infrastructure, and states that a client can execute directly from Bloomberg EMSX and other terminals through a FIX API Bridge. That is not consumer-facing charting; it is order routing built for a desk that already has its own terminal and its own analysis stack, and wants EXANTE as the execution venue behind it. Read alongside the earlier review’s note that EXANTE positions itself toward professional and institutional traders rather than first-time retail traders, the FIX bridge and EMSX connection are the clearest evidence of who the platform is actually built for.
AI-Powered Pulse
The platforms page also names a feature called AI-Powered Pulse, described as AI-curated news and sentiment signals built into the platform itself. The page gives no further detail on how the signals are generated, how often they refresh, or which markets they cover, so that is the extent of what can be reported about it: a named, in-platform news and sentiment feature, nothing more specific than the firm’s own one-line description.
What can actually be charted from the one account
EXANTE’s markets page sets out the range that sits behind the single account: stocks and ETFs describes access to over 70,000 securities globally from that one account, currencies lists more than 50 pairs tradable on the platform, futures claims over 3,000 contracts from major markets including CME, NYMEX and EUREX, options claims more than 25,000 unique tickers, and bonds describes access to 20,000 government and corporate bonds with the ability to scale up to 300,000 on demand; metals are listed as a separate instrument group with live pricing. The earlier review’s account summary frames this as direct access to stocks, ETFs, bonds, options, futures, currencies and commodities from one account, with no tiered retail account types and no published minimum deposit.
Execution route and its cost
The account structure is not purely electronic direct market access in every case. The earlier review reported a dealing desk trade fee of 90 EUR per trade when an order is placed through the dealing desk rather than routed electronically, and a separate 90 EUR charge for a manual close carried out on a margin call. Those two charges, as reported, sit inside the firm’s Cost and Charges Disclosure rather than the platforms page, but they describe a platform-level choice: a client who routes an order through the dealing desk, instead of the platform’s own order book or the FIX bridge, pays for that routing.
Custody charges follow the same instrument split described above: the earlier review reported 0% custody on stocks and ETFs, against 0.3% per year on bond custody, which matters for anyone building a bond position through the 20,000-plus bonds the markets page advertises rather than holding it through a broker that charges nothing on either asset class.
What the pages fetched do not cover
The platforms and markets pages fetched for this review describe the trading venue, the API and FIX connectivity, the AI Pulse feature, and the instrument list above. They say nothing about charting-specific tooling, such as which technical indicators or drawing tools sit inside the proprietary platform, how many timeframes it offers, or whether a demo account is available to test any of it before funding. That is a gap in what was fetched, not a statement that those features are missing from the platform.
Special Offers
The pages fetched for this review are account and cost pages, not a promotions page, and none of what they cover reads as a bonus, deposit match, cashback or referral scheme. The one place EXANTE advertises a 0% charge is on currency conversion at the point of deposit: the firm’s own page states 0% exchange fees on deposits made by bank transfer, across a currency list that runs to GBP, USD, JPY, EUR, CHF, CZK, SEK, CAD, HKD, MXN, PLN, NOK, SGD and AUD. That is a fee waiver on funding, not a trading credit.
What the earlier review reported about EXANTE’s cost schedule
Beyond that deposit-side waiver, the facts available to this catalogue about EXANTE’s charges come from our earlier review, not from a page our review process fetched directly, so they are reported here as what that review found rather than as EXANTE’s own words. It described a single multi-currency account with no tiered retail account types and no published minimum deposit, covering equities, ETFs, bonds, futures, options, commodities and currencies from one login. It also described a cost structure built around what a client pays rather than what EXANTE pays out: an inactivity fee; a 90 EUR charge for a trade placed through the dealing desk; a further 90 EUR for a manual close triggered by a margin call; and, for margin utilisation above 100%, a charge equivalent to 100% per annum on the excess. Custody was reported as split by asset class, 0% for stocks and ETFs against 0.3% per year for bonds, and overnight financing on short positions and FX was reported as real but not publicly quotable, since the rate is published only inside the client area rather than on any page a prospective client can check before opening an account.
Taken together, that is a fee sheet, not an offer sheet. A reader looking for a welcome bonus, a spread discount for a limited period, or a cashback tier on trading volume will not find one described on the pages this review draws on, and the only figure that resembles an incentive, the 0% deposit exchange fee, applies to funding the account rather than to trading it.
Opening an Account
EXANTE does not run a tiered sign-up ladder. The earlier review we are updating reported that the firm offers a single multi-currency account, giving direct access to stocks, ETFs, bonds, options, futures, currencies and commodities from that one account, and that no minimum deposit figure is published for it. There is no separate “beginner,” “standard,” or “VIP” account to choose between before applying.
Who EXANTE will not open an account for
EXT LTD’s own about page states plainly: EXT LTD does not onboard clients who are residents of Russia, Singapore, the US, and certain other jurisdictions as determined by internal policies. The same page adds, on Singapore specifically, that “EXT LTD is not licensed, approved, registered or in any other way authorised or regulated by the Monetary Authority of Singapore.” Anyone applying from those jurisdictions should expect the application to go nowhere, regardless of what the wider site shows them. On that last point, the earlier review we are updating found a gap worth flagging: a Singapore-based visitor to the site was served the full, unrestricted version of the site, with the internal warning text present in the page but not rendered where a visitor would see it. A prospective applicant browsing from Singapore cannot rely on the visible page to warn them off; the restriction exists in EXT LTD’s own policy, not in what renders on screen.
UK applicants specifically
The FCA register lists EXT LTD under FRN 589898 with the status “Supervised run-off,” checked on the FCA register search on 30 September 2026. A supervised run-off permission covers pre-existing contracts only; it is not an open door for a new UK retail client to sign up under. Anyone applying from the UK today is not opening an account under an active FCA retail authorisation, whatever the marketing footer implies about the group’s UK presence. The register separately lists a second, similarly named firm, XNT Ltd, FRN 620980, as “No longer authorised” since 31 December 2020. EXANTE’s own anti-fraud notice ties XNT to the same group of legal names as EXT LTD, which is worth knowing before assuming the two are unrelated.
Who EXANTE is built for
The earlier review we are updating described EXANTE’s audience as professional and institutional rather than first-time retail traders, and reported that clients who accept a professional-client categorisation lose negative balance protection, the retail leverage caps and other retail safeguards that come with MiFID II retail status. Anyone weighing whether to accept that categorisation during onboarding is trading away protections in exchange for the wider terms professional status brings, not gaining something for free.
Funding the account once it’s open
EXANTE’s own site lists bank transfer as a funding method, supporting GBP, USD, JPY, EUR, CHF, CZK, SEK, CAD, HKD, MXN, PLN, NOK, SGD and AUD, with 0% exchange fees on deposit for multi-currency funding. Beyond that, the earlier review we are updating flagged that deposit methods besides bank transfer, withdrawal fees, and processing times could not be verified from any primary source page in that fetch. Anyone funding the account for the first time should confirm withdrawal timelines directly with EXANTE before relying on them, particularly given the multi-currency structure of the single account on offer.
Registration paperwork behind the account
The contracting entity behind the account is EXT LTD, registered in Cyprus under HE 293592 (Cyprus Registrar of Companies, via the CyprusRegistry.com mirror), and authorised by CySEC under licence 165/12, confirmed on the CySEC register of Cypriot investment firms. The site’s marketing footer also names two further “EXANTE” brand entities alongside EXT LTD: XHK Limited, holding SFC Hong Kong CE reference BNN565, and LHCM LTD, described as “regulated by FCA (UK)” with no FRN, company number, or address published for it anywhere on the site. An applicant cannot independently check which of the three entities they are actually contracting with for a given product, or verify LHCM LTD’s claimed FCA status at all, before completing sign-up.
Deposits & Withdrawals
EXANTE’s own site names one funding rail: bank transfer. The Australia-facing page we read lists deposit currencies as GBP, USD, JPY, EUR, CHF, CZK, SEK, CAD, HKD, MXN, PLN, NOK, SGD and AUD, and states “0% exchange fees” on a deposit made this way, covering multi-currency deposits specifically. No card funding, e-wallet or other rail appears on that page; we have not seen one described anywhere else in the material we fetched.
Funding an EXANTE account
Beyond the bank-transfer currency list and the 0% deposit exchange fee on EXANTE’s own site, we have no figure for a minimum deposit. Our earlier review describes EXANTE’s offering as a single multi-asset, multi-currency account giving direct access to stocks, ETFs, bonds, options, futures, currencies and commodities, and it does not give a minimum deposit figure for that account.
What we could not confirm about getting money out
The earlier review reported that it could not verify EXANTE’s withdrawal fees, withdrawal methods, or processing times from any primary source page in its fetch. We are restating that gap rather than closing it: nothing in the material available to us here prices a withdrawal, names a withdrawal rail, or gives a payout timeline. A client should get those figures directly from EXANTE, inside the client area or from support, before relying on this review for them.
Charges that erode a balance between deposit and withdrawal
The earlier review’s account of EXANTE’s Cost and Charges Disclosure lists several charges that reduce what sits in the account rather than being charged on the funding or payout step itself. The earlier review priced custody for stocks and ETFs at 0%. The earlier review priced a trade placed through the dealing desk at 90 EUR per trade, and a position that is manually closed following a margin call is charged a further 90 EUR on top of any loss already taken on that position. Where margin utilisation exceeds 100%, the excess is charged at a rate equal to 100% a year, and a breach that continues turns this into a steep annualised charge. Overnight financing applies only to short positions and FX; the earlier review found the rate is not published anywhere public and sits inside the client area only, so it is not a figure we can check or quote here.
The compensation ceiling behind a deposit
EXT LTD’s licence sits with CySEC, the Cyprus regulator, and the earlier review put the Cyprus Investor Compensation Fund ceiling at €20,000 per client. That is worth weighing against a UK-authorised broker’s FSCS cover, which the earlier review put at £85,000, since it caps what a client could recover if EXANTE itself failed, separately from any loss taken on open positions.
Set against the fee score
None of the charges above is a percentage spread markup on entry; they sit on dormancy, custody, dealing-desk routing, and margin breaches instead, and several only bite under specific, named conditions rather than on every account. That structure is consistent with a broker priced mainly through its trading fees rather than its funding or payout mechanics, but it does not substitute for the withdrawal fee schedule we were unable to locate.
Customer Support
EXANTE lists a conventional cluster of contact channels rather than a single hotline. The firm’s own contact page names email support at support@exante.eu, three regional phone lines, a live chat channel, a Help Centre, and a dedicated relationship manager.
How to reach EXANTE
The contact page gives separate phone numbers for three regions: +357 2534 2627 for Cyprus and the EU, +971 4 019 382 for the UAE, and +48 222 630 313 for Poland. Email support runs through support@exante.eu. The same page states that live chat is reached “via the Client’s Area,” so a prospective client browsing the public site before opening an account cannot use it; chat only becomes available once an account exists and the client has logged in. A Help Centre is offered as a self-serve knowledge base, described on the page as somewhere to “find answers quickly,” alongside the option of a dedicated relationship manager who the page says a client can “connect directly with.”
Two registered addresses back the phone lines. The Cyprus office sits at 28 October Avenue, 365, Vashiotis Seafront Building, 3107, Limassol, Cyprus, sharing the same +357 2534 2627 number given for support. The Dubai office is at Unit GV-00-10-07-BC-08, Level 7, Gate Village Building 10, DIFC, reachable on the +971 4 019 382 line. Both addresses come from the firm’s own country pages rather than a directory listing, so they double as the entities a client would need to write to formally.
What a relationship manager gets a client, and what it doesn’t
The “dedicated relationship manager” channel is pitched as a named point of contact rather than a queue, which suits the firm’s professional and institutional positioning rather than a retail walk-in. Nothing on the contact page states response-time targets, complaint-handling procedures, or hours of operation for any of the five channels, so none of those can be reported here.
Where support meets cost
Some of what would ordinarily be a pure support question at EXANTE carries a price tag instead. Our earlier review reported that a manual close carried out on a margin call is billed at 90 EUR, on top of whatever loss triggered the close in the first place. The same earlier review reported that a dealing-desk trade, rather than one placed directly on-platform, is charged at 90 EUR per trade. Neither figure comes from a page our review process fetched directly, so they are restated here as what the prior review found rather than quoted from EXANTE’s own cost disclosure.
What happens if a complaint can’t be resolved with EXANTE
For a Cyprus-regulated client, recourse beyond the firm sits with the Cyprus Investor Compensation Fund, which the earlier review reported caps eligible claims at 20,000 EUR per client. That figure, again second-hand rather than fetched directly, is worth weighing against the UK’s FSCS cap of 85,000 GBP for anyone comparing EXANTE to a UK-authorised alternative, since the ceiling on what a Cyprus-regulated client can recover if the firm itself fails is materially lower.
The firm’s own warning about impersonation
EXANTE’s own site carries an explicit anti-fraud notice warning that fraudulent websites have used its brand name and logo, and the notice asks visitors to “match any mention of EXANTE with our legal name [EXT, XNT, etc.]” before trusting a channel claiming to be the firm. Read alongside the FCA register, that instruction cuts both ways: XNT Ltd is one of the legal names the firm itself ties to the EXANTE brand, and the FCA register shows XNT Ltd’s own permission, FRN 620980, as no longer authorised since 31 December 2020, while the currently active FCA permission sits under EXT LTD, FRN 589898. A client trying to use the firm’s own verification advice to check who they’re actually dealing with needs to keep those two legal names and two different FCA statuses apart, since a lapsed and an active permission are both offered as evidence of belonging to the same brand.
Beyond that notice, the site gives no separate complaints-handling page, no published escalation path beyond the channels already listed, and no stated hours for phone or chat support, so none of those can be reported here either.
Prohibited Countries
EXT LTD does not onboard clients who are residents of Russia, Singapore, the US, and certain other jurisdictions as determined by internal policies, according to the firm’s own about page. That last phrase leaves the full list open ended: the firm reserves the right to extend it without saying, on the page we read, what the additional jurisdictions are.
Singapore: a stated exclusion and a page that does not enforce it
For Singapore specifically, the firm’s own about page goes further than a general onboarding restriction. It states that EXT LTD is not licensed, approved, registered or in any other way authorised or regulated by the Monetary Authority of Singapore. That is a direct statement about MAS, named in the firm’s own text, not an inference.
What we found when checking how this plays out in practice is worth recording. When a Singapore IP address was used to fetch the site, it was served the full, unrestricted site. The shipped page text did contain the banner stating that services are not provided to Singapore residents and that the firm is not MAS authorised, but it was not rendered visibly on the page a Singapore visitor actually sees. So a Singapore based visitor sees the complete unrestricted offering, with the firm’s own disclosure about not serving Singapore present in the page’s code but not on display. We report this as what we observed in that fetch, not as a claim about every visit or every device.
The United Kingdom: authorised for old contracts, not for new UK clients
EXT LTD holds FCA registration FRN 589898. The FCA register itself, checked on 30 Sep 2026, lists the status of this permission as Supervised run-off. Under that status the firm cannot take on new UK clients through it. That matches what the firm states itself: EXT LTD is described as an EEA authorised firm permitted to remain active in the UK only for as long as it takes to carry out the activities needed to perform contracts that already existed, and for no other purpose. In practical terms, this permission does not give a new UK retail applicant a route to open an account with EXT LTD; it exists to wind down business already on the books.
A separate FCA entry, FRN 620980, is held by XNT Ltd, with a status of No longer authorised since 31 December 2020. EXANTE’s own anti-fraud notice on its site instructs visitors to match any mention of EXANTE with its legal names, listing EXT and XNT among them, which ties the lapsed XNT Ltd registration to the same group as the currently supervised EXT LTD. A prospective client checking the FCA register on either FRN should be clear about which one, and which status, applies to EXT LTD.
Who else this leaves out
Beyond the named jurisdictions, the firm’s own material frames itself around a professional and institutional audience rather than first time retail traders. That is a positioning statement from our earlier review rather than a formal exclusion clause, but it sits alongside the client categorisation terms: a client who accepts professional categorisation loses negative balance protection, the retail leverage caps and other retail safeguards under MiFID II. Nothing in the evidence we hold sets out a full published list of restricted countries beyond Russia, Singapore, and the US named on the about page, so this section reports what that page states and nothing beyond it.
Conclusion
EXANTE scores 7.5 overall, and the number reflects a split: the fee model is priced well (9), regulation drags the average down (6.7), and reviews trail everything else (5.7).
Why the regulation score sits where it does
EXT LTD holds CySEC licence 165/12, confirmed on the Cyprus Securities and Exchange Commission register as an authorised Cypriot investment firm, and that register also carries the company’s registration number, 293592. The same entity is authorised by the FCA under FRN 589898, but the FCA register records the status as Supervised run-off, meaning the firm cannot take on new UK clients under that permission; the disclosure covers pre-existing contracts only. A second, similarly named entity, XNT Ltd, holds FRN 620980, and the FCA register shows that one as No longer authorised since 31 December 2020. EXANTE’s own anti-fraud notice ties XNT to the same group of legal names as EXT LTD, so a reader checking either number needs to know both belong to the same brand before drawing conclusions from either one.
The Hong Kong side is more straightforward on paper and less so underneath: the SFC Public Register of Licensed Persons and Registered Institutions confirms XHK Limited under CE reference BNN565, licensed for Type 1 and Type 2 activities (dealing in securities, dealing in futures contracts), both active. That same register also lists two disciplinary actions against the licence, a fine and a public reprimand, both dated 1 June 2026. A third marketed entity, LHCM Ltd, is described in the site’s own footer as regulated by the FCA, but no FRN, company number, or address is published for it anywhere we fetched, so that claim isn’t independently checkable the way the other two are. The Cyprus company registration (HE 293592) and the Hong Kong company number (68841937) were not checked in this pass, and neither was the DIFC representative office registration (CL7447), since the issuing authority isn’t named on the site. Set against a UK-authorised competitor, the Cyprus Investor Compensation Fund caps eligible claims at 20,000 EUR per client, well under the FSCS’s £85,000, which matters for anyone comparing compensation exposure rather than just licence status.
What EXANTE charges, and why fees score high
The published cost structure is narrow and mostly avoidable rather than broad and hidden. Stocks and ETF custody costs nothing; bond custody runs 0.3% a year. An inactivity fee of 50 EUR a month only applies if all three conditions hold at once: no trade in 90 days, no open positions, and a balance under 5,000 EUR. Trading through the dealing desk costs 90 EUR per trade, and a manual close triggered by a margin call carries the same 90 EUR charge. Margin utilisation above 100% is billed at a rate equal to 100% a year on the amount above the line, a steep rate but one confined to a specific breach rather than baked into ordinary trading. Bank transfer deposits carry 0% exchange fees across a wide list of currencies including GBP, USD, EUR, and AUD. The one gap: overnight financing on short positions and FX is real but its rate is published only inside the client area, so it can’t be checked before funding an account, and deposit and withdrawal processing times weren’t verifiable from any page fetched in this review.
Platform and support
The offering is a single multi-currency account rather than tiered retail accounts, giving direct access to stocks, ETFs, bonds, options, futures, currencies and commodities from one login, synchronised across desktop, web, and mobile with API access; there’s no MetaTrader integration. The platforms page also describes FIX/HTTP API connectivity for existing infrastructure and direct execution from Bloomberg EMSX, positioning this toward professional and institutional users rather than first-time retail traders. Support runs through email, phone lines for Cyprus, the UAE, and Poland, live chat inside the client area, a help centre, and a dedicated relationship manager, backed by registered offices in Limassol and the DIFC.
Why reviews lag the rest of the score
The reviews component sits at 5.7, the lowest of the five, and the entity structure explains some of the caution behind it: three brands share the EXANTE name in site footers, one of them backed by a licence number nobody can look up, and a lapsed FCA registration sits under a legal name the firm itself links to its active one. Set against that, a search across 1,444 warning-list entries mirrored from CySEC, the FCA, and the FSC Mauritius turned up no match for the firm, and the site carries its own warning about fraudulent lookalike sites using its name and logo.
EXANTE gives professional and institutional traders single-account access to stocks, ETFs, bonds, futures, and options with low custody fees and a CySEC licence backing it, but a lapsed FCA entity sharing its brand name and an unverifiable Hong Kong-marketed sister firm hold the overall score to 7.5 out of 10.
What we saw
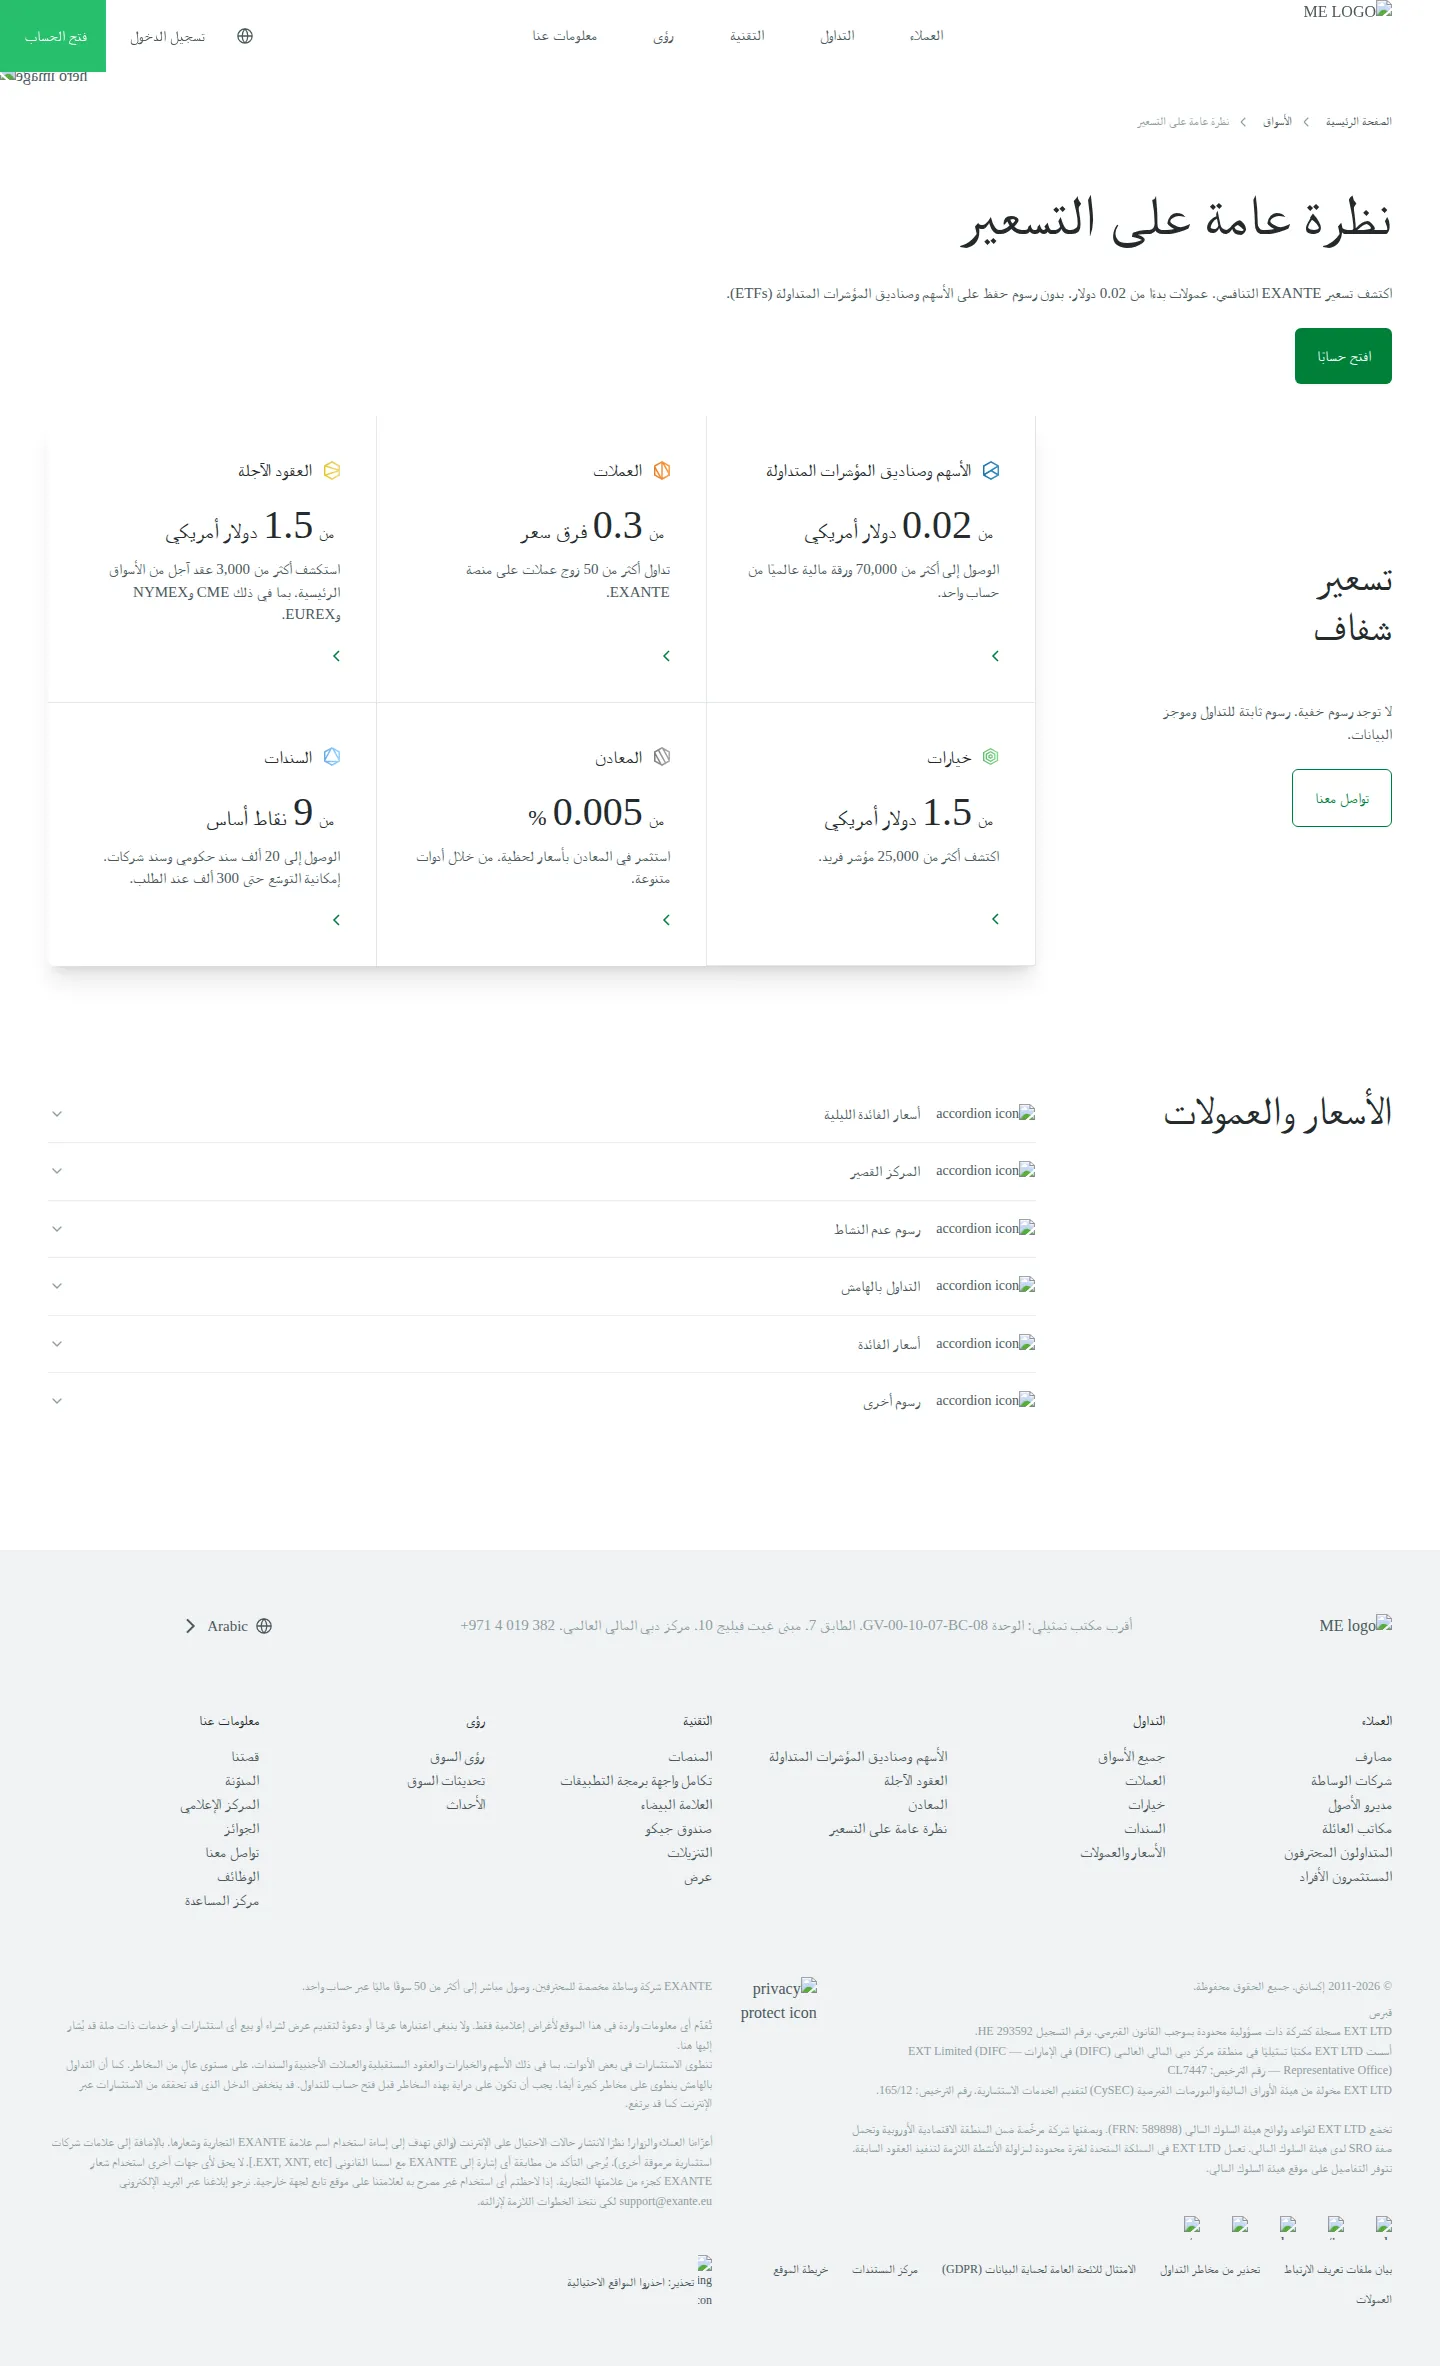
Pages captured from EXANTE’s own site when this review was written. Brokers change their terms; these are what we read.
Score history
Recomputed daily; every move is on the record. The current score is always the latest row.
| Date | Score | Move |
|---|---|---|
| 2026-10-08 | 7.5 | ▲ |
| 2026-09-13 | 5.8 | ▼ |
| 2026-09-12 | 6.3 | ▼ |
| 2026-07-27 | 7.0 | ▲ |
| 2026-07-26 | 6.8 | · |
FAQ
Is EXANTE regulated?
Yes, its Cyprus entity EXT Ltd holds a confirmed CySEC licence (165/12). Its FCA licence is a Supervised Run-Off closed to new UK clients, and its Hong Kong SFC licence is active but carries a June 2026 fine.
What does EXANTE charge for trading?
A round turn on 1 lot of EURUSD is quoted from USD 3.00, published as a ‘from’ spread rather than a fixed price. Minimum deposit is not published.
Is EXANTE's FCA licence open to new UK clients?
No. FCA licence 589898 is listed as a Supervised Run-Off, which covers only pre-existing UK contracts and does not accept new retail clients.
What is LHCM Ltd and is it FCA regulated?
LHCM Ltd is a brand entity named in EXANTE’s current marketing as ‘regulated by FCA (UK),’ but no FRN, company number or address is published for it, so the claim can’t be verified.
Has EXANTE had any regulatory issues?
Its Hong Kong entity, XHK Limited, holds an active SFC licence (BNN565) that carries a June 2026 fine and public reprimand on the register.
How can I contact EXANTE support?
By email, live chat or a published phone number, with staff available in the client’s own language and published hours covering around the clock.
How this review works
Track EXANTE live: score moves and red notices, in your pocket.