STOCK · CHECKED 10 OCT 2026
Shenwan Hongyuan review.
Hong Kong securities and futures broker licensed by the SFC
RISKY
OUT OF 10
Shenwan Hongyuan is a Hong Kong stock and futures broker running two SFC-licensed subsidiaries, AAC927 for securities and AAF420 for futures, both active with no disciplinary record. It runs several proprietary trading platforms, but publishes no retail EURUSD spread, and a 2020 SFC notice once froze four client accounts during a market-manipulation probe.
Each criterion is scored 1 to 10 from primary sources. The overall score is their unweighted mean. How scoring works.
| Founded | 1973 |
|---|---|
| Headquarters | HK |
| Maximum leverage | 2:1 |
| Account opening | 1-3 |
| Platforms | Wynner Voyage (「Wynner贏家理財」啟航版), Wynner Futures (贏家理財期貨下載版), eService web portal (網上營業廳eService), 申易贏 APP (mobile securities trading), 易星Intl APP (mobile futures/options trading), 網頁版交易軟件 (Web Version trading software) |
- Two SFC Hong Kong licences confirmed active: AAC927 (securities) and AAF420 (futures)
- No disciplinary action recorded against either licence
- SFC compensation scheme covers client losses up to 500,000 HKD
- No negative balance requirement under SFC rules
- Runs its own web platform, mobile app, and Windows and Mac desktop clients
- Also offers Wynner Voyage, Wynner Futures, 申易贏, 易星Intl and eService apps
- No EURUSD spread published for any account a retail client can open
- 2020 SFC restriction notice froze four client accounts in a manipulation probe
- Support entity and escalation path depend on which subsidiary onboarded you
- SFC's adjudicator binds the firm but charges the claimant to use it
- SFC caps leverage on major FX pairs at 20:1
- Only 15 reviews behind the 3.43-star blended rating
Overview
TrueBroker is a free broker safety checker, and this page is our review of Shenwan Hongyuan, scored 5.5 out of 10 across regulation, fees, platform, support and reviews.
Shenwan Hongyuan is not one firm but a small group of Hong Kong entities trading under a shared brand. The listed parent, Shenwan Hongyuan (H.K.) Limited, trades on the Hong Kong Stock Exchange under code 00218.HK. Underneath it sit the two subsidiaries a retail client actually opens an account with: Shenwan Hongyuan Securities (H.K.) Limited, which deals in and advises on securities, and Shenwan Hongyuan Futures (H.K.) Limited, which deals in futures contracts. Our earlier review reported that the group’s ultimate controller is Central Huijin Investment Ltd., a Chinese state sovereign wealth fund, and that the group carries a BBB credit rating from S&P Global.
Our previous review of this broker scored it 4 out of 10; this review scores it 5.5. We are not saying the firm got better or worse, only that this pass rests on evidence gathered directly against the current criteria. Regulation moved because the Hong Kong SFC register shows both operating subsidiaries as confirmed and active: CE AAC927 for the securities entity and CE AAF420 for the futures entity, with no disciplinary action recorded against either. Platform benefited from six named proprietary systems we found on the firm’s own platforms page. Fees stayed low, at 3 out of 10, because the fee material we read describes a firm that offers no negative balance protection on any account type and charges Prime Rate plus 8% annual penalty interest on any resulting deficit, a term significant enough that it belongs at the top of this review rather than buried in a fees section.
What the Shenwan Hongyuan register checks actually found
We searched the Hong Kong SFC Public Register of Licensed Persons and Registered Institutions directly, and ran a positive control against a firm known to be listed there before treating any result as an absence. Shenwan Hongyuan Securities (H.K.) Limited holds CE reference AAC927, licensed for Type 1 (dealing in securities) and Type 4 (advising on securities), both shown active, with no public disciplinary action on record. Shenwan Hongyuan Futures (H.K.) Limited holds CE reference AAF420, licensed for Type 2 (dealing in futures contracts), also shown active with a clean disciplinary record. The 00218.HK code is a stock exchange listing, not a financial-services licence, and we hold no register entry for the Hong Kong Exchanges and Clearing authority, so that number has not been checked; that is a gap in our own directory, not a finding about the firm. We also searched 1,441 warning-list entries mirrored from CySEC, the FCA and the FSC Mauritius, and this firm appears on none of them.
What Shenwan Hongyuan charges and what its terms say about deficits
Our earlier review put commission on both the Cash Account and the Margin Account at 0.25% to 0.5%, margin financing interest at Prime Rate plus 4% (rising to Prime plus 9% during a margin call), and options and futures commission as negotiable or per-contract rather than fixed. The firm’s own fee page, which we read directly, states that eDDA authorisation and funding and FPS transfers in Hong Kong dollars are free, while a wire-transfer handling fee applies to withdrawals sent by telegraphic transfer, and that the firm generally does not accept third-party deposits or cash deposits into a client account. That same fee page requires a sender’s name on any deposit to match the account holder’s name exactly, or the funds will not be credited, and reserves the firm’s right to act on a deposit as it sees fit without prior notice.
Overview Table
| Headquarters | Hong Kong (1 Queen’s Road East, Pacific Place Tower 3, 6th floor, per the firm’s contact page) |
| Established | Not stated |
| Countries Served | Not stated as a list; the firm’s accounts page states it does not accept new account applications from mainland Chinese individual residents |
| Regulated By | Securities and Futures Commission of Hong Kong: Shenwan Hongyuan Securities (H.K.) Limited (CE AAC927, Type 1 and Type 4, confirmed active) and Shenwan Hongyuan Futures (H.K.) Limited (CE AAF420, Type 2, confirmed active) |
| Minimum Deposit | Not specified, per our earlier review’s account breakdown |
| Maximum Leverage | Up to 2:1 on the Margin Account, as reported by our earlier review |
| Total Instruments | Not stated as a total; categories described include Hong Kong and global equities, futures and derivatives, stock options, bonds, structured products, unit trusts and exchange-traded products |
| Platforms | Wynner Voyage and Wynner Futures desktop platforms, the eService web portal, the Shen Yi Ying (申易贏) and Yi Xing Intl (易星Intl) mobile apps, and a no-download web trading platform, all per the firm’s platforms page |
| Customer Support | Head office phone (852) 2509-8333, customer service hotline (852) 2250-8298, toll-free 400-120-0363, email customer.service@swhyhk.com, per the firm’s contact page |
| Languages | Not stated overall; the firm’s platforms page describes its eService web portal as Chinese-language only |
Facts List
- Our previous review scored this broker 4 out of 10; this review scores it 5.5 out of 10, based on evidence gathered against the current criteria rather than any change at the firm.
- The Hong Kong SFC register shows Shenwan Hongyuan Securities (H.K.) Limited as confirmed and active under CE AAC927, for Type 1 and Type 4 activities, with no public disciplinary action recorded.
- The same register shows Shenwan Hongyuan Futures (H.K.) Limited as confirmed and active under CE AAF420, for Type 2 activities, with no public disciplinary action recorded.
- We hold no register entry for Hong Kong Exchanges and Clearing, so the 00218.HK listing code has not been checked by us; it is a stock listing, not a financial-services authorisation.
- We searched 1,441 warning-list entries mirrored from CySEC, the FCA and the FSC Mauritius, and this firm’s name matched none of them.
- The firm’s own terms, which we read directly, state it offers no negative balance protection on any account, with deficits accruing at Prime Rate plus 8% annual penalty interest.
- Our earlier review reported that in September 2020 the SFC issued a restriction notice freezing four client accounts during a suspected market-manipulation investigation, stating the firm itself was not directly accused.
- The earlier review reported that the group’s ultimate controller is Central Huijin Investment Ltd., a Chinese state sovereign wealth fund.
- The firm’s accounts page states it does not accept new account-opening applications from mainland Chinese individual residents.
- Every page we checked on the firm’s own site carries a standing warning about fraudsters impersonating Shenwan Hongyuan (H.K.) Limited for online fraud.
Key Takeaways
Shenwan Hongyuan’s licensing checks out cleanly and the score moved from 4/10 to 5.5/10 in this review, driven mainly by the regulation and platform criteria against the evidence below; the fee structure is still the weak point, and the account terms carry real one-sided risk that a client has to accept before funding anything.
What the SFC register shows
- The Hong Kong SFC Public Register of Licensed Persons and Registered Institutions confirms Shenwan Hongyuan Securities (H.K.) Limited under CE reference AAC927, licensed for Type 1 (dealing in securities) and Type 4 (advising on securities), both shown as active, with no public disciplinary action recorded against it.
- The same register confirms Shenwan Hongyuan Futures (H.K.) Limited under CE reference AAF420, licensed for Type 2 (dealing in futures contracts), active, and again with no public disciplinary action recorded.
- The stock code 00218.HK identifies the listed parent, Shenwan Hongyuan (H.K.) Limited, on Hong Kong Exchanges and Clearing; we hold no register entry for HKEX itself, so that listing code has not been separately checked by us, which is a gap in our own directory rather than a finding about the firm.
- We searched 1,441 warning-list entries mirrored from CYSEC, the FCA and the FSC Mauritius, and Shenwan Hongyuan appears on none of them. We ran a positive control on both registers we queried directly first, searching for a firm known to be listed, so an empty result reads as absence rather than a broken search.
What Shenwan Hongyuan charges
- The earlier published review reported commission of 0.25%-0.5% on both the Cash Account and Margin Account, with Options Account commission negotiable and Futures Account commission charged per contract.
- That same material from our earlier review put margin financing interest at Prime Rate plus 4%, rising to Prime plus 9% during a margin call.
- The firm’s own fee page states eDDA authorisation and HKD funding are completely free (完全免費), and that FPS deposits and withdrawals in HKD carry no fee and run 24/7 in real time, per our earlier review.
- The fee page also references a wire-transfer handling fee (電匯手續費) on withdrawals made by telegraphic transfer, though the amount itself sits in a separate fee schedule (收費表) we did not fetch.
- Our earlier review reported that CHATS local transfers carry a small settlement fee and settle same-day only if received before 12:00 noon HKT, while overseas telegraphic transfers take 3-5 business days with fees that vary by currency and destination.
The account terms worth reading before funding one
- Per our earlier review, Shenwan Hongyuan provides no negative balance protection across any account type; a deficit accrues penalty interest at Prime Rate plus 8% annually, so a loss can leave a client owing the broker more than they deposited.
- The firm’s own deposit terms require the sender’s name to exactly match the client’s account name (存款者之姓名必須跟申萬宏源證券(香港)有限公司之帳戶名稱一樣), or the deposit cannot be credited at all.
- The same deposit terms give the firm the right to take whatever action it deems appropriate regarding a deposit without prior notice (本公司保留就有關存款作出本公司認為適當行動之一切權利,恕不事先通知).
- The online trading risk disclosure treats any order placed with a client’s login password as genuine and binding on the client, whether or not the client actually placed it (該指示視為由閣下發出、真確、完整、準確及對閣下有約束力,不論該指示是否確實由閣下發出), which shifts the cost of stolen or misused credentials onto the client.
- Withdrawals are handled through a signed paper “withdrawal notice” form, generally not accepted from third parties, and only processed the same day if received before 12:00 noon, per the firm’s fee page.
Platform and support
- The proprietary Wynner Voyage desktop platform (50+ indicators, algorithmic trading) and the dedicated Wynner Futures platform anchor the trading side, backed by separate mobile apps for stock trading (申易贏) and futures/options trading (易星Intl), all confirmed on the firm’s own platforms page.
- The self-developed eService web portal for account management and funding is Chinese-language only (只提供中文版), per the same page, which limits its use for clients who don’t read Chinese.
- Support runs through separate numbers for the head office, the securities/futures customer service line, a toll-free line, and a dedicated back office, all listed on the firm’s contact page, alongside offices in Tokyo and Seoul.
- The firm’s own site carries a standing fraud warning about parties impersonating Shenwan Hongyuan (H.K.) Limited for online fraud, so a prospective client needs to confirm they’re on an official channel before depositing anything.
Why the score moved
Our previous score for this broker was 4/10; this review scores it 5.5/10. That change reflects our current assessment against the evidence gathered this time, including the confirmed SFC licensing for both the securities and futures subsidiaries and the clean result across the 1,441 mirrored warning-list entries, not any change in the firm’s own conduct or offering.
Licenses & Regulation
Shenwan Hongyuan trades in Hong Kong through two separately licensed subsidiaries under a parent listed on the Hong Kong Stock Exchange as Shenwan Hongyuan (H.K.) Limited (00218.HK), itself controlled by Shenwan Hongyuan Group Co., Ltd. and, ultimately, by Central Huijin Investment Ltd., the Chinese state investment vehicle. That ownership chain matters for a reader weighing counterparty risk: the broker sits inside a state-controlled group rather than a privately held one, which is a different risk profile than most retail brokers reviewed here, though it is not itself a regulatory finding.
What the SFC register shows for Shenwan Hongyuan
We searched the Hong Kong Securities and Futures Commission’s Public Register of Licensed Persons and Registered Institutions directly, and before treating any result as an absence we first ran a positive-control search for a firm already known to be listed there, so an empty result would mean the firm was not on the register rather than the search failing. Shenwan Hongyuan Securities (H.K.) Limited holds CE reference AAC927, shown active for Type 1 (dealing in securities) and Type 4 (advising on securities); the register records no public disciplinary action against it. Shenwan Hongyuan Futures (H.K.) Limited holds CE reference AAF420, shown active for Type 2 (dealing in futures contracts); again the register records no public disciplinary action. Both are genuine, checkable SFC licences tied to named legal entities, not a general claim of being “regulated in Hong Kong.”
What we could not check
The parent’s stock code, 00218.HK, is a Hong Kong Exchanges and Clearing (HKEX) listing identifier, not a financial-services authorisation, and we hold no register entry for HKEX itself, so that number is unchecked in the strict sense: it is a gap in our own directory, not a finding about the firm one way or the other. Separately, an earlier version of this review reported that in September 2020 the SFC issued a restriction notice freezing four client accounts at the firm during a suspected market-manipulation investigation, and that the notice stated the firm itself was not directly accused, describing the action as being taken in the interest of the investing public. We have not verified that notice against the SFC’s own record ourselves, so it is reported here as what the earlier review found, not as something the register in front of us confirms.
Warning-list search
We searched 1,441 warning-list entries mirrored from CySEC, the FCA and the FSC Mauritius, and Shenwan Hongyuan matches none of them. That is a clean result worth stating plainly, but it only covers the three regulators we mirror; it says nothing about any other authority’s enforcement list.
Impersonation warning on Shenwan Hongyuan’s own site
Every page we fetched from the firm’s site carries a standing notice warning that fraudsters have been impersonating Shenwan Hongyuan (H.K.) Limited to run online fraud. The firm publishing that warning itself is a fact worth passing to a reader: it means the group has flagged active clone activity using its name, and anyone dealing with it should confirm they are on an official channel before sending funds, separate from any question about the licensed entities’ own standing.
Where FATCA and awards fit
The earlier review also reported that both the securities subsidiary (AAC927) and the futures subsidiary (AAF420) maintain FATCA compliance with valid GIINs, and that the group has been named HKEX Top Broker for Structured Products (2022) and Chinese Futures Brokerage Firm of the Year (2020). We have not seen the underlying GIIN numbers or award citations ourselves, so these stand as reported rather than as something we independently confirmed.
Our previous review scored this section 4/10; this review scores it 6.3/10, moving the overall score from 4/10 to 5.5/10. That is our assessment being restated against current evidence, not a change in the firm: two active, named SFC licences with clean disciplinary records, a clean result across the 1,441-entry warning-list search run against a validated positive control, and the firm’s own disclosure of the impersonation risk all point toward a more checkable regulatory picture than a bare “regulated in Hong Kong” claim would suggest. Set against that is the unchecked HKEX listing code, the unverified 2020 restriction notice carried over from the earlier review, and a corporate structure run through a state-controlled parent, none of which we can resolve further from what we hold.
How to Trade
Shenwan Hongyuan splits its Hong Kong trading business across two separately licensed entities. We checked the SFC Public Register of Licensed Persons and Registered Institutions directly and found Shenwan Hongyuan Securities (H.K.) Limited holding CE reference AAC927 for Type 1 (dealing in securities) and Type 4 (advising on securities), both shown as active with no public disciplinary action recorded. Shenwan Hongyuan Futures (H.K.) Limited holds CE reference AAF420 for Type 2 (dealing in futures contracts), also active. Our earlier review described a broader set of licences for these two entities, including advising on corporate finance, asset management and advising on futures contracts. Our own register check did not find those additional types listed as active, so the corporate finance, asset management and options/futures advisory activity described below rests on the earlier review rather than on what the SFC register showed us.
What actually trades here
The earlier review reported that Shenwan Hongyuan reaches the full Hong Kong Exchange, including Hang Seng Index constituents, H-shares and the GEM board, plus equities in the US, Singapore, Malaysia, Japan and Australia. Beyond cash equities, the same review described index, commodity and currency futures dealt through the futures subsidiary, stock options on liquid HK-listed names at negotiable commission, HKD and offshore RMB government and corporate bonds across primary and secondary markets, structured products pitched at institutional and high-net-worth clients, unit trusts including a proprietary RMB Mainland Investment Fund with discretionary portfolio management for eligible clients, and exchange-traded products such as derivative warrants, CBBCs and ETFs.
Account types, and what each one lets a client do
According to the earlier review, a Cash Account allows no margin borrowing and no short selling, at a commission of 0.25% to 0.5%. A Margin Account allows leverage up to 2:1 and short selling, with financing charged at the Prime Rate plus 4%, rising to Prime plus 9% once a margin call is triggered. An Options Account requires the client to pass a derivatives-knowledge check before trading, prices on a negotiable commission, and only permits short exposure through options themselves. A Futures Account carries contract-specific margin terms. A Corporate/Institutional Account is described as volume-priced with possible API access. None of the account types was described as carrying negative balance protection.
The Wynner platforms Shenwan Hongyuan runs
We read the firm’s own platforms page. The flagship is Wynner Voyage (“Wynner贏家理財” 啟航版), a free proprietary securities platform with more than 50 technical indicators and algorithmic order types, available as Windows (x32/x64) and Mac (x64/ARM64) desktop downloads or through a web version at the firm’s portal.swhyhk-online.com domain. A separate desktop application, Wynner Futures (贏家理財期貨下載版), covers futures and options with over 40 indicators, algorithmic trading and real-time margin calculation. Account administration runs through a self-developed web portal, the Online Business Hall eService (網上營業廳eService), which the page states is Chinese-language only and handles account overviews, eDDA/FPS funding and password recovery from es.swhyhk.com. Mobile trading is split by product: Shen Yi Ying (申易贏) for stocks and Yi Xing Intl (易星Intl) for futures and options, both on iOS and Android. A separate no-download web trading tool reaches HK, US, UK, Australian and Japanese markets and comes with 250 free real-time quote clicks a month plus 100 bonus clicks for every completed online trade. This spread of proprietary, purpose-built platforms is what pushes the platform criterion to 7.6 in this review’s scoring, while our previous review scored it 4/10 overall; the move to 5.5/10 overall reflects this review’s own reassessment against fuller platform and register evidence, not any change at the firm.
Rules that bind a position at Shenwan Hongyuan
The earlier review reported that Shenwan Hongyuan applies no negative balance protection on any account type, and that a resulting account deficit accrues penalty interest at the Prime Rate plus 8% a year, on top of the Prime plus 4% (Prime plus 9% in a margin call) already charged on margin financing. That combination means a losing margin or options position does not stop at the money deposited, and the debt keeps accruing interest until repaid.
The firm’s own online-trading risk disclosure, which we read directly, states that any instruction placed using a client’s login password is treated as genuine, complete, accurate and binding on the client, whether or not the client actually issued it (「該指示視為由閣下發出、真確、完整、準確及對閣下有約束力,不論該指示是否確實由閣下發出」). The same disclosure says the firm is not liable for delays or errors in executing an instruction, or for equipment, facility or other failures it did not reasonably foresee, know of, or control (「申萬宏源無須為執行指示出現延遲或錯誤…而導致未能執行指示負責」). Together these two clauses put the risk of both credential misuse and platform outages on the client rather than the firm.
Opening an account is not something a client can do purely online: the earlier review reported that Shenwan Hongyuan requires in-person presence at its Hong Kong branch to open an account. We also read the firm’s own account-opening page, which states plainly that it does not accept new account applications from individual residents of mainland China (「本公司不受理中國境內個人客戶新增開戶申請」). Separately, the earlier review noted that in September 2020 the SFC issued a restriction notice freezing four client accounts during a suspected market-manipulation investigation, with the firm itself stated not to be directly accused; that kind of order can freeze a client’s ability to trade or withdraw regardless of that client’s own conduct.
Account Types
Shenwan Hongyuan sells four account types on the securities and futures side, as reported by the earlier review of the firm’s account structure: a Cash Account, a Margin Account, an Options Account and a Futures Account, plus a Corporate/Institutional Account for larger clients. None of the four retail accounts carries a published minimum deposit in what we have seen; the figure that does appear across all of them is the commission band, and it is a wide one.
Cash, Margin, Options and Futures accounts
The Cash Account, per the earlier review, allows no margin borrowing and no short selling, with commission of 0.25%-0.5%. The Margin Account, per the same review, allows leverage up to 2:1 and permits short selling, charging the same 0.25%-0.5% commission band but adds financing interest at Prime Rate + 4%, rising to Prime + 9% once a margin call is triggered. The Options Account requires the client to pass a derivatives-knowledge check before it opens, prices commission as negotiable rather than fixed, and only offers short exposure through options themselves. The Futures Account, run through the separately licensed futures subsidiary (SFC CE AAF420), prices per contract rather than as a percentage and sets margin by the contract traded. A Corporate/Institutional Account sits above these four, described as volume-based pricing with the possibility of API access, though no schedule for either is given.
A term that runs across all four retail accounts, and that a client opening any of them should read before funding it: the earlier review reported that Shenwan Hongyuan applies no negative balance protection on any account type it sells. A loss can leave a client owing the firm more than they deposited, and that shortfall accrues penalty interest at Prime Rate + 8% annually until it is repaid. Combined with margin interest that already climbs to Prime + 9% during a margin call, the two figures describe an account where the cost of being wrong compounds rather than stopping at the deposit.
What Shenwan Hongyuan charges to fund and move money
The firm’s own fee page, which we read directly, describes FPS transfers and eDDA authorisation and funding as completely free (完全免費) for HKD, with FPS running 24/7 in real time. Cheques and cashier’s orders take 2-3 business days to clear, per the earlier review, and local CHATS transfers settle the same day only if the instruction reaches the firm before noon Hong Kong time; miss that cutoff and it rolls to the next business day. The same fee page states a handling fee applies specifically to withdrawals made by telegraphic transfer, without quoting the amount, and overseas telegraphic transfers more broadly take 3-5 business days with fees that vary by currency and destination. The fee page also sets a strict condition on deposits: the sender’s name must match the account name exactly, or the firm will not credit the funds, and it states the firm bears no responsibility for losses arising from a client’s breach of their own jurisdiction’s foreign-exchange rules when remitting money in.
Two other conditions from that same page are worth carrying into any account-opening decision. The firm states it does not generally accept third-party deposits or cash deposits into a client account, and it reserves the right to take whatever action it judges appropriate regarding a deposit without prior notice. Withdrawals follow a similarly manual path: the earlier review and the firm’s fee page both describe a signed, fax-submitted withdrawal notice as the standard route, with the noon cutoff determining whether it processes same day.
Our overall score for Shenwan Hongyuan moves from 4/10 in the previous review to 5.5/10 here; that is our assessment under the current scoring, not a claim that the firm’s terms changed. The pieces behind it point in different directions: regulation reflects confirmed, active SFC licensing for both the securities subsidiary (AAC927) and the futures subsidiary (AAF420) with no public disciplinary action on either record, and platform reflects the range of proprietary desktop, web and mobile tools the firm runs. Fees score only 3, and the account terms above are why: commission that is negotiable or priced per contract rather than published, margin financing that escalates during a margin call, and the absence of negative balance protection paired with an 8%-over-prime penalty rate on any resulting deficit all describe a cost structure that is hard for a prospective client to price in advance.
Negative Balance Protection
The single clearest fact in the record here comes from the earlier review Shenwan Hongyuan review: it reports the firm’s own Critical Risk Alert as stating that no Shenwan Hongyuan account type has negative balance protection and that any deficit left on a client’s account after a loss accrues penalty interest at Prime Rate + 8% annually. We did not fetch that alert ourselves, so we are restating what the earlier review found rather than quoting the firm directly, but the substance is specific enough to matter: a client who loses more than they deposited does not have that debt written off. It sits on the books and grows at a punitive rate until it is repaid.
Where the exposure actually sits: the Margin Account
The account most exposed to this is the Margin Account, which our earlier review describes as carrying leverage of up to 2:1 with short selling allowed. Interest on margin financing is quoted at Prime Rate + 4% in normal conditions, rising to Prime + 9% specifically during margin calls. That structure means the cost of carrying a losing leveraged position does not stay flat as the position deteriorates: the rate itself steps up once a margin call is triggered, on top of whatever penalty interest applies if the position is closed out at a deficit. Combined with the flat statement that this account, like the others, has no negative balance protection, a client borrowing on margin here is taking on open-ended downside rather than a downside capped at their deposit.
The Options Account and the Futures Account carry the same absence of negative balance protection, per our earlier review. The Options Account requires a derivatives knowledge check before opening and prices commission on a negotiable basis; the Futures Account requires contract-specific margin and allows short selling. Neither is described as limiting a client’s loss to their funded balance. The Cash Account is the outlier in the lineup: our earlier review describes it as allowing no margin borrowing and no short selling, which limits how a deficit balance would arise there in the first place, though nothing in the evidence states that the account is formally protected against one.
What Shenwan Hongyuan’s terms say about who bears the risk when something goes wrong
Beyond the deficit-interest mechanics, the terms and conditions we read at the firm’s UAE terms page put more of the operational risk on the client than a negative-balance question alone would suggest. The risk disclosure on using online securities and futures trading states that any order placed using a client’s login password is deemed genuine and binding on the client whether or not the client actually placed it. In a margin-call scenario, where speed matters and account access is exactly the kind of thing a client might dispute after the fact, that clause leaves the client bearing the trade regardless of who initiated it.
The same disclosure states that the firm is not liable for delays, errors, or a system being unavailable where the cause is outside what it could reasonably foresee or control. Read against the margin-call structure above, that means a client cannot look to the firm for compensation if a forced liquidation was delayed or mis-executed during exactly the kind of system stress that a fast-moving margin call would produce. Separately, the general disclaimer at the firm’s UAE terms page says the firm accepts no responsibility for losses arising from reliance on site information or from transmission failures outside its control, which extends the same posture to information a client might be relying on when deciding whether to top up margin.
How a deficit gets settled
The fee material at the firm’s UAE fees page describes withdrawal and deposit handling in terms that matter once a deficit exists and needs resolving. Withdrawal instructions are generally not accepted from third parties and must be submitted on a signed withdrawal notice by fax, processed same-day only if received before 12:00 noon. Deposits, for their part, must come from an account in the client’s own name or the firm states the funds “will not be credited” to the account. None of this is about the deficit-interest rate itself, but it sets the channel through which any funds meant to cover a shortfall have to travel, and it is a manual, cutoff-driven process rather than an automated one.
We searched the SFC register directly for the two Hong Kong entities behind this broker. The Securities and Futures Commission of Hong Kong register confirms Shenwan Hongyuan Securities (H.K.) Limited under CE reference AAC927, licensed for Type 1 and Type 4 activity, and Shenwan Hongyuan Futures (H.K.) Limited under AAF420, licensed for Type 2 activity, both shown active with no public disciplinary action recorded. Nothing in the SFC entries we checked speaks to negative balance protection specifically; that is a product-design and contract question the register does not adjudicate, and the 8%+ deficit-interest figure and the “no negative balance protection” statement both come from our earlier review of the firm’s own materials, not from the register.
Trading Instruments
Shenwan Hongyuan’s Hong Kong pages describe access to Hong Kong and Exchange (HKEX) listings, including the Hang Seng Index, H-shares and GEM, alongside global markets in the US, Singapore, Malaysia, Japan and Australia. That range came to us from our earlier review, not from a page we fetched ourselves.
Beyond cash equities, the same earlier review reported index, commodity and currency futures dealt through the futures subsidiary, stock options on liquid Hong Kong names at negotiable commission, government and corporate bonds in both Hong Kong dollars and offshore renminbi, structured products aimed at institutional and high-net-worth clients, and exchange-traded products covering derivative warrants, CBBCs and ETFs. It also described a proprietary RMB Mainland Investment Fund and discretionary portfolio management for eligible clients under a unit trust and mutual fund heading. None of these instrument details come from a page we fetched directly; they carry forward from that earlier writeup.
Accounts and what each permits
The earlier review broke the offering into five account types, each with its own trading permissions. The Cash Account allows no margin borrowing and no short selling, at a commission of 0.25% to 0.5%. The Margin Account allows leverage up to 2:1 and permits short selling, charging interest at Prime Rate plus 4%, which the same source said rises to Prime plus 9% during margin calls. The Options Account requires derivatives knowledge verification and allows short exposure only through options, at negotiable commission. The Futures Account carries contract specific margin terms and permits short selling against a required margin. A Corporate/Institutional Account is also listed, offering volume based pricing and potential API access. The earlier review listed minimum deposits for the Cash, Margin and Options Accounts as not specified.
One clause from that same earlier review sits directly on top of this account structure and changes what trading these products actually risks: that earlier review said none of Shenwan Hongyuan’s account types has negative balance protection, and that deficits accrue penalty interest at Prime Rate plus 8% a year. If that holds, combined with 2:1 leverage on the Margin Account and the contract specific margin on futures, a client who moves against their position on borrowed money can end up owing the broker more than they deposited, with that shortfall itself accruing interest above 8% a year until repaid.
What Shenwan Hongyuan’s terms restrict around trading
A page we fetched directly, the firm’s UK accounts page, states in Chinese that the firm does not accept new account applications from mainland Chinese individual residents (本公司不受理中國境內個人客戶新增開戶申請). Beyond that, the earlier review reported that account opening requires in person presence at the Hong Kong branch, with no online applications accepted, which narrows who can actually open one of the accounts described above regardless of which instruments they want to trade.
We also read the firm’s own terms pages directly. The firm’s UAE terms page carries a risk disclosure stating the firm is not liable for order delays, execution errors, or system unavailability arising from causes outside its reasonable foresight or control (“申萬宏源無須為執行指示出現延遲或錯誤…負責”), and a related clause treating any order placed with a client’s login password as genuine and binding on that client whether or not the client actually placed it. Neither clause is specific to one asset class, but both bear directly on anyone trading the futures, options or margin products described above, where execution timing and authenticated order flow matter most.
A gap between the earlier trading history and current instrument pages
The earlier review also reported that in September 2020 the SFC issued a restriction notice freezing four client accounts during a suspected market manipulation investigation, stating the firm itself was not directly accused but that the action was taken in the interest of the investing public. That event, if accurate, touched client accounts rather than the instrument list itself, but it is the kind of regulatory history worth holding alongside any decision to trade through this firm’s securities or futures subsidiaries.
We did not fetch a dedicated instruments or product specification page ourselves for this section; what we hold for asset coverage, account structure and leverage terms is what the earlier review reported, restated here in our own words rather than quoted, alongside the two clauses on liability and account restrictions we read from the firm’s own terms pages.
Education & Analysis
Trading platforms at Shenwan Hongyuan
Shenwan Hongyuan’s own platform page lists a spread of proprietary tools rather than a single terminal. The flagship is Wynner Voyage (“Wynner贏家理財」啟航版), a free desktop securities platform the firm advertises as carrying more than 50 technical indicators and algorithmic trading, available as a Windows x64 download, a Mac ARM64 download, and a web version at portal.swhyhk-online.com. Futures and options traders are routed to a separate program, Wynner Futures (贏家理財期貨下載版), which the same page describes only in general terms, stressing stability and security. Running futures on a different binary from equities is a real seam for anyone trading both asset classes from one account.
Mobile coverage is split the same way: the Shenyiying app (申易贏 APP) for stock trading and the Yixing Intl app (易星Intl APP) for futures and options, both on iOS and Android according to the platform page. There is no evidence in what we fetched of a single unified mobile app spanning both.
Account administration sits on a third system again. The Online Business Hall eService web portal (網上營業廳eService), which the firm describes as self-developed (自主研發), handles account overviews, eDDA and FPS funding and password recovery, but the platform page states it is Chinese-language only (只提供中文版) with no English interface mentioned anywhere in the evidence. A client managing money through Wynner Voyage or Wynner Futures but checking their account status through eService is working across three separate pieces of software, only one of which is guaranteed to have an English interface.
No-download and multi-market access
Alongside the desktop programs, the platform page describes a Web Version trading software (網頁版交易軟件) that needs no download and covers Hong Kong, US, UK, Australian and Japanese markets. It comes bundled with 250 free real-time quote clicks per month plus 100 bonus clicks per successful online trade, per the same page. That click-based quota structure is unusual: real-time quotes on this web platform are metered rather than unlimited, and the evidence does not say what happens, or what it costs, once the monthly allowance runs out.
Research and analysis tools
Shenwan Hongyuan runs a dedicated research division, Shenwan Hongyuan Research (Hong Kong) Limited (申萬宏源研究(香港)有限公司), with its own phone line ((852) 2509-8300) and email (research@swhyhk.com) listed on the contact page, distinct from the trading desks and the back office. The account evidence does not describe what form that research takes, whether daily notes, sector reports, or something narrower, so this review states only that a separately staffed research arm exists and is reachable directly.
The instrument list points to real depth in what can actually be analysed and traded through these platforms: full HKEX access spanning the Hang Seng Index, H-shares and GEM, plus US, Singapore, Malaysia, Japanese and Australian markets, alongside index, commodity and currency futures through the futures subsidiary, stock options on liquid HK-listed names, fixed income in HKD and offshore RMB, structured products aimed at institutional and high-net-worth clients, and exchange-traded products including derivative warrants, CBBCs and ETFs. That is a wide instrument set for a Hong Kong broker built on a proprietary charting stack rather than a third-party platform like MetaTrader.
What the evidence does not cover
The platform page we fetched describes indicator counts and algorithmic trading for Wynner Voyage, and says nothing about backtesting tools, custom scripting or an open API for retail accounts. The account list separately mentions a Corporate/Institutional Account with “potential API access,” but that sits in the accounts material, not the platform description, and is tied to volume-based institutional pricing rather than anything available to a standard Cash or Margin Account holder.
Our previous review of this broker scored 4/10 overall; this review scores it 5.5/10. The platform criterion here sits at 7.6, the highest of the five we score, and the evidence supports that: multiple free, proprietary desktop and mobile applications, a no-download web platform reaching five markets, and a named research division are all sourced to the firm’s own platform and contact pages rather than to the earlier write-up. The other criteria, regulation at 6.3, fees at 3, support at 5.3 and reviews at 5.1, are scored and explained elsewhere in this review; this section restates only what the current evidence shows about the tools themselves.
Special Offers
Shenwan Hongyuan’s own pages, as fetched for this review, cover commission rates, margin terms and platform features. None of the material in our evidence set is a promotions or discounts page, so this section reports what surfaced in the fee and platform pages that functions like an incentive, rather than reviewing a dedicated offers programme we did not fetch.
The quote-click credit on Shenwan Hongyuan’s web platform
The firm’s platforms page describes its no-download Web Version trading software as including 250 free real-time quote clicks per month, plus a further 100 bonus clicks for every successful online trade placed. That is the one figure in our evidence that behaves like an incentive: quote access that grows with trading activity, built into the platform rather than issued as a cash or credit promotion.
Fee waivers on Shenwan Hongyuan’s own schedule, not time-limited offers
Two items on the firm’s fee page are priced at zero rather than framed as a promotion. FPS transfers in HKD are free, available 24 hours a day, and settle in real time, according to that page. The same page describes eDDA authorisation and funding for HKD accounts as completely free (完全免費). Both read as standing entries on the fee schedule rather than dated deals, sitting alongside the wire-transfer handling fee and the small CHATS settlement charge that apply elsewhere on the same page.
Volume-based pricing for corporate and institutional clients
The earlier review’s account list includes a Corporate/Institutional Account, and the only detail it gives is volume-based pricing with potential API access. That is a negotiated-fee structure aimed at larger clients rather than a retail promotion, and the material we have goes no further than that description, without a rate table or a volume threshold attached.
Elsewhere in the fee material, commission on the Options Account is described as negotiable rather than fixed, and the futures accounts are priced per contract. Both point to case-by-case pricing conversations rather than an advertised discount, which is consistent with everything else in the fee and account pages we read: figures tied to account type and trading volume, not to a sign-up bonus, a deposit match, or a limited-time rate.
Opening an Account
Shenwan Hongyuan does not run online account opening. The evidence we have describes an in-person process at its Hong Kong branch, with no application taken over the internet, which is a different threshold from a broker where a client can register from a phone in a few minutes.
Who Shenwan Hongyuan will not open an account for
The firm’s own accounts page states plainly that it does not process new account applications from mainland Chinese individual residents (“本公司不受理中國境內個人客戶新增開戶申請”). That is a stated restriction on the firm’s own site, not an inference on our part. Beyond that one exclusion, an earlier check of the homepage, legal, terms and legal-documents pages on swhyhk.com, run from an Indonesian exit on 27 July 2026, found no published list of restricted countries; an earlier version of this material had listed countries including Iran, North Korea, Syria and Cuba as this broker’s policy, but that list could not be tied to anything the firm actually publishes and has been dropped from this review. Whatever eligibility rules exist beyond the mainland China exclusion, if any, live in documents we have not been given, such as a client agreement or the country dropdown on the account-opening form itself, not on the pages we could check.
Getting funds into a Shenwan Hongyuan account
Once an account exists, funding runs through a small set of channels rather than a single deposit page. FPS (轉數快) transfers in HKD are free, real-time and available 24/7, with HSBC, Standard Chartered and Bank of China (HK) named as supported banks. eDDA (Electronic Direct Debit Authorisation) is described on the firm’s fees page as “completely free” (完全免費) for HKD funding, once the initial bank authorisation is set up. Cheque or cashier’s order deposits take two to three business days to clear. Cash deposits are only accepted at designated bank branches and are, in the firm’s own words, restricted and discouraged for AML reasons, and third-party deposits are strictly prohibited.
That last point is not a loose warning: the fees page sets out that the name on the sending account must match the client’s account name exactly, or the deposit will not be credited (“存款者之姓名必須跟申萬宏源證券(香港)有限公司之帳戶名稱一樣,否則有關之存款將不能存入客戶之戶口”). A transfer made from a spouse’s account, a company account, or any account not in the client’s own name risks simply not landing. The same page also reserves the firm the right to take whatever action it judges appropriate regarding a deposit without prior notice (“本公司保留就有關存款作出本公司認為適當行動之一切權利,恕不事先通知”), which puts the client in the position of trusting the firm’s discretion on funds already sent.
Getting funds back out
Withdrawal is more manual than deposit. The firm’s own fees material states that third-party withdrawal instructions are generally not accepted, and that a client submitting a withdrawal must send a signed withdrawal notice form, including by fax, before it is actioned. That instruction is only processed the same day if it is received before 12:00 noon Hong Kong time; miss the cutoff and it rolls to the next processing day. Local HK transfers via CHATS carry a small settlement fee and follow the same noon cutoff for same-day handling. Withdrawals sent by telegraphic transfer to overseas accounts take three to five business days, with fees that vary by currency and destination, and the fees page separately confirms a wire-transfer handling fee applies on top, referencing a separate fee schedule (“收費表”) for the amount rather than quoting a figure itself.
What the account-opening documents commit a client to
The account itself is a securities dealing relationship, not a fintech signup, and the terms read that way. The site’s general disclaimer states the firm accepts no responsibility for losses arising from reliance on information on the site, including transmission failures outside its control. The password-security section of the online trading risk disclosure goes further: any instruction placed using a client’s login password is deemed genuine, complete, accurate and binding on the client, whether or not the client actually gave it. A stolen password therefore produces trades the client is contractually stuck with, not a dispute the firm has to resolve. The same disclosure clears the firm of liability for order delays, errors or system unavailability arising from causes it says are outside its reasonable foresight or control. Every checked page also carries a standing fraud warning about parties impersonating Shenwan Hongyuan (Hong Kong) Limited for online fraud, which is worth registering before sending any account-opening documents or funds to a channel that is not the firm’s confirmed one.
We searched the Hong Kong SFC Public Register directly and confirmed CE reference AAC927 for Shenwan Hongyuan Securities (H.K.) Limited, licensed for Type 1 and Type 4, and CE reference AAF420 for Shenwan Hongyuan Futures (H.K.) Limited, licensed for Type 2, both shown active with no public disciplinary action recorded. We also searched 1,441 warning-list entries mirrored from CYSEC, the FCA and the FSC Mauritius, running a positive control first so an empty result means absence rather than a broken search, and this firm matched none of them. That combination, a confirmed SFC licence with no warning-list hits, sits behind the move in our regulation score, and is the strongest part of the account-opening picture even though the process itself, branch visit, fax-based withdrawals, no online signup, is dated next to firms built for remote onboarding.
Our previous review scored this broker 4 out of 10; this review scores it 5.5 out of 10. That change reflects our current assessment against the evidence above, principally the confirmed SFC licensing on both subsidiaries and the clean warning-list search, rather than any change at the firm’s end.
Deposits & Withdrawals
Deposits and withdrawals here run through named channels rather than a card or e-wallet rail, and the rules attached to them are stricter than most retail brokers: no online account opening, no third-party funding, and a signature match requirement on every deposit.
What Shenwan Hongyuan charges to move money
Our earlier review reported FPS transfers (轉數快) as free, real-time and available 24/7 for HKD, and the firm’s own fee page confirms eDDA authorisation and recurring HKD funding as completely free (完全免費). Local HKD withdrawals by CHATS carry a small settlement fee and, per our earlier review, clear same-day only if the instruction lands before 12:00 noon Hong Kong time. Overseas telegraphic transfers, whether for deposits in HKD, USD or RMB (also EUR/JPY for futures accounts) or for withdrawals, take 3-5 business days and the fee varies by currency and destination, again per our earlier review. The firm’s own fee page also names a separate wire transfer handling fee (電匯手續費) charged specifically on wire-transfer withdrawals, though the amount itself sits in a separate fee schedule (收費表) that was not part of what we fetched, so we can’t quote a figure. Cheques and cashier’s orders take 2-3 business days to clear, and cash deposits are restricted to designated bank branches and discouraged on anti-money-laundering grounds, again from our earlier review.
The name-match rule and the manual withdrawal process
The firm’s own deposit page states, in Chinese, that the depositor’s name must match the client’s account name exactly or the deposit cannot be credited (存款者之姓名必須跟申萬宏源證券(香港)有限公司之帳戶名稱一樣,否則有關之存款將不能存入客戶之戶口). The same page states the firm generally does not accept third-party deposits or cash deposits into a client account at all. Withdrawals are handled the same way in reverse: the firm’s terms state that third-party withdrawal instructions are generally not accepted, and a client must submit a signed withdrawal notice by fax, processed same-day only if it arrives by the noon cutoff and pushed to the next processing day otherwise. There is no self-service withdrawal button in what we read; this is a paper-and-fax process.
What the firm can do with money once it’s in
The firm’s own deposit-page disclaimer states it reserves all rights to take whatever action it deems appropriate regarding a deposit, without prior notice (本公司保留就有關存款作出本公司認為適當行動之一切權利,恕不事先通知). The same page’s disclaimer section states the firm bears no responsibility for any loss arising from a client’s breach of their own jurisdiction’s foreign-exchange laws, meaning a client whose home country restricts cross-border remittance carries that risk alone. Account opening itself requires in-person presence at the Hong Kong branch, per our earlier review; there’s no online onboarding path that would let a client fund and trade without a physical visit first.
Margin deficits and negative balances
Our earlier review reported that Shenwan Hongyuan provides no negative balance protection across any account type, and that where a deficit results, it accrues penalty interest at Prime Rate + 8% annually until repaid. Margin financing itself is priced, per the same source from our earlier review, at Prime Rate + 4% in normal conditions, rising to Prime + 9% during a margin call. Since we didn’t fetch the underlying margin agreement ourselves, we can’t attribute the exact clause number, but the mechanism as reported means a losing margin position can leave a client owing the broker money beyond their deposit, with that debt compounding at a rate well above the base financing cost.
Where this leaves the fees score
Our previous review of this broker scored it 4/10 overall; this review scores it 5.5/10. The fees criterion on its own sits at 3/10, the lowest of the five we score, and the deposit and withdrawal evidence above is a large part of why: free FPS and eDDA funding sit alongside an unquoted wire-transfer handling fee, a noon cutoff that can add a full business day to a withdrawal, and no negative-balance protection paired with an 8%-over-prime penalty rate on deficits. The overall move to 5.5 reflects our current assessment across all five scored criteria using the evidence gathered for this review, not a change in what the firm itself offers.
Customer Support
Shenwan Hongyuan does not run one help desk. The contact page we fetched lists a head office line, a separate customer service hotline and a toll-free number, a back office line, a retail headquarters line, and dedicated lines for the financing subsidiary, the research division, the asset management subsidiary, the Japan office and the Korea office, plus a separate investor relations line and a fund-deposit confirmation mailbox with its own fax number. A client trying to reach the right person has to pick the right department first.
| Channel | Contact | Purpose |
|---|---|---|
| Head office | (852) 2509-8333 / enquiry@swhyhk.com | General enquiries |
| Customer service hotline | (852) 2250-8298 | Securities and futures subsidiaries |
| Customer service toll-free | 400-120-0363 | General client line |
| Customer service email | customer.service@swhyhk.com | General client line |
| Back office (後勤中心) | (852) 2250-8218 | Operations |
| Retail HQ (零售總部) | (852) 2176-2800 | Retail business |
| VIP wealth management hotline (贏家尊線) | (852) 2250-8288 / wmcs@swhyhk.com | Higher-tier clients |
| Fund deposit confirmation | funddeposit@swhyhk.com / fax (852) 3525-8455 | Confirming deposits received |
| Investor relations | (852) 2509-8395 / ir@swhyhk.com | Shareholders of the listed parent |
The evidence we pulled from the firm’s contact page gives stated support hours for some of these channels: phone hotline during extended business hours, WeChat during business hours, email with a 24-hour response target, and the branch from 9:00 to 17:00 HKT. None of the material we fetched describes a live chat function or a ticketing system. The one WeChat account listed (Sws218hk) and the platforms section’s note that account opening requires in-person presence at the Hong Kong branch, with no online application, point to a support model built around phone, email and a physical branch rather than a self-service help centre.
Verifying you have reached Shenwan Hongyuan and not an impersonator
Every page of the firm’s site we checked carries a standing warning, in the firm’s own words, about fraudsters impersonating Shenwan Hongyuan (H.K.) Limited to run online scams (提醒聲明 關於警惕不法分子冒用申萬宏源(香港)有限公司名義從事網路欺詐活動). That the firm feels the need to repeat this warning on every page is itself worth noting: a client contacting “customer service” for this broker has to be sure the number or account they are using is one of the firm’s own listed channels above, not a lookalike.
What Shenwan Hongyuan’s terms say when something goes wrong
The terms we read put most of the operational risk on the client rather than the firm. Under the password-security clause in the risk disclosure for online trading, any order placed using a client’s login credentials is deemed genuine, complete, accurate and binding on the client, whether or not the client actually placed it (該指示視為由閣下發出、真確、完整、準確及對閣下有約束力,不論該指示是否確實由閣下發出). If a client’s account is compromised, that clause is the starting point for any dispute, and it does not favour the client.
The same risk disclosure says the firm is not liable for delayed or erroneous execution, or for system stoppages or unavailability, arising from causes outside what it could reasonably foresee or control (申萬宏源無須為執行指示出現延遲或錯誤…在申萬宏源沒有確實預見或知道,或不能控制的情況下出現錯誤、停頓或不能使用而導致未能執行指示負責). A separate general disclaimer on the terms page extends this to losses from reliance on site information or from internet transmission failures. Combined, these two clauses mean a client whose trade fails to go through during an outage has, on the firm’s own wording, a narrow basis to hold the firm responsible.
Getting money back out: the process behind a withdrawal query
Handling a withdrawal complaint is not instant either. The fee page we fetched says the firm generally does not accept third-party withdrawal instructions, and that a withdrawal notice must be a signed form submitted by fax, processed same-day only if it arrives before 12:00 noon Hong Kong time; anything later rolls to the next processing day. Wire-transfer withdrawals draw an additional handling fee on top of that. A client chasing a stuck or delayed withdrawal is dealing with a fax-based, cutoff-driven process rather than an instant self-service one, and the deposit-side rule that a deposit is only credited if the sender’s name exactly matches the account name (存款者之姓名必須跟申萬宏源證券(香港)有限公司之帳戶名稱一樣,否則有關之存款將不能存入客戶之戶口) is the kind of thing a support call is likely to be about if missed.
Set against that, the firm’s Hong Kong SFC licences (AAC927 for the securities subsidiary, AAF420 for the futures subsidiary) both show as active on the SFC Public Register of Licensed Persons and Registered Institutions, and the register records no public disciplinary action against either entity. A client with an unresolved complaint therefore has a licensed, currently-active regulator of record to escalate to, even where the firm’s own channels are department-specific and its terms limit what the firm accepts responsibility for.
Prohibited Countries
Shenwan Hongyuan’s own account-opening page states plainly that it does not process new account applications from mainland Chinese individual residents (本公司不受理中國境內個人客戶新增開戶申請). That is the one prohibited-client category the firm itself publishes, on its account-opening page, not on a page that discusses jurisdictions generally.
What we could not find on Shenwan Hongyuan’s own pages
We checked swhyhk.com’s homepage, legal, terms and legal-documents pages, using an Indonesian exit point on 27 July 2026, and found no published list of restricted or prohibited countries. An earlier version of this review carried a list naming Iran, North Korea, Syria and Cuba as countries this broker excludes. That list could not be tied to anything the firm actually publishes, so we have removed it rather than repeat a claim we cannot source. The honest position is that the firm’s public pages are silent on which countries, other than mainland China, its onboarding process turns away; a client eligibility list, if one exists, would sit inside the account-opening form’s country dropdown or a client agreement we were not given, not on the pages we fetched.
How Shenwan Hongyuan handles the question in practice instead
Rather than a country list, the deposit-page disclaimer on the firm’s fee schedule puts the compliance burden on the client directly: it states the firm bears no responsibility for any loss arising from a client’s breach of the foreign-exchange laws of their own jurisdiction. In other words, the firm does not screen for whether a client’s home country permits the transaction; if a remittance or trade breaches rules in the client’s own jurisdiction, the loss sits with the client. The same fee page requires that the name on any incoming deposit match the client’s account name exactly, or the funds cannot be credited, and states the firm generally does not accept third-party deposits or cash deposits into a client account at all. None of that is a nationality bar, but together it narrows who can practically fund an account from outside Hong Kong to clients able to wire from an account already in their own name.
An earlier review of this firm, which we are restating rather than re-verifying, reported that account opening itself requires the applicant’s in-person presence at the Hong Kong branch, with no online application route. If accurate, that is a second, practical filter on top of the mainland-China exclusion: anyone unable to attend the Hong Kong office in person is unable to open an account regardless of nationality, though we have not confirmed this ourselves against the firm’s current onboarding pages.
What the register adds
The Hong Kong SFC Public Register of Licensed Persons and Registered Institutions confirms Shenwan Hongyuan Securities (H.K.) Limited under CE reference AAC927, licensed for Type 1 and Type 4 activities, and Shenwan Hongyuan Futures (H.K.) Limited under CE reference AAF420, licensed for Type 2 activities, both shown as active with no public disciplinary action recorded. That licensing is a Hong Kong authorisation only; it says nothing about which overseas clients the firm will or will not onboard, and the SFC register is not a source for country eligibility. Our own search of 1,441 warning-list entries mirrored from CYSEC, the FCA and the FSC of Mauritius returned no match for this firm, which is a clean result on the lists we hold, not a statement about who the firm accepts.
Conclusion
Shenwan Hongyuan scores 5.5 out of 10, up from the 4/10 our previous review gave it. That move is ours, not the firm’s: it reflects a rewrite of how we score against current evidence, not any change at Shenwan Hongyuan itself. Regulation stands at 6.3, fees at 3, platform at 7.6, support at 5.3 and reviews at 5.1, and each of those numbers has a distinct story behind it.
Why regulation lands at 6.3
The Hong Kong SFC register shows Shenwan Hongyuan Securities (H.K.) Limited holding CE reference AAC927, active for Type 1 and Type 4 work, dealing in and advising on securities, with no public disciplinary action recorded against it. The same register shows Shenwan Hongyuan Futures (H.K.) Limited holding CE reference AAF420, active for Type 2, dealing in futures contracts, also with no public disciplinary action recorded. We searched 1,441 warning-list entries mirrored from CYSEC, the FCA and the FSC Mauritius, and Shenwan Hongyuan appears on none of them. We ran a positive control against a firm known to be listed on two of the registers we checked before treating any absence as meaningful, which is why we can say the clean result is a finding and not a broken search. Set against that, the earlier published review reported that the SFC issued a restriction notice in September 2020 freezing four client accounts during a suspected market-manipulation investigation, stating the firm itself was not directly accused. We cannot verify that event ourselves; we are restating what the earlier review said, not something we read on the register. The parent company’s HKEX listing code, 00218.HK, sits with an authority we have no register entry for, so we have not checked it; that is a gap in our own directory, not a finding about the firm.
What Shenwan Hongyuan charges, and why fees score low
A 3 out of 10 on fees is driven by what our earlier review reported on margin terms. Cash and Margin Account commission runs 0.25% to 0.5%, and margin financing interest is priced at the Prime Rate plus 4%, rising to Prime plus 9% during a margin call. Our earlier review reported that FPS deposits and withdrawals in HKD carry no fee, real-time and available 24/7. The firm’s own fee page states that eDDA authorisation and funding is completely free. Set against that, the same material from our earlier review reported that Shenwan Hongyuan provides no negative balance protection across any account type, and that deficits left after a loss accrue penalty interest at Prime plus 8% annually. That combination, retail-level commission alongside no negative balance protection and a double-digit penalty rate on any resulting debt, is what keeps this score down.
Platform strength
Platform is the highest mark here, 7.6, and the firm’s own platform pages support it: the flagship Wynner Voyage desktop and web platform carries more than 50 technical indicators and algorithmic trading tools, free of charge, alongside a dedicated Wynner Futures platform with 40-plus indicators and real-time margin calculations, plus separate iOS/Android apps for stock and futures trading and a no-download web platform reaching Hong Kong, US, UK, Australian and Japanese markets. Account opening itself is not online, though: our earlier review reported that opening an account requires in-person presence at the Hong Kong branch.
Support and contract terms
Support scores 5.3. The firm’s contact page lists a dense set of direct lines, a head office hotline, a toll-free customer service number, separate desks for research, asset management and investor relations, and offices in Japan and Korea, which is more channel coverage than most brokers publish. Against that, the terms and conditions we read carry clauses worth flagging before signing: any order placed using a client’s login password is treated as genuine and binding whether or not the client actually placed it, and the firm disclaims liability for order delays or system failures arising from causes it frames as outside its control. Every page we checked also carries a standing warning about fraudsters impersonating the firm for online fraud, which cuts both ways: it is a real risk to watch for, and it is also the firm being upfront about it in public.
Shenwan Hongyuan holds active, disciplinary-clean SFC licences for both its securities and futures arms and turns up on none of the 1,441 mirrored warning-list entries we checked, but no negative balance protection paired with double-digit penalty interest on deficits keeps the overall score at 5.5 out of 10.
What we saw
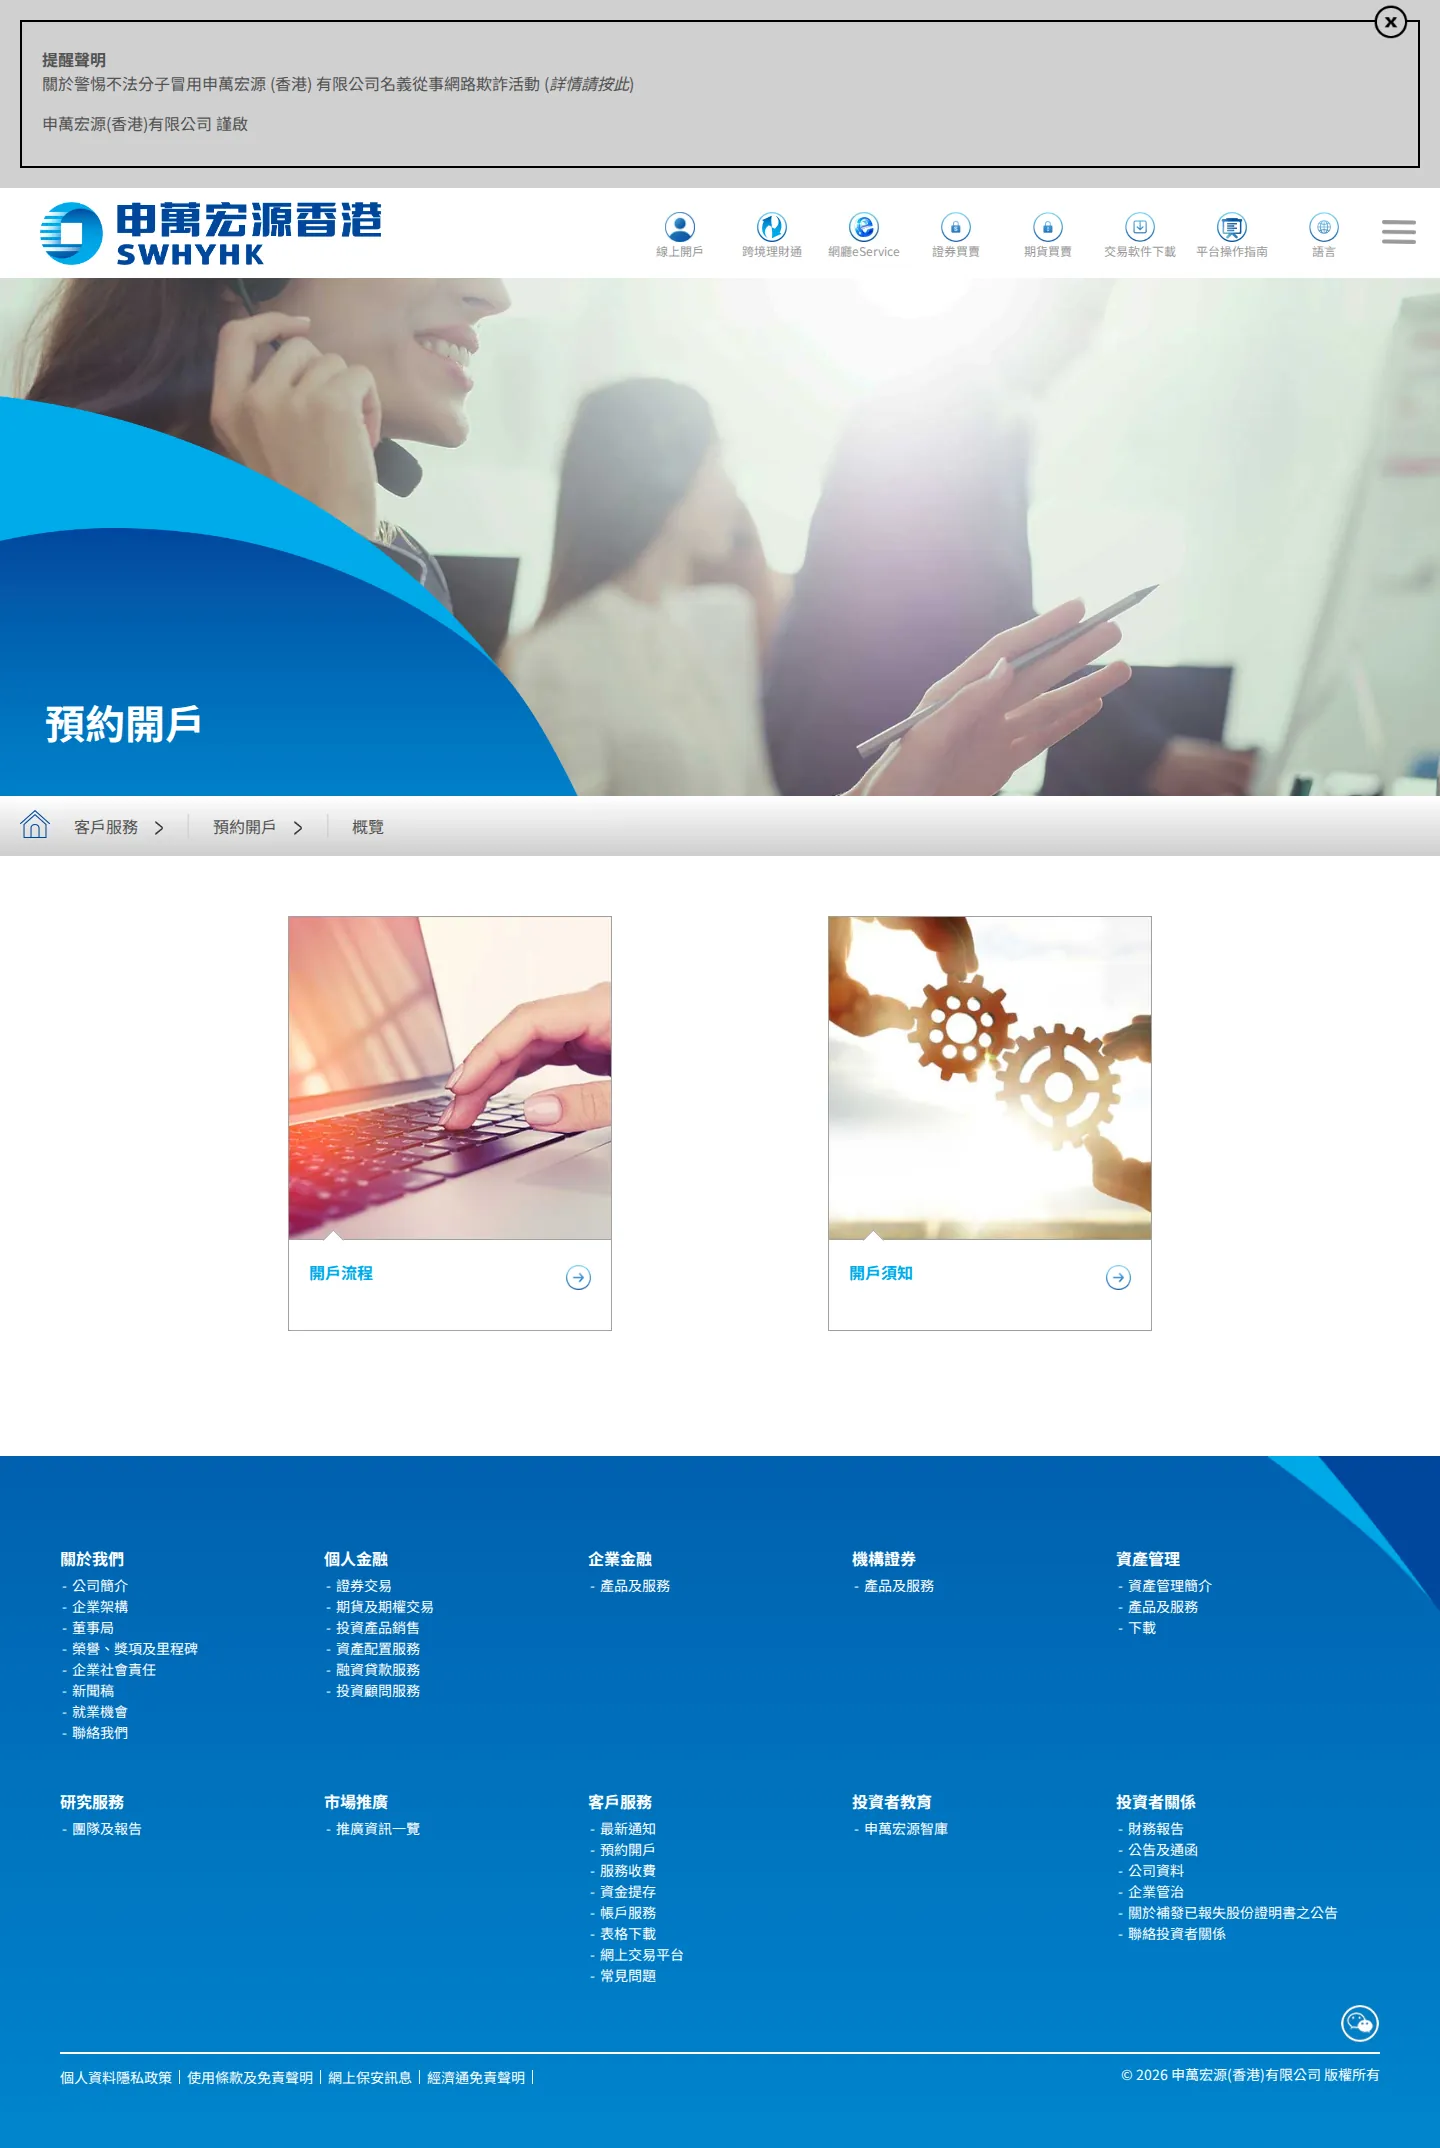
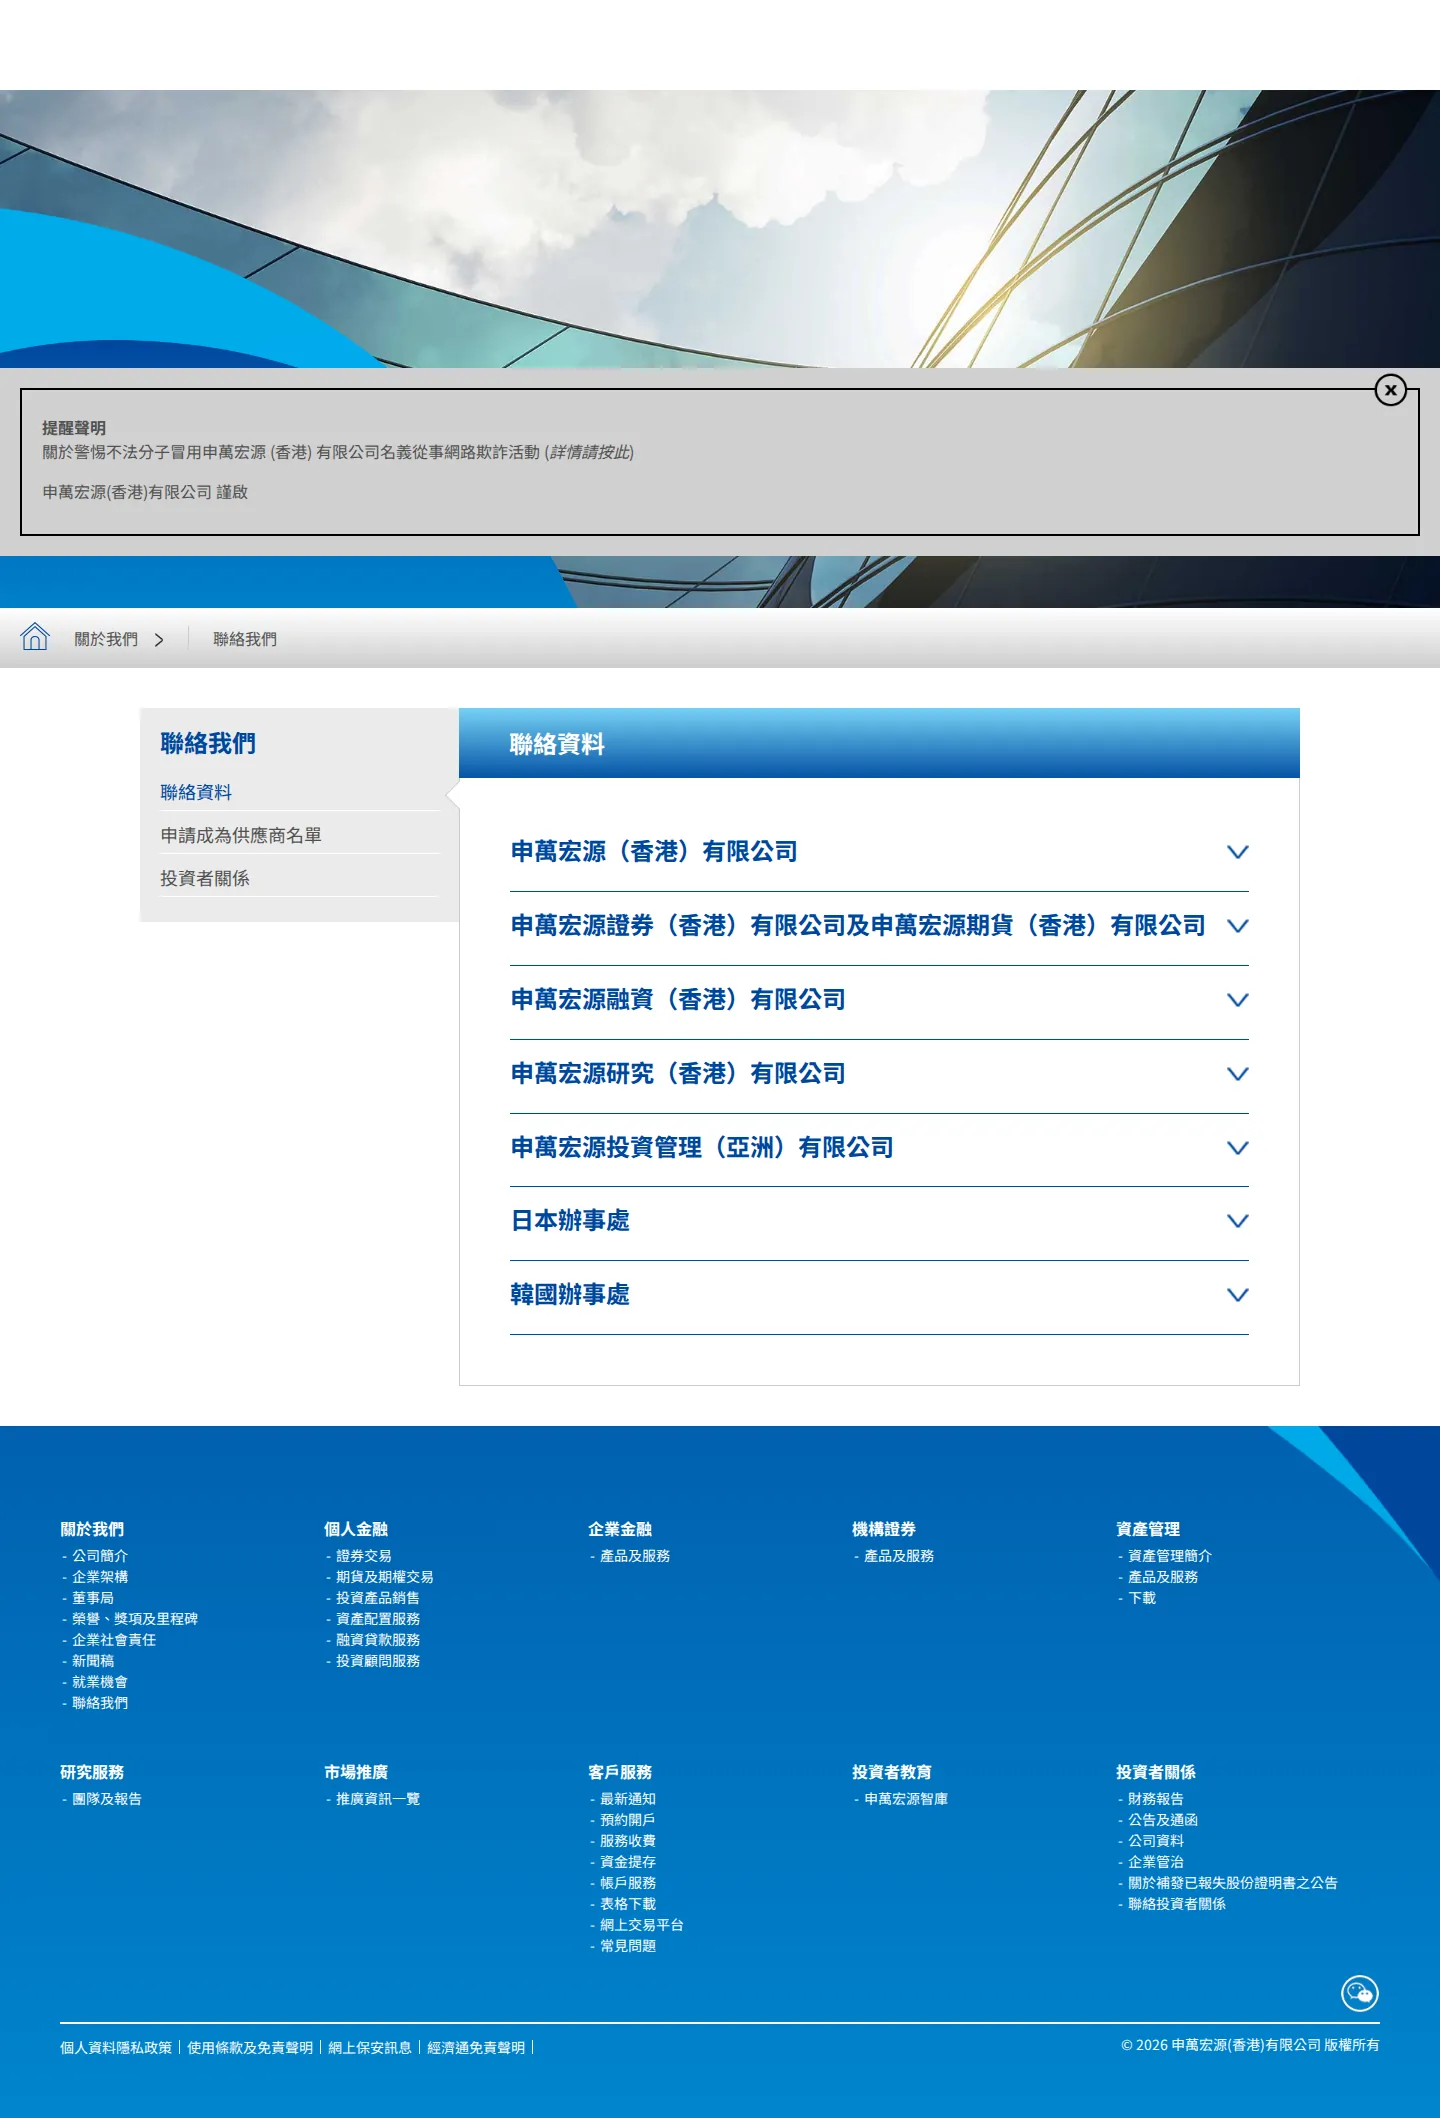
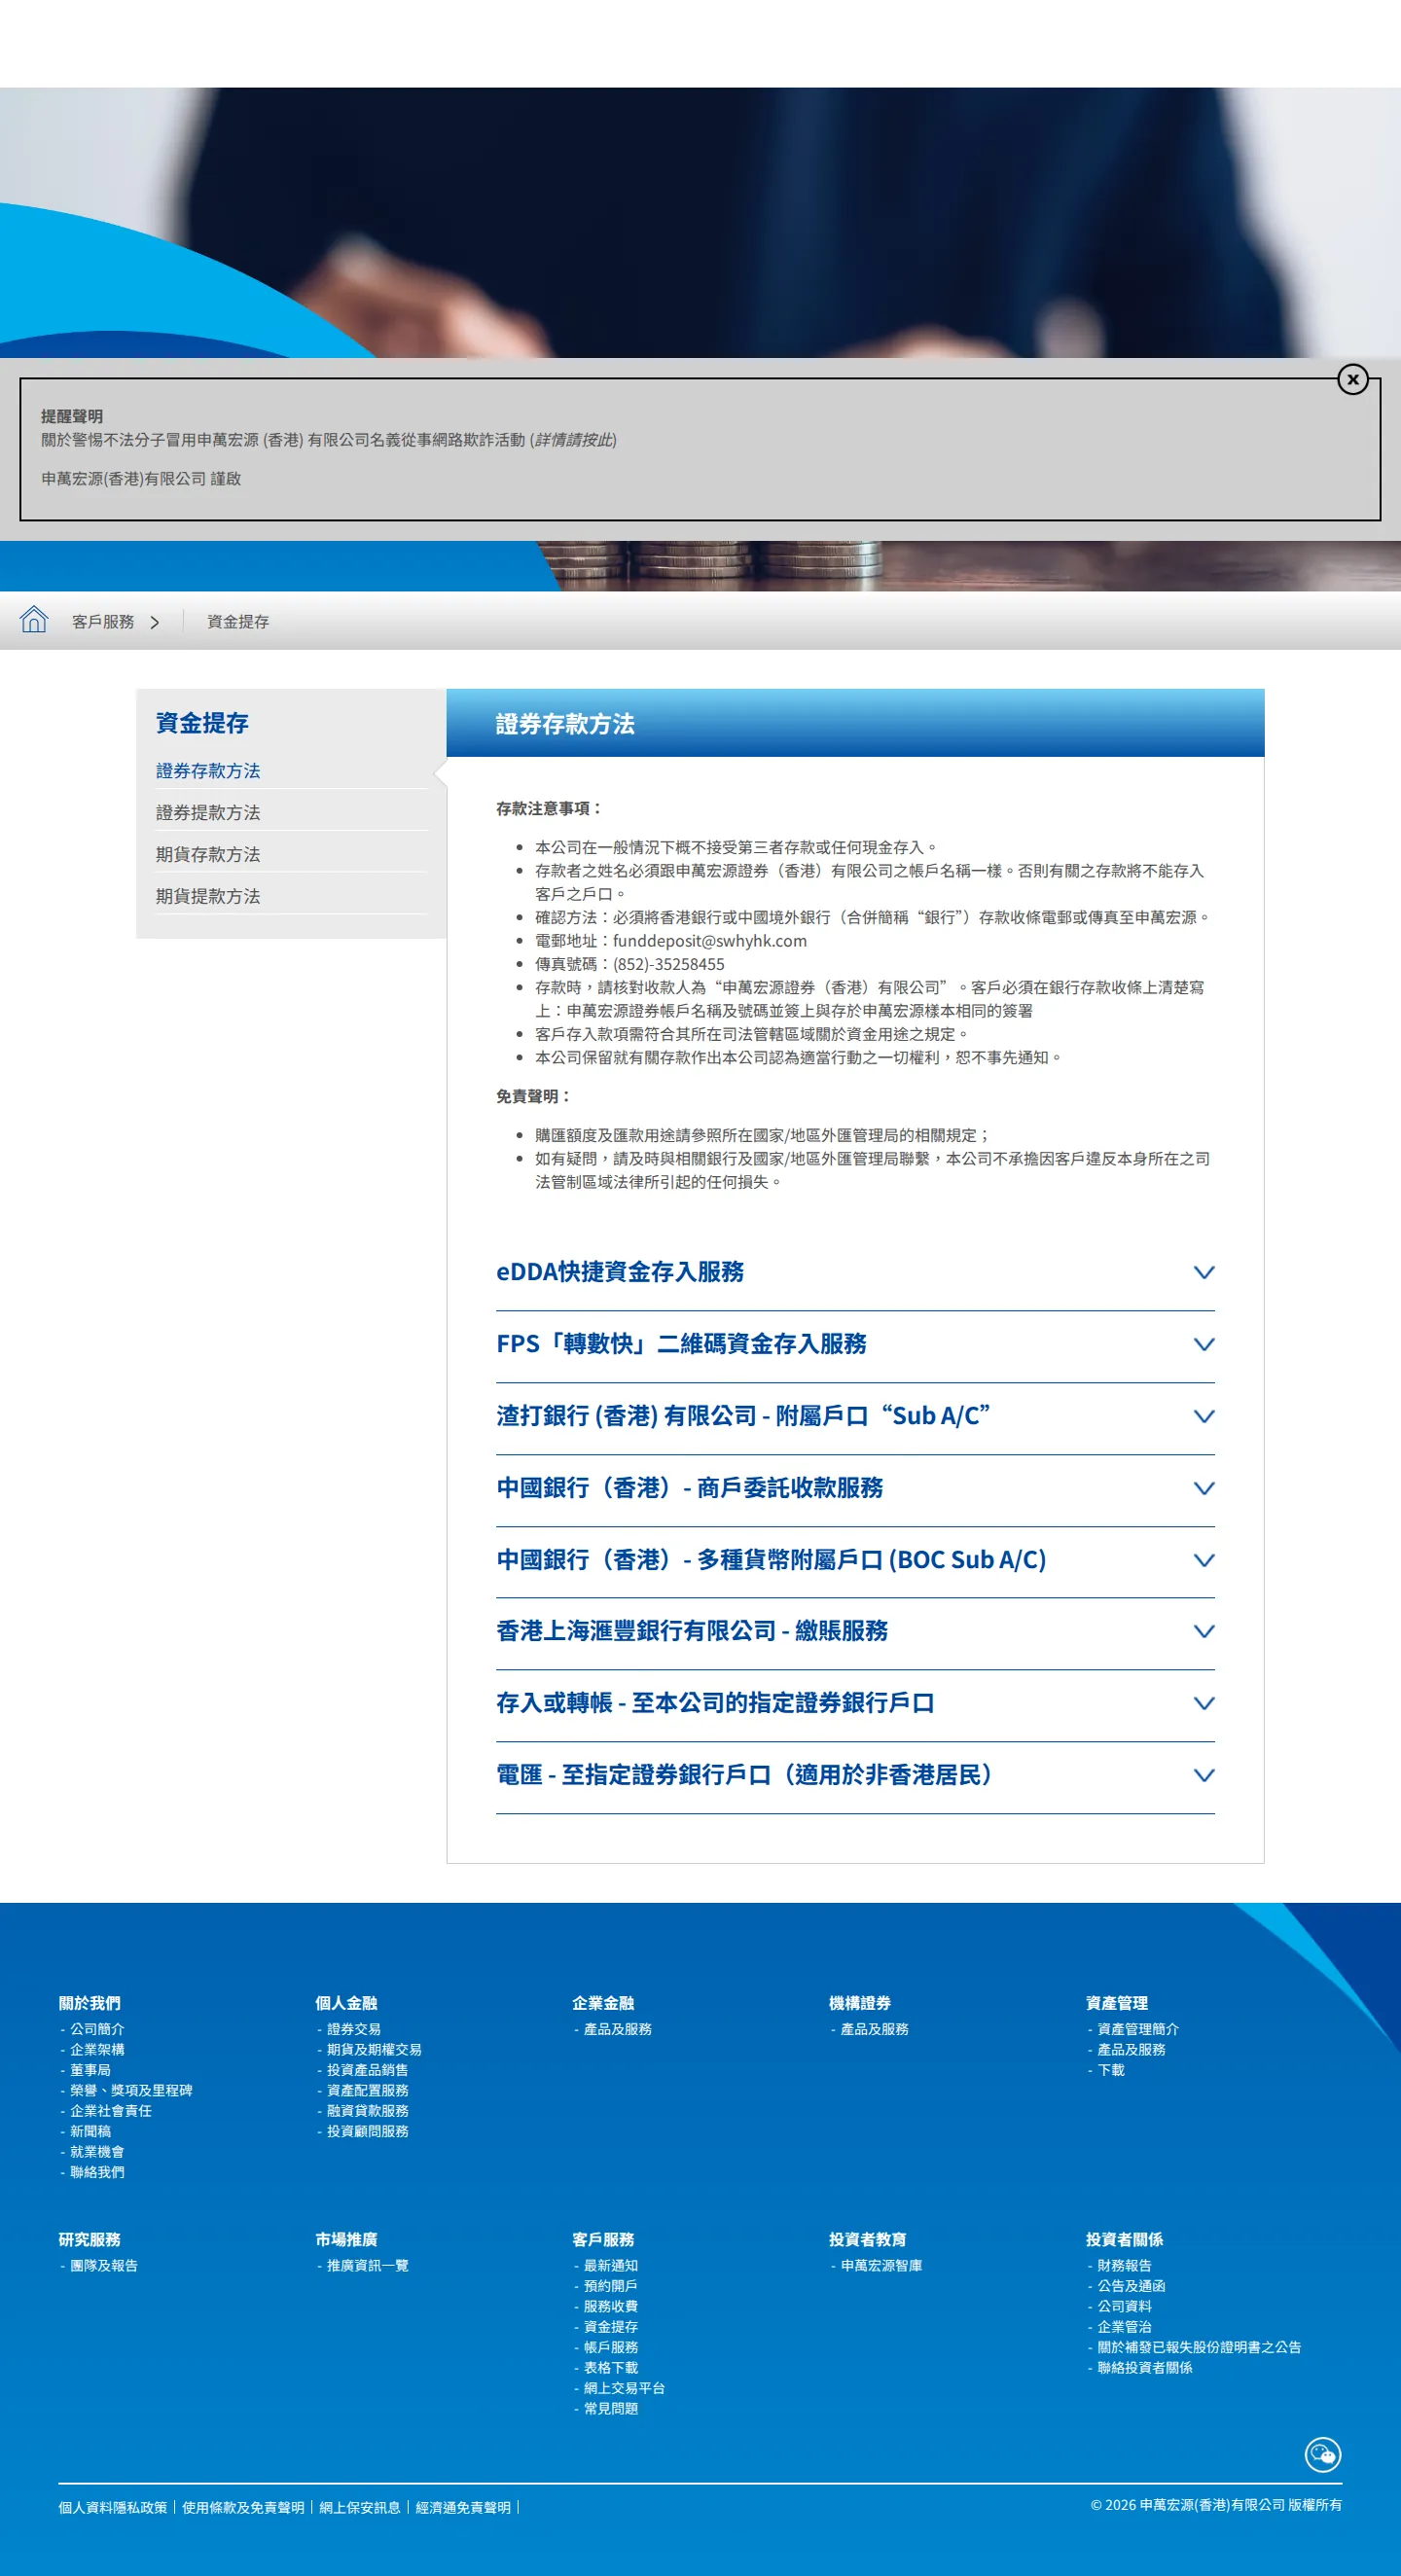
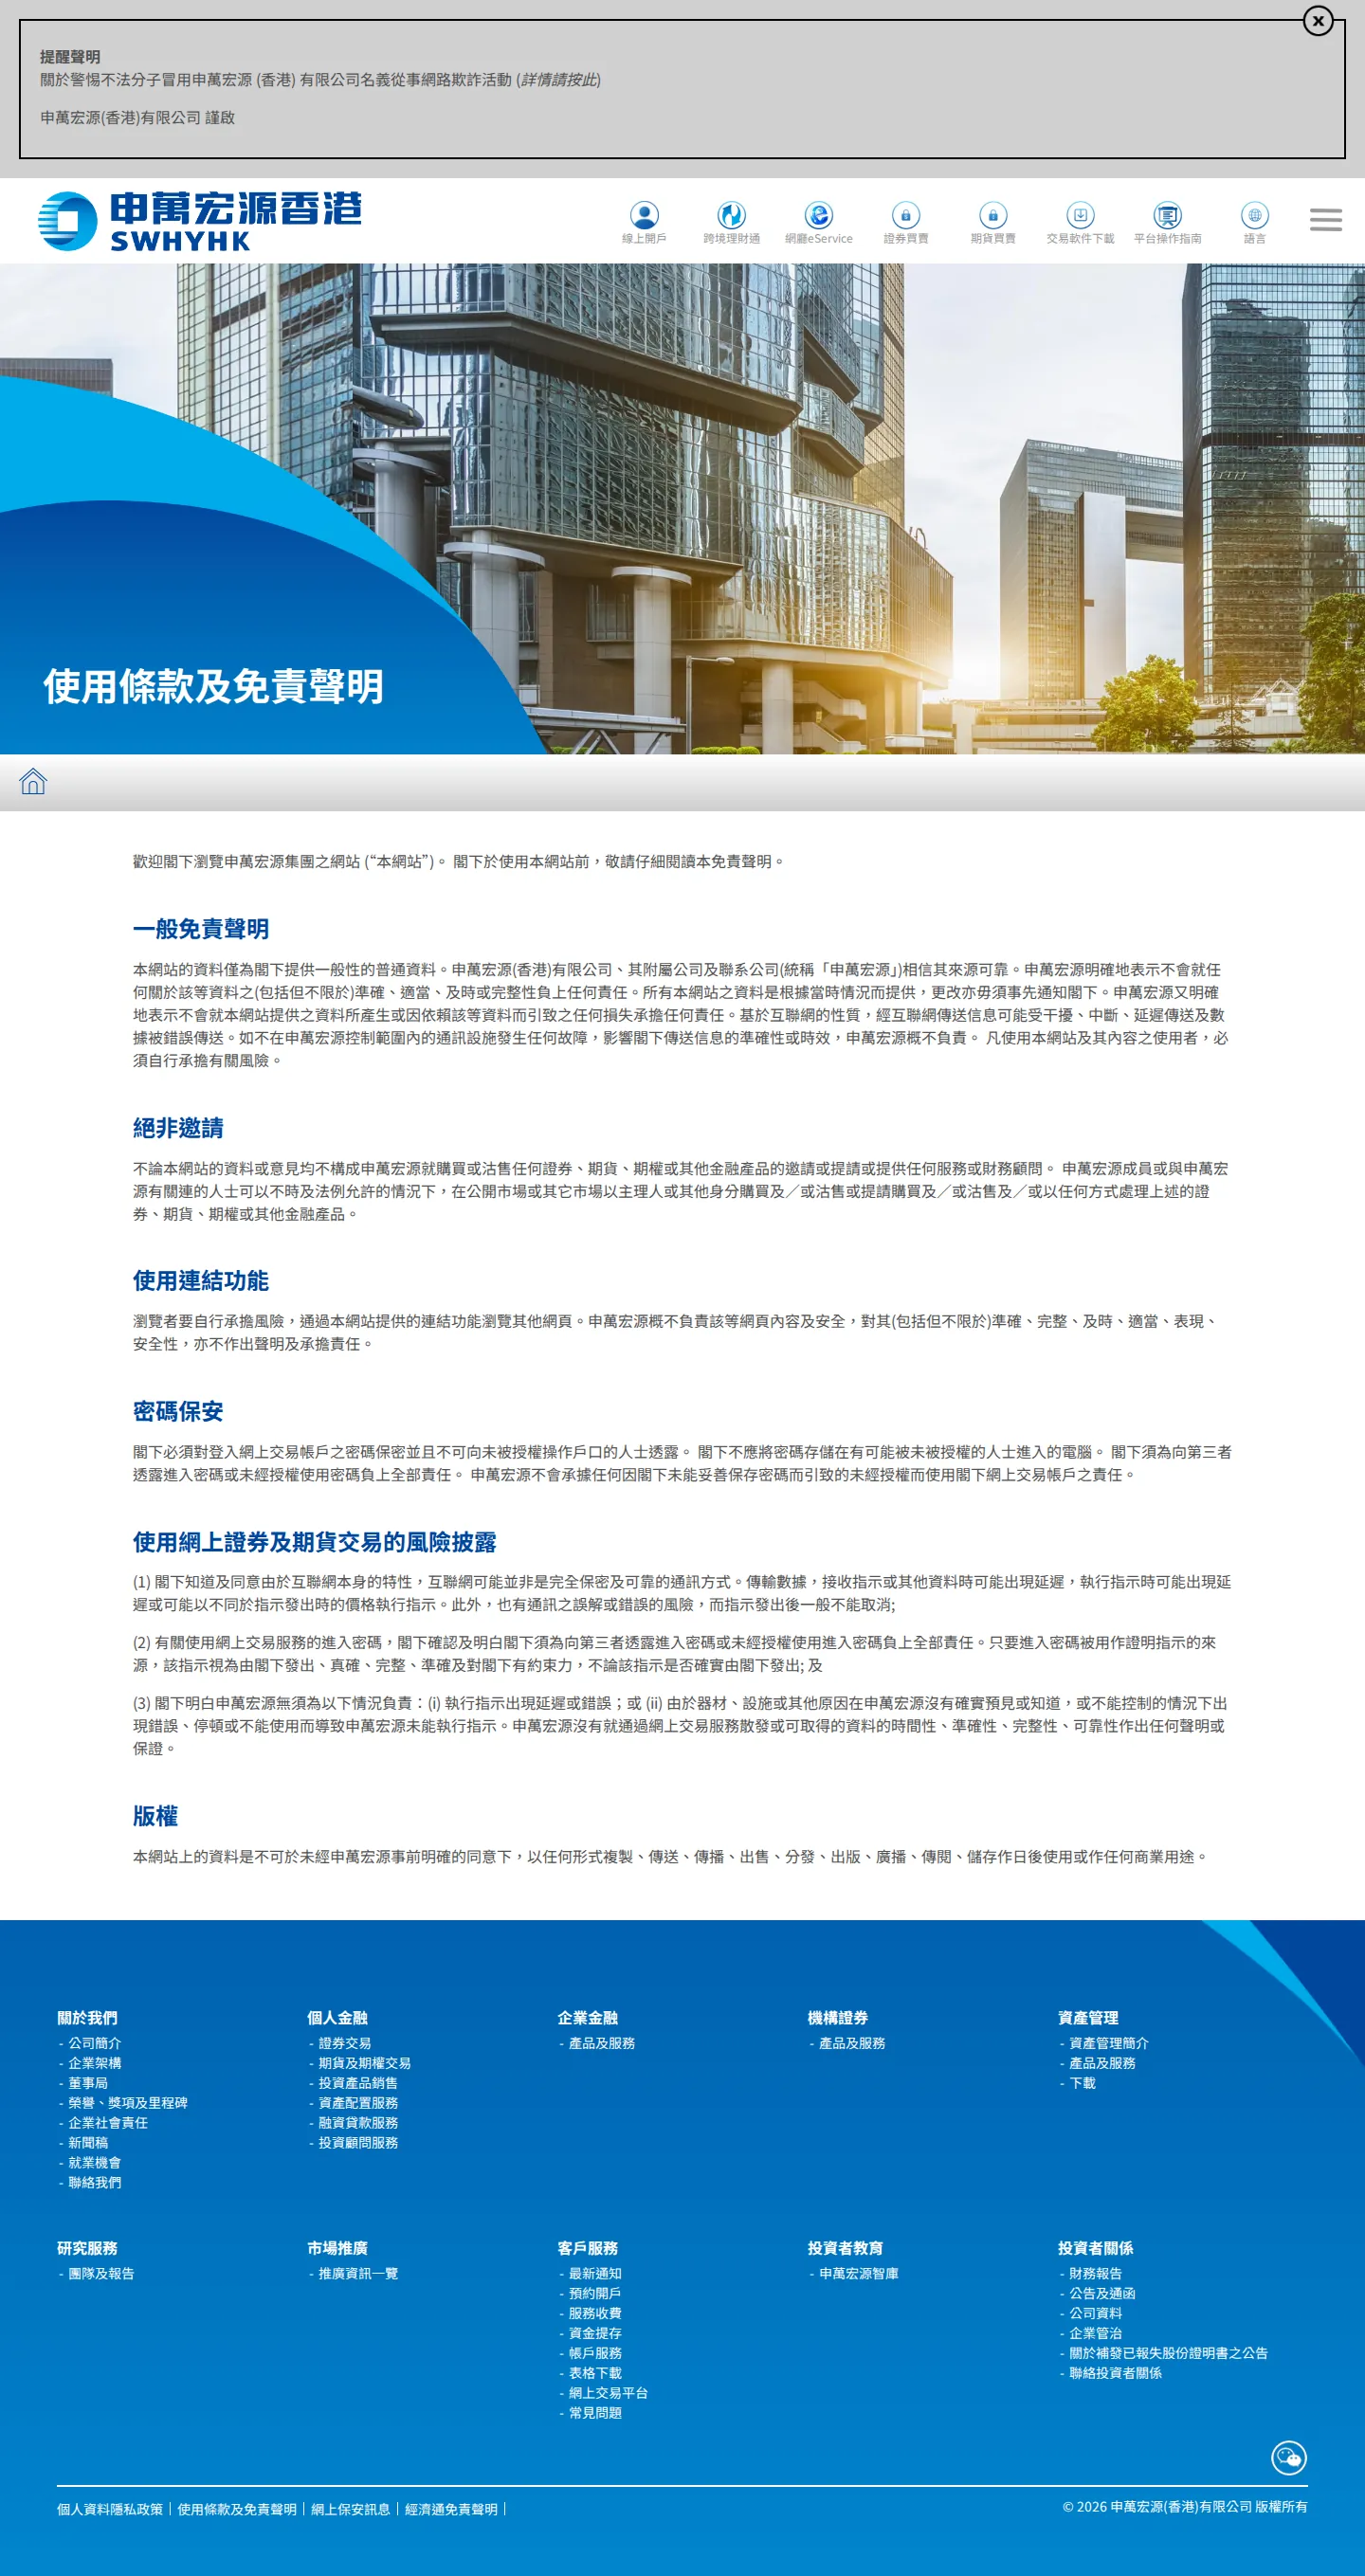
Pages captured from Shenwan Hongyuan’s own site when this review was written. Brokers change their terms; these are what we read.
Score history
Recomputed daily; every move is on the record. The current score is always the latest row.
| Date | Score | Move |
|---|---|---|
| 2026-09-29 | 5.5 | ▲ |
| 2026-07-25 | 4.0 | ▲ |
| 2026-07-18 | 3.8 | ▼ |
| 2026-07-11 | 4.0 | · |
FAQ
Is Shenwan Hongyuan regulated?
Yes. Its Hong Kong subsidiaries hold active SFC licences AAC927 (securities) and AAF420 (futures), with no disciplinary action recorded.
Has Shenwan Hongyuan ever faced regulatory action?
In 2020 the SFC issued a restriction notice freezing four client accounts during a market-manipulation probe; the firm itself was not accused.
What does Shenwan Hongyuan charge?
Some fees are published, but no EURUSD spread is available for any account a retail client can open.
What trading platforms does Shenwan Hongyuan offer?
Its own web platform, mobile app, and Windows and Mac clients, plus Wynner Voyage, Wynner Futures, 申易贏, 易星Intl and an eService web portal.
How can I contact Shenwan Hongyuan support?
By phone or email, staffed in the client’s own language with published hours, though the exact entity and escalation depend on who onboarded you.
Is client money protected if Shenwan Hongyuan fails?
Under the SFC’s compensation scheme, clients can claim up to 500,000 HKD, though the adjudicator charges the claimant to use it.
How this review works
Track Shenwan Hongyuan live: score moves and red notices, in your pocket.