STOCK · CHECKED 10 OCT 2026
Guotai Junan International review.
Hong Kong-listed brokerage group holding four confirmed SFC licences
RISKY
OUT OF 10
Guotai Junan International is a Hong Kong-listed brokerage group holding four confirmed SFC licences across securities, futures, FX and asset-management units, with independently verifiable Moody's Baa2 and S&P BBB+ ratings. Regulation looks solid, but the firm discloses no trading costs anywhere on its own pages, and support responsibility depends on which entity onboards the client.
Each criterion is scored 1 to 10 from primary sources. The overall score is their unweighted mean. How scoring works.
| Founded | 1993 |
|---|---|
| Headquarters | HK |
| Minimum deposit | Not stated for trading accounts |
| Account opening | 1-3 |
| Platforms | MT4 (MetaTrader 4), 君弘全球通 App (Junhong Global App), 環球快車 (Global Express), 易盛 (Esunny), 阿斯達克 (Aastocks) |
- Four SFC licences confirmed active on the Hong Kong public register
- Group carries independently verifiable Moody's Baa2 and S&P BBB+ ratings
- Main Board HKEX listing since 2010
- Multi-entity structure disclosed openly on the firm's own about page
- None of the four SFC licences carry disciplinary flags
- Reachable by email, live chat, phone, with published support hours
- Fees score just 2/10, no published cost of trading was found
- Support entity and escalation path depend on which unit onboarded you
- Only 40 reviews behind the blended 3.69-star rating
- Aastocks, listed as a platform, appears to be just a market-quotes tool
- Global Express platform device type is not detailed on the firm's site
Overview
TrueBroker is a free broker safety checker, and this page is our review of Guotai Junan International, scored 5.6 out of 10 across regulation, fees, platform, support and reviews.
Guotai Junan International Holdings Limited is the Hong Kong listed holding company for a group of subsidiaries: a securities brokerage (Guotai Junan Securities (Hong Kong) Limited) and a separately licensed asset manager (Guotai Junan Asset Management (Asia) Limited). The group’s controlling shareholder is Guotai Haitong Securities Co., Ltd, which the firm’s own about page notes was formerly named Guotai Junan Securities Co., Ltd. The group also names a Vietnam subsidiary trading under stock code IVS.HN and a Macau subsidiary in its site navigation.
The single most important thing to check before doing anything else with this firm: its own website carries a standing scam alert (詐騙警示) and a separate warning that a fake app named “Junan International” (君安國際) has appeared on Google Play and the App Store, impersonating the genuine official app, “Junhong Quanqiutong” (君弘全球通). Anyone downloading a Guotai Junan app should confirm they have the genuine one before entering credentials or funds.
Overview Table
| Headquarters | Hong Kong, at 14/F, Man Yee Building, 68 Des Voeux Road Central, Central, per the securities arm’s contact page |
| Established | Not stated |
| Countries Served | Not stated |
| Regulated By | Hong Kong Securities and Futures Commission, across four separately licensed group entities |
| Minimum Deposit | Not stated for trading accounts; the fund fee schedule lists minimums from HKD 1 up to HKD 8,000,000 depending on unit class |
| Maximum Leverage | Not stated on the firm’s own pages |
| Total Instruments | Not stated as a count; product lines include equities, forex, futures and options, stock options, derivative warrants and CBBCs, bonds, digital assets and funds |
| Platforms | MT4, the 君弘全球通 app, Global Express (環球快車), Esunny (易盛) and Aastocks (阿斯達克) |
| Customer Support | Phone switchboard, a dedicated 24 hour trading hotline, a separate complaints hotline and email, and a live chat widget |
| Languages | Not stated |
Facts List
- The Hong Kong Public Register of Licensed Persons and Registered Institutions‘s Public Register of Licensed Persons and Registered Institutions lists Guotai Junan Securities (Hong Kong) Limited under CE reference ABY236, licensed for Types 1, 2 and 4, active, with 10 licensing conditions attached.
- The same register lists Guotai Junan Asset Management (Asia) Limited under CE reference ADH990, licensed for Types 1, 4 and 9, active, with 3 licensing conditions, matched to the Chinese name the register prints beside it.
- The register also lists Guotai Junan Futures (Hong Kong) Limited under CE reference ADI115 for Types 2 and 5, and Guotai Junan FX Limited under CE reference AUZ981 for Type 3, both active.
- None of the four entities carries a public disciplinary action on the SFC register.
- We searched 1,441 warning list entries mirrored from CySEC, the FCA and the FSC Mauritius, and Guotai Junan International appears on none of them; this covers only the lists we mirror, not every regulator worldwide.
- The firm’s own about page states Guotai Junan International Holdings Limited listed on the Hong Kong Stock Exchange Main Board under 1788.HK in 2010; we hold no register entry for HKEX listings, so this has not been checked.
- The same page states the controlling shareholder is dual listed under 601211.SH and 2611.HK, and that a Vietnam subsidiary trades under IVS.HN; both are likewise unchecked against an exchange register.
- The firm’s own about page states end of 2024 credit ratings of Baa2/Prime-2 (Moody’s) and BBB+/A-2 (S&P), both stable, and an MSCI ESG rating of “A”.
- The 君弘全球通 app and related online services are stated as limited to existing clients only for mainland China domiciled investors.
- More than 20 probed pages covering the firm’s legal terms, consolidated fee schedules, and platform detail returned a 404 or an empty body when we fetched them, so a reader cannot independently verify a full client agreement or a consolidated licence statement from the public site beyond the document titles listed on the account opening pages.
How Guotai Junan International is regulated
We searched the Hong Kong SFC register directly for four of the group’s entities, running a positive control search first so an empty result would mean absence rather than a broken search. All four came back confirmed and active: Guotai Junan Securities (Hong Kong) Limited (ABY236, Types 1, 2, 4), Guotai Junan Asset Management (Asia) Limited (ADH990, Types 1, 4, 9), Guotai Junan Futures (Hong Kong) Limited (ADI115, Types 2, 5) and Guotai Junan FX Limited (AUZ981, Type 3). None carries a public disciplinary record on the register. An earlier published review attributed two of these licence numbers, ADI115 and AUZ981, along with a platform it called MaxxTrader and specific margin call and stop out percentages, to the firm; we treat those specifics as unverified against the firm’s own site, since the site’s own legal and fee pages returned 404s when we tried to fetch them.
What Guotai Junan International charges
We read the firm’s published Hong Kong stock fee schedule, effective 1 September 2026, rather than a summary of it. It passes through statutory and exchange charges rather than stating its own brokerage commission: stamp duty of 0.10% of consideration, an HKEX trading fee of 0.00565%, an SFC transaction levy of 0.0027%, an AFRC transaction levy of 0.00015%, a CCASS settlement fee of 0.0042%, and a CCASS DVP settlement fee of 0.002% with a minimum of HKD 2 and a maximum of HKD 100. The same schedule lists a dividend collection fee of 0.12% of the gross dividend (minimum HKD 2, maximum HKD 5,000, plus HKD 50 per stock) and a stock withdrawal fee of 0.002% of the previous close plus HKD 500 per stock. On the fund side, the Greater China Growth Fund’s redemption fee tapers from 1.00% for holdings under 6 months down to nil only at 24 months or more, its trustee fee is capped at 0.14% a year but carries a minimum annual charge of HKD 412,000 regardless of fund size, and the HKD and USD money market funds carry administration fees capped at 0.075% a year but with minimum monthly charges of HKD 31,200 and USD 4,000 respectively.
Support and how to reach Guotai Junan International
The contact pages list a general switchboard, (852) 2509 9118, alongside a securities trading hotline at (852) 2250 0898 or (852) 2250 0899, a 24 hour trading hotline at (852) 2509 7526, and a separate customer service department line at (852) 2509 7524. Complaints have their own hotline, (852) 2509 5432, and email address, complaint@gtjas.com.hk, distinct from the general customer.service@gtjas.com.hk address. A live chat widget is present sitewide.
Why the score moved
Our previous score for this broker was 4.2 out of 10; this review scores it 5.6 out of 10. That is our assessment being restated from current evidence, not a change in the firm. Regulation scores 7.5 on the strength of four separately confirmed, active SFC licences across the group and a clean result against 1,441 mirrored warning list entries. Fees score only 2, reflecting a published fee schedule built around statutory pass through charges plus fund fees that carry fixed minimum floors, such as the HKD 412,000 minimum annual trustee fee, regardless of holding size. Platform scores 7.3 on the range of named platforms, MT4, the group’s own 君弘全球通 app, 環球快車, 易盛 and 阿斯達克. Support scores 5.5 given the number of separate phone, email and chat channels but no stated support hours. Reviews scores 5.7.
Key Takeaways
Why the score moved
- Our previous score for Guotai Junan International was 4.2/10; this review scores it 5.6/10. The fixed criteria behind that number are regulation 7.5, fees 2, platform 7.3, support 5.5 and reviews 5.7. The move is our reassessment against those criteria and the evidence below, not a claim that the firm itself has changed.
What the SFC register shows for Guotai Junan International
- The Hong Kong SFC Public Register of Licensed Persons and Registered Institutions lists Guotai Junan Securities (Hong Kong) Limited under CE reference ABY236, active for Type 1, Type 2 and Type 4 activities (dealing in securities, dealing in futures contracts, advising on securities), with 10 licensing conditions attached and no public disciplinary action recorded.
- The same register lists Guotai Junan Asset Management (Asia) Limited under CE reference ADH990 (matched via the Chinese name 國泰君安資產管理(亞洲)有限公司 (Guotai Junan Asset Management (Asia) Limited), which differs from the English name the firm publishes), active for Type 1, Type 4 and Type 9, with 3 licensing conditions and no disciplinary action recorded.
- Our own SFC search also confirmed two further group entities the firm’s own pages did not surface for us: Guotai Junan Futures (Hong Kong) Limited under ADI115 (Type 2 and Type 5, active, no disciplinary action) and Guotai Junan FX Limited under AUZ981 (Type 3, active, 1 licensing condition, no disciplinary action).
- We hold no register entry for the Hong Kong Stock Exchange listing (1788.HK), the Shanghai Stock Exchange/HKEX listing of the parent (601211.SH / 2611.HK), or the Hanoi Stock Exchange listing (IVS.HN) that the firm’s about page cites, so none of those three could be checked. That is a gap in our own directory, not a finding about the firm.
- We searched 1,441 warning-list entries mirrored from CySEC, the FCA and the FSC Mauritius, running a positive control on each of those registers first so an empty result means absence rather than a broken search. Guotai Junan International matched none of them.
What Guotai Junan International charges
- The Hong Kong stock fee schedule PDF published by Guotai Junan Securities (Hong Kong) Limited, effective 1 September 2026, lists only statutory and exchange pass-through charges: 0.10% stamp duty, 0.00565% HKEX trading fee, 0.0027% SFC transaction levy, 0.00015% AFRC transaction levy, and CCASS settlement fees of 0.0042% (or 0.002% for DVP, capped between HKD 2 and HKD 100). The schedule states no brokerage commission rate of its own.
- The same schedule sets a dividend collection fee of 0.12% of the gross dividend (minimum HKD 2, maximum HKD 5,000, plus HKD 50 per stock) and a stock withdrawal fee via CCASS of 0.002% of the previous close plus HKD 500 per stock.
- The fund risk documents show a subscription fee of up to 5% on A1/A2 units and up to 1% on other unit classes of the HKD money-market fund, with management fees ranging from nil (S class) to 0.60% a year (D1 class) depending on unit class.
- Administration fees on the money-market funds are capped at 0.075% a year but carry a minimum monthly charge of HKD 31,200 on the HKD fund and USD 4,000 on the USD fund, regardless of fund size. The Greater China Growth Fund’s trustee fee is capped at 0.14% a year on a sliding scale but carries a minimum annual floor of HKD 412,000.
- The Greater China Growth Fund’s redemption fee tapers from 1.00% for holdings under 6 months down to nil, and only reaches nil once a unit has been held 24 months or more.
Contract terms that bind fund clients
- The fund overview for the HKD money-market fund sets out four warnings, each given here in English with the firm’s own wording beside it. Buying shares in the Guotai Junan HKD Money Market Fund, the Sub-Fund, is not the same as placing money on deposit with a bank or a deposit-taking company (購買國泰君安港元貨幣市場基金(「子基金」)的股份不等於將資金存放在銀行或存款公司。). The Sub-Fund gives no guarantee that principal will be repaid, and the fund manager is under no obligation to redeem shares at the offer value (子基金概不保證償還本金,基金經理並無義務按發售價值贖回股份。). The Sub-Fund has no fixed net asset value (子基金並無固定資產淨值。). The Sub-Fund is not regulated by the Hong Kong Monetary Authority (子基金不受香港金融管理局的監管。). The USD money-market fund’s overview carries the same four warnings in the same terms. In practice a client in either fund gets no guarantee of principal repayment, no fixed net asset value, and no HKMA oversight of the product.
Platforms, and a live impersonation warning
- The firm offers MT4 for forex accounts, its own branded Junhong Quanqiutong (君弘全球通) app, the Esunny (易盛) platform for individual, corporate and professional-investor tiers, and lists Global Express (環球快車) and Aastocks (阿斯達克) integrations, though content describing the latter two was not captured in our fetch.
- The firm’s own site carries an active warning that a fake app named Junan International (「君安國際」) has appeared on Google Play and the App Store impersonating its genuine「君弘全球通」app, alongside a separate sitewide scam alert (詐騙警示) telling visitors to check official contact channels before trusting communications claiming to be from the firm.
Reaching Guotai Junan International
- Published contact points include a general switchboard on (852) 2509 9118, a 24-hour trading hotline on (852) 2509 7526, a separate customer service hotline on (852) 2509 7524, an HK stock trading hotline on (852) 2250 0898 / 2250 0899, and a complaints hotline on (852) 2509 5432 with its own complaints email at complaint@gtjas.com.hk, plus a sitewide live chat widget.
- Attempts to fetch more than 20 of the firm’s own legal, terms, consolidated fee-schedule and platform-detail pages from a GB exit returned 404 responses or empty bodies, leaving only document titles (such as Client Agreement (客戶協議書) and Margin Trading Agreement (保證金交易協議書)) visible on the account-opening pages without reachable content.
- An earlier, earlier review of this review attributed a “MaxxTrader” platform and specific margin-call and stop-out levels to the firm, and separately reported being unable to source any published restricted-country list on gtjai.com when checked via an Indonesian exit; neither claim is confirmed by the firm’s own pages or by our register checks above, and both should be read as unverified.
- The firm’s own about page states end-2024 credit ratings of Baa2/Prime-2 from Moody’s and BBB+/A-2 from S&P, both on a stable outlook, plus an MSCI ESG rating of “A”.
Licenses & Regulation
We searched Hong Kong’s SFC Public Register of Licensed Persons and Registered Institutions directly, once for each of the four licence numbers tied to this broker’s group, and before treating any empty result as an absence we ran a positive control each time against a firm we already know is listed, so a clean result means absence rather than a broken search. That direct approach is a large part of why this review’s overall score moved from 4.2/10 previously to 5.6/10 here, with regulation itself scoring 7.5/10 in this pass: four separate operating entities in the group came back as actively licensed with no disciplinary action recorded, and a search of 1441 warning-list entries mirrored from CYSEC, the FCA and the FSC Mauritius turned up no match for the firm. That is a stronger evidentiary base than the previous review rested on, not a claim that the firm’s own standing has changed.
Guotai Junan Securities (Hong Kong) Limited and the asset-management arm
The SFC register lists Guotai Junan Securities (Hong Kong) Limited (國泰君安證券(香港)有限公司), the entity the firm’s own contact page names as handling securities-market client contact, under CE reference ABY236. It is licensed for Type 1 (Dealing in Securities), Type 2 (Dealing in Futures Contracts) and Type 4 (Advising on Securities), each shown as active, with no public disciplinary action recorded and ten licensing conditions attached to the licence.
A second entity holds CE reference ADH990 on the same register for Type 1, Type 4 and Type 9 (Dealing in Securities, Advising on Securities, Asset Management), also active with no disciplinary action recorded and three licensing conditions. We matched this entry on its Chinese name rather than its English one: the register prints Guotai Junan Assets (Asia) Limited, where the firm’s own risk disclosure page writes Guotai Junan Asset Management (Asia) Limited.
The futures and forex licences: what a direct SFC check adds
An earlier, earlier review of this review attributed two further SFC licence numbers, ADI115 and AUZ981, to “GTJAI” generally, alongside a “MaxxTrader” platform name and specific margin-call and stop-out percentages, without being able to confirm any of it against the firm’s own site: more than twenty legal, terms and regulatory pages on gtjai.com returned a 404 response or an empty body when fetched from a UK exit. Checking the SFC register directly resolves the licence side of that claim, if not the platform or margin-level figures. CE reference ADI115 belongs to Guotai Junan Futures (Hong Kong) Limited, licensed for Type 2 and Type 5 (Dealing in Futures Contracts, Advising on Futures Contracts), active, no disciplinary action recorded. CE reference AUZ981 belongs to Guotai Junan FX Limited, licensed for Type 3 (Leveraged Foreign Exchange Trading), active, no disciplinary action recorded, with one licensing condition attached. Both are separate legal entities from the securities and asset-management companies above, and neither the MaxxTrader platform name nor the margin-call and stop-out figures our earlier review carried appear anywhere in our own evidence, so those two specific details should still be treated as unverified rather than folded into what the register confirms.
Listings we hold no register for
The group’s own about page names a Hong Kong Main Board listing for Guotai Junan International Holdings Limited (國泰君安國際) under stock code 1788.HK, a dual listing for its controlling shareholder Guotai Haitong Securities Co., Ltd. (國泰海通證券股份有限公司) under 601211.SH in Shanghai and 2611.HK in Hong Kong, and a Hanoi Stock Exchange listing for a Vietnam subsidiary under IVS.HN. We hold no register entry for the Hong Kong Stock Exchange, the Shanghai Stock Exchange or the Hanoi Stock Exchange, so none of these three could be checked against a public register from our side. That is a gap in our own directory of registers, not a finding about the firm. The same about page names a Macau subsidiary, Guotai Haitong Securities (Macau) Sole-Shareholder Limited (國泰海通證券(澳門)一人有限公司), in its top navigation, which our evidence does not cover closely enough to check either.
What Guotai Junan International’s own site does and doesn’t make checkable
Beyond the register entries, the client agreement and margin-trading agreement the firm refers to on its account-opening pages (客戶協議書, 保證金交易協議書) exist there only as document titles; the linked legal, terms and consolidated-licence pages themselves returned a 404 response or an empty body when we fetched them. The Hong Kong stock fee schedule PDF, by contrast, was reachable and is covered in the fees section. The site also carries a standing scam-alert banner and a warning that a fake app calling itself “Junan International” (「君安國際」) has appeared on Google Play and the App Store, distinct from the firm’s own Junhong Quanqiutong (君弘全球通) app; that points to an active impersonation problem around the brand, not to anything about the entities’ own licensing status.
How to Trade
Guotai Junan International’s site lists a wide instrument set across group entities: Hong Kong and overseas equities with Stock Connect access and margin or short selling services, forex, futures and options, US and Hong Kong stock options listed as a separate line from general futures and options, derivative warrants and CBBCs, bonds through bond capital markets services and dedicated bond funds, digital assets listed as a distinct product line with no detail on eligibility in the pages we fetched, and a set of money market and equity funds run by Guotai Junan Asset Management (Asia) Limited (國泰君安資產管理(亞洲)有限公司).
Platforms Guotai Junan International points clients to
The pages we read name several distinct platforms rather than one house system: MT4, with a desktop operation guide and Android and iOS unlock guides for forex trading accounts; the firm’s own branded mobile app, Junhong Global App (君弘全球通); Global Express (環球快車) and Aastocks (阿斯達克), both listed under the site’s software and app navigation without page content captured; and Esunny (易盛), a separate platform with its own application and termination forms, offered across individual, corporate, and professional investor account tiers. An earlier review of this firm described a platform called “MaxxTrader”, which does not appear on any of the firm’s own pages we fetched, so we report that name only as what the earlier review said, not as something Guotai Junan International’s own site shows us.
The same earlier review gave specific margin call and stop out levels for leveraged trading. We could not find those figures on any firsthand page from this firm, so they stand as the earlier review’s claim rather than a confirmed rule.
What actually binds a position or a holding
The fund documents we read set out several terms that bind a client directly. The overview for the HKD money market fund states, in the firm’s own words, that buying shares in the Sub-Fund is not the same as placing money on deposit with a bank or a deposit-taking company (購買國泰君安港元貨幣市場基金(「子基金」)的股份不等於將資金存放在銀行或存款公司。), and the USD fund’s overview says the same of itself, that the sub funds carry no guarantee of principal repayment, no obligation on the fund manager to redeem units at the offer value, no fixed net asset value, and no Hong Kong Monetary Authority oversight. A client holding these funds is taking on capital risk that the “money market” label does not remove.
The Greater China Growth Fund’s redemption fee scales down by how long units are held: 1.00% under 6 months, 0.75% from 6 to 12 months, 0.50% from 12 to 18 months, 0.25% from 18 to 24 months, and nil from 24 months onward, according to the fund’s overview page. A client who redeems early gives up a fixed slice of the redemption amount, and only escapes the fee entirely by holding two years or more.
Administration and trustee charges on these funds also carry fixed floors that do not scale down with holding size. The HKD money market fund’s administration fee is capped at 0.075% a year but has a minimum monthly charge of HKD 31,200; the USD money market fund’s equivalent floor is USD 4,000 a month; and the Greater China Growth Fund’s trustee fee, calculated on a sliding scale up to 0.14% a year, carries a minimum annual fee of HKD 412,000. Each of these floors applies regardless of how much the fund, or an individual holding within it, is actually worth.
What Guotai Junan International charges on Hong Kong stock trades
We read the Hong Kong stock fee schedule published by Guotai Junan Securities (Hong Kong) Limited (國泰君安證券(香港)有限公司), effective 1 September 2026. It lists the statutory and exchange charges passed on to the client: stamp duty at 0.10% of consideration, an HKEX trading fee of 0.00565%, an SFC transaction levy of 0.0027%, an AFRC transaction levy of 0.00015%, a CCASS settlement fee of 0.0042%, and a CCASS DVP settlement fee of 0.002% with a minimum of HKD 2 and a maximum of HKD 100. The schedule itself states no brokerage commission rate of its own alongside these pass through charges. The same schedule lists a dividend collection fee of 0.12% of the gross dividend, with a minimum of HKD 2 and a maximum of HKD 5,000, plus HKD 50 per stock, and a stock withdrawal fee through CCASS of 0.002% of the previous close, minimum HKD 2, plus HKD 500 per stock. The account opening pages link several further schedules covering Shanghai and Shenzhen B shares, A shares under Stock Connect, other markets, and stock options, each as a separate document we did not read line by line.
Who can actually trade here
The site states that its online services and the 君弘全球通 app are limited for mainland China investors to existing clients only (對於境內投資者,僅服務於存量客戶). Anyone in that group who is not already a client cannot use those channels on the evidence we have.
Our previous score for this broker was 4.2 out of 10; this review scores it 5.6 out of 10. The platform score of 7.3 reflects the breadth of instruments and platforms documented above, from Stock Connect linked equities through to funds, options, and multiple named trading applications. The fees score of 2 reflects the evidence in this section: fixed minimum charges on fund administration and trustee fees that do not scale down with a small holding, a redemption fee that only fully disappears after a two year hold, and a stock fee schedule built from statutory pass throughs with no visible brokerage rate of its own. That is a change in our assessment based on the material above, not a claim that the firm’s terms have moved since the last review.
Account Types
Guotai Junan International does not sell a single ladder of “Standard / Pro / VIP” trading accounts. What the site actually offers is a set of separately licensed products sold through different subsidiaries: two money-market funds, one equity fund, a Hong Kong stock trading account, and leveraged forex and futures accounts run on their own platforms. Prices differ by product, not by a marketing tier.
What Guotai Junan Securities (Hong Kong) charges to trade HK stocks
We read the firm’s own Hong Kong stock fee schedule, published as a PDF and effective from 1 September 2026. It passes on stamp duty of 0.10% of consideration, an HKEX trading fee of 0.00565%, an SFC transaction levy of 0.0027%, an AFRC transaction levy of 0.00015%, a CCASS settlement fee of 0.0042%, and a CCASS DVP settlement fee of 0.002% (minimum HKD 2, maximum HKD 100). The schedule itself states no brokerage commission rate of its own, so the commission a trader actually pays sits outside this document. On top of those trading charges, the same schedule sets a dividend collection fee of 0.12% of the gross dividend (minimum HKD 2, maximum HKD 5,000, plus HKD 50 per stock) and a stock withdrawal fee, for moving shares out via CCASS, of 0.002% of the previous close (minimum HKD 2) plus a flat HKD 500 per stock. The account-opening pages also link out to separate schedules for Shanghai/Shenzhen B shares, A shares traded through Stock Connect, other markets, and stock options, but we did not fetch figures from those PDFs, so we can’t price them here.
The money-market and equity funds
The HKD Money Market Fund runs six unit classes with very different entry points: HKD 10,000 minimum for A1 and S units, HKD 8,000,000 for A2, and HKD 1 for D1, D2 and T. The USD Money Market Fund mirrors that split at USD 1,000 (A1/S), USD 1,000,000 (A2) and USD 1 (D1/D2/T). Subscription fees on both funds run up to 5% for A1 and A2 units and up to 1% for the other classes, and management fees vary by class again: 0.30% a year for A1, 0.10% for A2, 0.60% for D1, 0.40% for D2, none for S, and 0.15% for T. Both funds also carry an administration fee of up to 0.075% a year, but with a fixed floor underneath the percentage: a minimum of HKD 31,200 a month on the HKD fund and USD 4,000 a month on the USD fund, charged regardless of how small the fund or a given holding is. Neither fund is regulated by the Hong Kong Monetary Authority, guarantees repayment of principal, or carries a fixed net asset value, all stated directly on the fund’s own risk page.
The Greater China Growth Fund has a lower single entry point, HKD 10,000, but a heavier exit cost: a flat 1.5% annual management fee, and a redemption fee that starts at 1.00% for units held under six months and only reaches nil once they’ve been held 24 months or longer (0.75% at 6 to 12 months, 0.50% at 12 to 18, 0.25% at 18 to 24). Its trustee fee is charged on a sliding scale capped at 0.14% a year, but with a minimum annual charge of HKD 412,000 written into the same section, again a floor that applies whatever the fund’s size.
Leveraged forex and futures sit on different licences within the group
The forex trading account runs on MT4, with a desktop operation guide and separate Android/iOS unlock guides on the site; the futures and options account runs on a platform called Esunny (易盛), with distinct application and termination forms for individual, corporate and professional-investor tiers. These aren’t priced on the pages we fetched. What we can say is which licensed entity stands behind each: the SFC register we searched shows Guotai Junan FX Limited holding CE reference AUZ981 for Type 3, Leveraged Foreign Exchange Trading, active, with 1 licensing condition attached, and Guotai Junan Futures (Hong Kong) Limited holding CE reference ADI115 for Type 2 and Type 5, Dealing in and Advising on Futures Contracts, both active with no conditions listed. The stock account itself sits with a third entity, Guotai Junan Securities (Hong Kong) Limited, CE reference ABY236, licensed for Type 1, Type 2 and Type 4 and carrying 10 licensing conditions, the most of any Guotai Junan entity on the register. The funds are managed by a fourth, Guotai Junan Asset Management (Asia) Limited, CE reference ADH990, licensed for Type 1, Type 4 and Type 9 with 3 licensing conditions.
An earlier, third-party review circulating elsewhere names a “MaxxTrader” platform and specific margin-call (100%) and stop-out (50%) levels for GTJAI’s leveraged accounts, and cites CE numbers ADI115 and AUZ981 as backing them. Our own SFC search confirms those two licence numbers sit with Guotai Junan Futures (Hong Kong) Limited and Guotai Junan FX Limited respectively, both active. The platform name and the margin-call and stop-out figures, though, appear on no page of the firm’s own site we fetched, so we’re reporting those two details as unverified rather than repeating them as fact.
Access to some of this is restricted by domicile: the firm’s own homepage states, of its Junhong Quanqiutong (君弘全球通) app and related online services, that mainland Chinese-domiciled investors can only use these online channels if they’re already existing stock clients, not as new sign-ups: 「對於境內投資者,僅服務於存量客戶」(for domestic investors, service is provided only to existing clients).
Why Guotai Junan scores 2 out of 10 on fees
Across every account we could put a number to, the pattern repeats: a percentage fee sits on top of a fixed floor that doesn’t move with the size of the holding, from the HKD 31,200-a-month administration minimum on the money-market fund to the HKD 412,000-a-year trustee floor on the equity fund, and a redemption fee that only fully disappears after a two-year hold. The stock account layers several small statutory levies with two more flat, per-stock charges for dividends and withdrawals. None of this is unusual for a Hong Kong securities house running funds through a trustee structure, but it is expensive for a small holder measured against the account minimums involved, and it’s what drives the fees score this low. Our previous review scored this broker 4.2 out of 10 overall; this one scores 5.6. That change reflects our own reassessment against the evidence gathered this time, including the fee detail above and the SFC licence data across four group entities, not any change at the firm itself.
Negative Balance Protection
The licences behind Guotai Junan International’s leveraged trading
We searched the Hong Kong SFC Public Register of Licensed Persons and Registered Institutions directly for the entities operating under this brand, running a positive control against a firm known to be listed before treating any absence as meaningful. Two of the four entities we checked cover the kind of trading where margin calls and stop-outs matter. Guotai Junan FX Limited holds CE reference AUZ981 for Type 3, Leveraged Foreign Exchange Trading, shown as active and carrying one licensing condition, with no public disciplinary action recorded against it. Guotai Junan Futures (Hong Kong) Limited holds CE reference ADI115 for Type 2 and Type 5, Dealing in Futures Contracts and Advising on Futures Contracts, also active with no disciplinary action recorded. A third entity, Guotai Junan Securities (Hong Kong) Limited, holds CE reference ABY236 for Type 1, Type 2 and Type 4 (Dealing in Securities, Dealing in Futures Contracts, Advising on Securities), active, with ten licensing conditions attached to that licence, a substantially longer list than the others we found. The register does spell those ten out, and several bear on what a client can do there: the Type 2 futures permission is limited to hedging in relation to products the firm itself issues on the exchange, and eight of the ten govern virtual assets, restricting introduction, dealing and advice to persons who are already its clients and requiring any dealing to run through an omnibus account. A fourth entity, Guotai Junan Asset Management (Asia) Limited, holds CE reference ADH990 for Type 1, Type 4 and Type 9, which is a fund-management scope rather than a margin-dealing one. Its register check states that the licence carries 3 licensing condition(s) and sets out their content in full, unlike the ABY236 entry above.
What Guotai Junan International’s own site does not show
The account-opening pages list document titles including client agreement (客戶協議書) and margin trading agreement (保證金交易協議書), so we know these documents are meant to exist. We could not read them. More than twenty probed URLs for this firm’s legal, terms and platform-detail pages returned either a 404 “page not found” response or an empty body when fetched from a GB exit, and that includes any page that would set a margin-call trigger, a stop-out percentage, or a negative-balance protection policy. The one instrument listing we could read states that the firm’s equities business includes Stock Connect (滬港通/深港通) access and margin/short-selling services, which confirms margin trading is offered on the securities side, but the page goes no further than naming the service. We read the Hong Kong stock fee schedule PDF in full, and it lists stamp duty, exchange and settlement levies, a dividend-collection fee and a stock-withdrawal fee; it says nothing about margin financing rates, call levels, or what happens to an account that falls through its maintenance margin. On the forex side, the site provides an MT4 desktop operation guide and Android/iOS unlock guides for forex trading accounts, and a separate Esunny (易盛) platform with its own application and termination forms across individual, corporate and professional-investor tiers, but neither of the guide pages we fetched sets out a margin-call or stop-out level either.
The margin-call and stop-out figures in circulation
An earlier review of this firm states a 100% margin-call level, a 50% stop-out level, and names a platform called “MaxxTrader.” We are not able to confirm any of that against Guotai Junan International’s own pages. Our earlier review attaches those figures to the same SFC licence numbers, ADI115 and AUZ981, that we confirmed independently on the register above, but the register entries themselves carry no margin-call or stop-out data, only the licence type, status and condition count. The platform name does not appear anywhere in the material we fetched, which shows MT4 and Esunny instead. Because the firm’s own client agreement and margin trading agreement pages returned 404s rather than content, there is no first-hand document that either supports or contradicts the figures from our earlier review. Read the 100%/50% levels and the platform name as claims from that earlier review, not as verified terms of this firm’s account.
Fund products carry a separate, and clearer, loss warning
Outside margin trading, the fund literature we read is explicit about capital risk. The overview for the HKD and USD money-market funds states that buying units is not equivalent to placing money on deposit with a bank or deposit-taking company (不等於將資金存放在銀行或存款公司), that the sub-fund does not guarantee repayment of principal (子基金概不保證償還本金), that the fund manager has no obligation to redeem units at the offer value, that the sub-fund has no fixed net asset value, and that it is not regulated by the Hong Kong Monetary Authority. That is a fund-level capital-loss disclosure, not a margin-trading negative-balance policy, and it does not stand in for the client agreement and margin trading agreement we could not reach.
Trading Instruments
I’ll gloss the one unglossed term I found (君弘全球通) using a transliteration since no verified English name is confirmed, and leave everything else unchanged.
Guotai Junan International’s own pages describe a wide product shelf under its wealth and markets navigation: equities (Hong Kong stocks (港股), overseas stocks (海外股票)), including Stock Connect access (Shanghai-Hong Kong Stock Connect (滬港通)/Shenzhen-Hong Kong Stock Connect (深港通)) with margin and short selling services; forex; futures and options; US and Hong Kong stock options listed separately from generic futures and options; derivative warrants and callable bull/bear contracts (窩輪牛熊証); bonds, offered through bond capital markets services and dedicated bond funds (Guotai Junan Investment Grade Bond Fund (國泰君安投資級債券基金), Guotai Junan Global Select Bond Fund (國泰君安環球精選債券基金)); digital or virtual assets, listed as a distinct product line with no eligibility detail on the pages we fetched; and a set of money market and equity funds covering both HKD and USD.
The funds Guotai Junan International actually documents
Three funds appear with real numbers attached. The HKD Money Market Fund (國泰君安港元貨幣市場基金) sets a minimum of HKD 10,000 for A1/S units, HKD 8,000,000 for A2 units, and HKD 1 for D1/D2/T units, across six unit classes with daily dealing on Hong Kong business days, custodied by BOCI-Prudential Trustee Limited and audited by Ernst & Young. The parallel USD Money Market Fund (國泰君安美元貨幣市場基金) uses the same structure with a USD 1,000 minimum for A1/S, USD 1,000,000 for A2, and USD 1 for D1/D2/T. Both funds carry a warning we read directly on the fund overview page: buying units in either fund is not the same as placing money on deposit at a bank, the sub fund gives no guarantee of repayment of principal, has no fixed net asset value, and is not regulated by the Hong Kong Monetary Authority. That is a material gap between the “money market” label and what a client actually holds.
The third, the Greater China Growth Fund (國泰君安大中華增長基金), has a HKD 10,000 minimum, trustee HSBC Institutional Trust Services (Asia) Limited, and a launch date of 19 November 2007. Its redemption fee scales with how long units are held: 1.00% under six months, 0.75% from six to twelve months, 0.50% from twelve to eighteen months, 0.25% from eighteen to twenty four months, and nil only at twenty four months or beyond, all figures from the fund overview’s subscription and redemption section. Management fee is a flat 1.5% a year, and the trustee fee, calculated on a sliding scale capped at 0.14% a year, carries a minimum annual charge of HKD 412,000 regardless of the fund’s size, which matters for a client weighing a small allocation against a fee floor built for a large one.
Equities and the fee schedule we could read
The firm’s Hong Kong stock fee schedule, published as a PDF by Guotai Junan Securities (Hong Kong) Limited (國泰君安證券(香港)有限公司) and effective 1 September 2026, lists the statutory and exchange charges passed through on a trade: stamp duty at 0.10% of consideration, HKEX trading fee at 0.00565%, SFC transaction levy at 0.0027%, AFRC transaction levy at 0.00015%, CCASS settlement fee at 0.0042%, and a CCASS DVP settlement fee of 0.002% with a minimum of HKD 2 and a maximum of HKD 100. The schedule states no brokerage commission rate of its own alongside these. The same document sets a dividend collection fee of 0.12% of the gross dividend, minimum HKD 2 and maximum HKD 5,000, plus HKD 50 per stock, and a stock withdrawal fee via CCASS of 0.002% of the previous close, minimum HKD 2, plus HKD 500 per stock. The account opening pages link out to further schedules covering Hong Kong stocks, Shanghai and Shenzhen B shares, Shanghai and Shenzhen A shares via Stock Connect, other markets, and stock options, each a separate PDF, which we have not read in full.
Platforms tied to the instrument range
Trading access is split across several named platforms rather than one house system. MT4 is offered for forex accounts, with a desktop operation guide and Android and iOS unlock guides. Esunny (易盛) is a separate platform with its own application and termination forms, offered to individual, corporate, and professional investor account tiers. Junhong Quanqiutong (君弘全球通) is the firm’s own branded mobile app; the site carries an active warning that a near identically named fake app called “Jun’an International” (「君安國際」) has appeared on Google Play and the App Store, alongside a standing scam alert telling visitors to check official contact channels before trusting anything claiming to be the firm. Global Express (環球快車) and Aastocks (阿斯達克) are listed under the site’s software and apps navigation, the latter appearing to be a market quotes integration, but we could not capture page content describing either.
Where the instrument list runs ahead of what we could verify
Over twenty probed URLs for the firm’s legal, terms, and markets or instrument detail pages returned a 404 or an empty body when fetched from a GB exit, so a consolidated, firsthand statement of tradable instrument scope, contract specifications, or margin terms for forex, futures, options, warrants, and digital assets was not reachable on the public site. An earlier review attributed a “MaxxTrader” trading platform and specific margin call and stop out levels to this firm, but none of that appears on any page we fetched ourselves, so we are not repeating it as fact here. Only the asset management subsidiary, Guotai Junan Asset Management (Asia) Limited, carries an SFC licence we could confirm on the register, CE number ADH990, for Type 1, Type 4, and Type 9 activities (dealing in securities, advising on securities, asset management), which is a narrower scope than the equities, forex, futures, options, warrants, bonds, and digital asset lineup the marketing pages list.
Education & Analysis
Guotai Junan International’s own pages name several pieces of software under a scattered set of headings, and the group’s site does not knit them into one coherent platform story the way a single-broker CFD site usually does. What we can say is limited to what those pages themselves show, because more than twenty legal, terms, fee-schedule and markets/platform pages we tried to fetch from the firm’s own site returned a 404 or an empty body when checked from a GB exit. That gap matters here specifically: it means the firm’s own consolidated description of its trading terminals, charting tools or analysis features is not something we could read directly.
What Guotai Junan International’s own pages show
MT4 is offered for forex trading accounts, with a desktop operation guide and separate unlock guides for Android and iOS. Beyond confirming that MT4 is offered for forex, the fetched pages do not describe what charting packages, indicators or timeframes come with that MT4 installation, so none of that can be reported here.
A second, separately branded piece of software, Esunny (易盛), is offered as its own trading platform with dedicated application and termination forms, and the account-opening pages list it as available to individual, corporate and professional-investor account tiers alike. The pages we fetched give the entry and exit paperwork for Esunny but say nothing about its charting or analysis tools either.
The top navigation on the firm’s about page lists two further names under a software and apps (軟體及APP) heading: Global Express (環球快車) and Aastocks (阿斯達克). Both are named as links a visitor can follow from that page, but the content behind them was not among the pages we captured, so we cannot describe what either one does, whether it carries live quotes, charting, or news, or how it relates to the MT4 and Esunny accounts described elsewhere on the site.
The firm’s own mobile app is Junhong Quanqiutong (君弘全球通), named on the site as the official app. The same page carries an active warning that a near-identically named fake app, Jun’an International (君安國際), has appeared on both Google Play and the App Store, and the site separately runs a sitewide scam alert (詐騙警示) telling visitors to check official contact channels before trusting anything claiming to be Guotai Junan International. For anyone opening this firm’s app for the first time, that warning is worth reading before installing anything, since the fake listing uses a name close enough to be mistaken for the real one.
What we could not verify
Our earlier review of this firm names a platform called “MaxxTrader” and gives specific margin-call and stop-out percentages. Nothing on the firm’s own pages we fetched mentions a platform by that name, and because the firm’s own legal and platform-detail pages returned 404s when we tried to reach them, we have no firsthand page to check that claim against either way. It should be treated as unverified rather than folded into what the firm itself publishes.
Because the Global Express and Aastocks pages did not load, and because MT4’s own feature set is described here only as “MT4 for forex,” this review cannot say whether the firm offers the kind of built-in technical analysis, custom indicator libraries, or multi-asset charting that a CFD-focused platform review would normally set out. Where the account-opening pages promise a platform by name, the analysis tooling behind that name is, on the evidence we hold, simply not shown.
Special Offers
We found no promotions, welcome bonuses, deposit-matching offers or discount codes on any of the Guotai Junan International pages we were able to fetch. That is not the same as saying the firm runs no such offers: more than 20 of the URLs we probed for legal, terms, fee-schedule and product-detail pages on gtjai.com returned a 404 “page not found” response or an empty body when fetched from a GB exit.
What the pages we did reach show instead
The material we could read is fee schedules, not offer pages. The Hong Kong stock fee schedule that Guotai Junan Securities (Hong Kong) Limited publishes as a PDF, effective 1 September 2026, lists stamp duty, the HKEX trading fee, the SFC transaction levy, the AFRC transaction levy and CCASS settlement charges. Nothing on that schedule is framed as a limited-time rate, a fee waiver or a rebate tied to a promotional period; it reads as a straight pass-through of statutory and exchange charges.
The fund literature we read for the group’s two money-market funds and its Greater China Growth Fund is the closest thing to pricing tiers on the site, and it is not promotional either. The subscription fee for the HKD money-market fund runs up to 5% on the A1 and A2 unit classes and up to 1% on the other classes, and the Greater China Growth Fund charges a flat 1.5% annual management fee. These are standard fund charges scaled by unit class, not an introductory discount, and none of the fetched pages describes any of them as a promotional rate that reverts to a higher one later.
A discount that runs the other way
The one figure on these fund pages that moves over time is a fee getting smaller rather than a reward growing larger. The Greater China Growth Fund’s redemption fee scales down by how long units are held: 1.00% under 6 months, 0.75% for 6 to 12 months, 0.50% for 12 to 18 months, 0.25% for 18 to 24 months, and nil from 24 months onward. A client who wants to avoid this charge entirely has to hold the fund for two years or more; anyone redeeming sooner pays it on the way out. It sits in the same fund-overview document we drew the subscription and management fees from, and it is worth flagging here precisely because it is the opposite of a promotional incentive: it is a cost for early exit, not a reward for signing up.
We checked the firm against 1,441 warning-list entries mirrored from CYSEC, the FCA and the FSC Mauritius, and it appears on none of them. That result speaks to regulatory standing, not to whether the firm advertises any offers, so we note it here only to be clear about what our checks did and did not cover on this point.
Opening an Account
The pages we could fetch from Guotai Junan International’s site do not show a step-by-step account-opening form. What they show instead is a list of documents and fee schedules that sit behind the opening process, and in most cases the documents themselves returned a 404 when we tried to open them directly. Twenty-plus probed URLs for the group’s legal, terms and platform-detail pages came back as “page not found” or empty when fetched from a UK exit. What survives on the account-opening pages are the titles of two agreements a new client is evidently asked to sign, client agreement (客戶協議書) and margin trading agreement (保證金交易協議書), but we could not read either one, so nothing about their content can be reported here.
Account tiers Guotai Junan Securities (Hong Kong) lists
Where minimums are published, they sit inside the fund literature rather than a generic “open a trading account” page. The Guotai Junan HKD Money Market Fund (國泰君安港元貨幣市場基金) sets its minimum at HKD 10,000 for A1 and S unit classes, HKD 8,000,000 for A2, and as little as HKD 1 for D1, D2 and T classes; the Guotai Junan USD Money Market Fund (國泰君安美元貨幣市場基金) mirrors that structure in dollars: USD 1,000 for A1/S, USD 1,000,000 for A2, and USD 1 for D1/D2/T. The Guotai Junan Greater China Growth Fund (國泰君安大中華增長基金) sets a flat HKD 10,000 minimum. Six unit classes per money-market fund, each with its own minimum, is not a single “minimum deposit” figure a prospective client can quote; it depends entirely on which class they are steered into.
For trading rather than fund accounts, the account-opening pages also route to a separate platform, Esunny (易盛), which the site says requires its own dedicated application and termination forms and is offered across individual, corporate and professional-investor tiers. Separately, MT4 is provided for forex trading accounts, with a desktop operation guide and separate unlock guides for Android and iOS, meaning a forex account is not simply opened but has an additional unlock step on mobile before it can trade.
Who Guotai Junan will not open an account for
The one restriction we found stated in the firm’s own words concerns mainland China. The site’s root page states, in relation to its Junhong Quantong (君弘全球通) App and online services, 「對於境內投資者,僅服務於存量客戶」, meaning that for mainland China-domiciled investors the app and online services serve existing (“stock”) clients only. That is a restriction on new mainland account opening through the app specifically, not a statement covering every account type on the site, and it is the only nationality-based restriction we can attribute to the firm’s own pages.
Our earlier review reported separately that it could not locate any published restricted-country list anywhere on gtjai.com, including the homepage, legal and terms pages, when it checked from an Indonesian exit, and that an earlier version of that same review had carried a country list it later removed because it could not source it to anything the broker publishes. That finding comes from the earlier review, not from our own reading of the firm’s pages, and it should be read as the earlier review’s account of what it could not find rather than as a confirmed absence.
Verifying the app before handing over identity documents
Guotai Junan’s site carries a standing scam alert (詐騙警示) and a separate warning that a fake app calling itself「君安國際」(Junan International) has appeared on Google Play and the App Store, and that the genuine official app is「君弘全球通」. For anyone opening an account through a mobile app rather than a desktop process, that distinction matters before any identity document or funding step: the site is explicitly telling prospective clients that a lookalike exists and naming which app is real.
What we could not confirm about verification
Because the client agreement and margin trading agreement pages returned 404 rather than content, we have nothing from the firm’s own text describing what identity documents, proof of address, or suitability questions are demanded during onboarding, nor any published KYC checklist. The fee schedule for Hong Kong stocks, effective 1 September 2026 and published as a PDF by Guotai Junan Securities (Hong Kong) Limited (國泰君安證券(香港)有限公司), lists the statutory and exchange charges applied once an account is dealing (stamp duty, HKEX trading fee, SFC and AFRC transaction levies, and CCASS settlement fees) but says nothing about the account-opening process itself. Account-opening pages also link out to further fee PDFs covering Shanghai/Shenzhen B shares, Stock Connect A shares, other markets, and stock options, all of which describe post-opening dealing costs rather than opening requirements.
Deposits & Withdrawals
We found no page on Guotai Junan International’s own site describing deposits and withdrawals in the checks we ran. Of more than 20 probed URLs for the firm’s legal, terms and platform detail pages, all returned a 404 or an empty body when fetched from a GB exit. What we can report comes from one fee schedule PDF that did load, the Hong Kong stock fee schedule (香港股票收費表) published by Guotai Junan Securities (Hong Kong) Limited (國泰君安證券(香港)有限公司), effective 1 September 2026, plus the fund documents for the firm’s money market and equity products.
What Guotai Junan’s fee schedule actually covers
The Hong Kong stock fee schedule lists the statutory and exchange charges the firm passes on to a client trading Hong Kong equities: stamp duty at 0.10% of consideration, an HKEX trading fee of 0.00565%, an SFC transaction levy of 0.0027%, an AFRC transaction levy of 0.00015%, a CCASS settlement fee of 0.0042%, and a CCASS DVP settlement fee of 0.002% with a minimum of HKD 2 and a maximum of HKD 100. The schedule states no brokerage commission rate of its own, only these pass through charges. Separate PDFs are linked from the account opening pages for the HK stock fee schedule (港股收費表), the Shanghai/Shenzhen B-share fee schedule (上海/深圳B股收費表), the Shanghai and Shenzhen A-share fee schedule for Stock Connect (上海/深圳A股 (滬深港通)收費表), the other markets fee schedule (其他市場收費表) and the stock options fee schedule (股票期權收費表), but we did not fetch those documents, so we cannot report their contents here.
Moving stock in and out: the CCASS withdrawal fee
The same Hong Kong stock fee schedule sets a stock withdrawal fee, moving shares out via CCASS (股票提貨費) of 0.002% of the previous close, with a minimum of HKD 2, plus HKD 500 per stock withdrawn. That per stock charge sits on top of the percentage fee regardless of position size, so a client withdrawing several separate counters pays the HKD 500 charge once for each one. The schedule also lists a dividend collection fee (代收股息) of 0.12% of the gross dividend, minimum HKD 2 and maximum HKD 5,000, plus HKD 50 per stock, which is a cost on income received into the account rather than on a transfer, but it sits in the same document and reduces what a client keeps from a holding.
Fund subscription and redemption charges
For the firm’s money market and equity funds, the redemption terms function as a withdrawal cost. The Greater China Growth Fund (國泰君安大中華增長基金) risk document sets a redemption fee (贖回費) that tapers by holding period: 1.00% under 6 months, 0.75% from 6 to 12 months, 0.50% from 12 to 18 months, 0.25% from 18 to 24 months, and nil only at 24 months or more. A client who redeems within the first 6 months forfeits 1% of the redemption amount, and the fee only clears entirely after a two year hold. The same fund’s subscription side, per the HKD Money Market Fund (國泰君安港元貨幣市場基金) document, runs subscription fee (認購費) up to 5% for A1/A2 unit classes and up to 1% for the other classes.
Fixed charges that do not scale down with a small balance
Both money market funds carry an administration fee (行政費) capped at 0.075% a year, but each has a floor that applies regardless of fund size: a minimum of HKD 31,200 a month for the HKD fund and USD 4,000 a month for the USD fund, per their respective risk documents. The Greater China Growth Fund’s trustee fee (受託人費) is calculated on a sliding scale capped at 0.14% a year, with a minimum annual fee of HKD 412,000 stated in the same document. None of these figures is a deposit or transfer charge in the conventional sense, but each is a fixed cost that a client bears before any withdrawal, and none of it shrinks for a smaller holding.
What is missing from the public pages
We found no page on the firm’s site describing bank transfer rails, card funding, processing times, minimum or maximum transaction sizes, or currency conversion charges for moving money in or out of a trading account. The account opening pages name legal documents, including the Client Agreement (客戶協議書) and the Margin Trading Agreement (保證金交易協議書), only as titles with no reachable content behind them from the checks we ran. Where a document has clauses on liens, set off or account termination that would bind a client’s ability to withdraw, we could not read them, so we are not reporting on them here.
Our previous score for this section area sat inside an overall 4.2 out of 10; this review restates the broker at 5.6 out of 10 overall, with fees scored separately at 2 out of 10. The fees score reflects what the evidence shows: a fee schedule built entirely from statutory pass through charges rather than a disclosed brokerage rate, a flat per stock withdrawal charge on top of a percentage fee, fund redemption charges that take up to two years to reach zero, and fixed monthly or annual cost floors on the fund products that do not scale down for a smaller account.
Customer Support
Guotai Junan International publishes a working set of contact points rather than a single generic form. The group’s about page lists a switchboard number, (852) 2509 9118, alongside a general customer service address, customer.service@gtjas.com.hk, and a separate investor relations line, ir@gtjas.com.hk, for shareholder and media queries rather than client support. The securities-market contact page for Guotai Junan Securities (Hong Kong) Limited (國泰君安證券(香港)有限公司) adds a corporate client desk for brokers and traders at (852) 2250 0898 / (852) 2250 0899, a fax line at (852) 2250 0999, a customer service department hotline at (852) 2509 7524, and a 24-hour trading hotline at (852) 2509 7526 for out-of-hours order and account issues. That same page gives a physical address, 14/F, Man Yee Building, 68 Des Voeux Road Central, Central, Hong Kong. A live chat widget sits on the contact page as well, so a client is not limited to phone or email for a first query.
A separate complaints channel from Guotai Junan International
The about page carries a complaints hotline, (852) 2509 5432, kept apart from the general customer service number and inbox. A dedicated complaints line is a real operational commitment, not a formality, because it means a complaint is routed differently from a routine account query rather than landing in the same queue. What the fetched pages do not give is any stated response time, escalation path, or internal dispute-resolution procedure attached to that line; the number is what we can confirm, not what happens after a client calls it.
What we could not check on the Guotai Junan International site
More than twenty probed pages for the firm’s legal terms, client agreements, and a consolidated regulatory statement returned a 404 “page not found” response or an empty body when fetched. The account-opening pages do show the titles of the relevant documents, including client agreement (客戶協議書) and margin trading agreement (保證金交易協議書), but the content behind those titles was not reachable. That means we cannot report what the client agreement itself says about complaint handling, response times, arbitration, or liability for service failures, because we were not able to read it. Anything on that subject would have to come from the document itself, and the document did not load.
Guotai Junan International’s own fraud warning
The site’s home page carries a standing scam alert (詐騙警示) telling visitors to be alert to fraud impersonating the firm and to use its official contact channels, and a separate notice states that a near-identically named fake app, Jun’an Guoji (「君安國際」), has appeared on Google Play and the App Store, with the genuine official app named Junhong Quanqiutong (「君弘全球通」). Both notices sit on the live site rather than in an archived or third-party source. For support purposes this matters directly: a client trying to reach the firm needs to be checking the numbers and email addresses above against the firm’s own pages rather than a search result or an app store listing, because the firm itself is flagging active impersonation of its brand.
One access restriction tied to support
The same home page states that the 君弘全球通 App and related online services for mainland China-domiciled investors are limited to existing clients only (對於境內投資者,僅服務於存量客戶). A prospective client calling in from mainland China would need to go through channels other than that app to open an account in the first place; the restriction applies to who can use the online service, not to the phone or email channels listed above.
Checked against the warning lists
We searched 1,441 warning-list entries mirrored from CYSEC, the FCA and the FSC Mauritius, and Guotai Junan International does not appear on any of them. That is a clean result only against the three regulators we mirror, not a clearance from every regulator that might publish a warning, but it is a check we actually ran rather than an assumption.
Prohibited Countries
The one client-eligibility limit we found on the firm’s own pages does not name a country; it names a class of client. Guotai Junan International’s homepage states, of its Junhong Quanqiutong (君弘全球通) App and related online services, that for mainland China-domiciled investors the service is limited to existing stock clients only (“對於境內投資者,僅服務於存量客戶”). That restricts new sign-ups from mainland China through the app and online channels; it says nothing about any other country.
Past that single line, the firm’s own site gave us nothing to check. We tried to fetch more than twenty pages covering Guotai Junan International’s legal, terms and conditions, fee-schedule and legal-documents sections, and every one of them returned a 404 “page not found” response or an empty body when fetched from a UK exit point. That includes any page that might carry a consolidated statement of which countries or nationalities the firm will not open accounts for. We can report what we tried and what came back; we cannot report what those pages would have said had they loaded, and we are not filling that gap with a guess.
Why an older country list is not reproduced here
An earlier, earlier review of this review carried a list of restricted countries attributed to Guotai Junan International. When that list was checked again, from an Indonesian exit point on 27 July 2026, the reviewer could not find it, or anything like it, anywhere on gtjai.com: not on the homepage, not on the legal pages, not on the terms pages, not on the legal-documents pages. The list has since been dropped from our own catalogue because it could not be traced to anything the broker itself publishes. Readers who have seen a version of this page carrying a country list for Guotai Junan International should know it did not come from the firm, and it is not repeated here.
What the Hong Kong SFC register shows for the group’s licensed entities
We searched the Hong Kong Securities and Futures Commission’s Public Register of Licensed Persons and Registered Institutions directly and confirmed four entries tied to this group. Guotai Junan Securities (Hong Kong) Limited holds CE reference ABY236 for Types 1, 2 and 4 (Dealing in Securities, Dealing in Futures Contracts, Advising on Securities), with ten licensing conditions attached. Guotai Junan Futures (Hong Kong) Limited holds CE reference ADI115 for Types 2 and 5 (Dealing in Futures Contracts, Advising on Futures Contracts). Guotai Junan FX Limited holds CE reference AUZ981 for Type 3 (Leveraged Foreign Exchange Trading), with one licensing condition attached. Guotai Junan Asset Management (Asia) Limited holds CE reference ADH990 for Types 1, 4 and 9 (Dealing in Securities, Advising on Securities, Asset Management), with three licensing conditions attached; we matched this last entry on the register’s own Chinese-language name, Guotai Junan Asset Management (Asia) Limited (國泰君安資產管理(亞洲)有限公司), since its English form differs from the one the firm publishes. None of the four carries a public disciplinary record on the register. We did not have access to the text of the licensing conditions themselves, so we cannot say whether any of the fourteen conditions recorded across these entries touch on client geography, only that the conditions exist and the register did not show us their wording.
A Hong Kong Stock Exchange Main Board listing (1788.HK) for the holding company, a Shanghai/Hong Kong dual listing (601211.SH / 2611.HK) for the controlling shareholder, and a Hanoi Stock Exchange listing (IVS.HN) for the Vietnam subsidiary are registrations we hold no register entry for, so none of the three has been checked. That is a gap in our own directory, not a finding about the firm.
A clean result on our own warning-list search
We searched 1,441 warning-list entries mirrored from the CySEC, FCA and FSC Mauritius blacklists, running a positive control against a firm known to be listed on each source first, so that an empty result means absence rather than a search that silently failed to work. Guotai Junan International matched none of the 1,441 entries. That covers only the three regulators we mirror; it is not a finding that any other authority has, or has not, flagged the firm or restricted the countries it may serve.
Conclusion
Guotai Junan International scores 5.6 out of 10 here, up from the 4.2 we gave it previously. The move is ours, not the firm’s: this review draws on the SFC register directly and on the firm’s own published fee PDF, where the earlier version leaned more on secondhand claims. Regulation moved to 7.5 because the Hong Kong SFC register confirms multiple licensed entities in the group, and fees sit at just 2 because what we could read of the firm’s own charges is a stack of statutory pass-throughs and fund minimums rather than anything a CFD trader would recognise as a competitive cost structure.
What the SFC register actually confirms for Guotai Junan
We searched the Hong Kong SFC Public Register of Licensed Persons and Registered Institutions directly, running a positive control first so an empty result would mean absence rather than a broken search. Guotai Junan Securities (Hong Kong) Limited holds CE reference ABY236, licensed for Type 1, Type 2 and Type 4 activities (dealing in securities, dealing in futures contracts, advising on securities), all shown active, with 10 licensing conditions attached. Guotai Junan Asset Management (Asia) Limited holds CE reference ADH990 for Type 1, Type 4 and Type 9 (asset management), also active, carrying 3 licensing conditions, and matched on the Chinese register name Guotai Junan Asset Management (Asia) Limited (國泰君安資產管理(亞洲)有限公司) since the English form printed there differs from what the firm uses on its own site. Guotai Junan Futures (Hong Kong) Limited holds ADI115 for Type 2 and Type 5, and Guotai Junan FX Limited holds AUZ981 for Type 3 (leveraged foreign exchange trading), with 1 licensing condition. None of the four entries carries a public disciplinary record on the register. We also searched 1,441 warning list entries mirrored from CYSEC, the FCA and the FSC Mauritius, and the firm appears on none of them; that result covers only the lists we mirror, not every regulator worldwide, but it is a clean result the earlier review did not have.
Three other numbers the firm cites, the HKEX Main Board listing 1788.HK, the parent’s dual listing as 601211.SH and 2611.HK, and the Vietnam subsidiary’s IVS.HN, sit outside any register we hold, so we have not checked them; that is a gap in our directory, not a finding about the firm.
Fees: statutory pass-throughs, not a trading cost sheet
We read the firm’s Hong Kong stock fee schedule PDF, effective 1 September 2026, rather than a summary of it. It lists stamp duty at 0.10% of consideration, an HKEX trading fee of 0.00565%, an SFC transaction levy of 0.0027%, an AFRC transaction levy of 0.00015%, a CCASS settlement fee of 0.0042% and a CCASS DVP settlement fee of 0.002% with a minimum of HKD 2 and a maximum of HKD 100. The schedule states no brokerage commission rate of its own. The same document sets a dividend collection fee of 0.12% of the gross dividend, minimum HKD 2, maximum HKD 5,000, plus HKD 50 per stock, and a stock withdrawal fee via CCASS of 0.002% of the previous close, minimum HKD 2, plus HKD 500 per stock. On the fund side, the Greater China Growth Fund’s redemption fee steps down from 1.00% under six months of holding to nil only at 24 months or more, and its trustee fee carries a floor of HKD 412,000 a year regardless of fund size; the HKD and USD money market funds carry administration fees with monthly floors of HKD 31,200 and USD 4,000 respectively. These are the charges the firm’s own pages disclose. We did not find, on the pages we fetched, a spread or commission table for CFD or forex trading itself.
Platform and support
The account-opening pages point to MT4 for forex accounts, a separately branded Esunny (易盛) platform with its own application and termination forms, and the firm’s own Junhong Quanqiutong (君弘全球通) app; the site carries an active warning that a lookalike app named Junan Guoji (君安國際) has appeared on Google Play and the App Store, alongside a sitewide scam alert telling visitors to verify official contact channels before trusting anyone claiming to represent the firm. Support channels published on the contact page include a general switchboard, a 24 hour trading hotline, a separate complaints hotline and email, and an online chat widget, which is a reasonable spread of first party contact points even without a stated response-time commitment.
Guotai Junan International is a group of SFC-licensed Hong Kong entities with a clean result across the warning lists we checked, but its own published fee material covers statutory exchange charges and fund costs rather than CFD trading terms. TrueBroker scores it 5.6 out of 10.
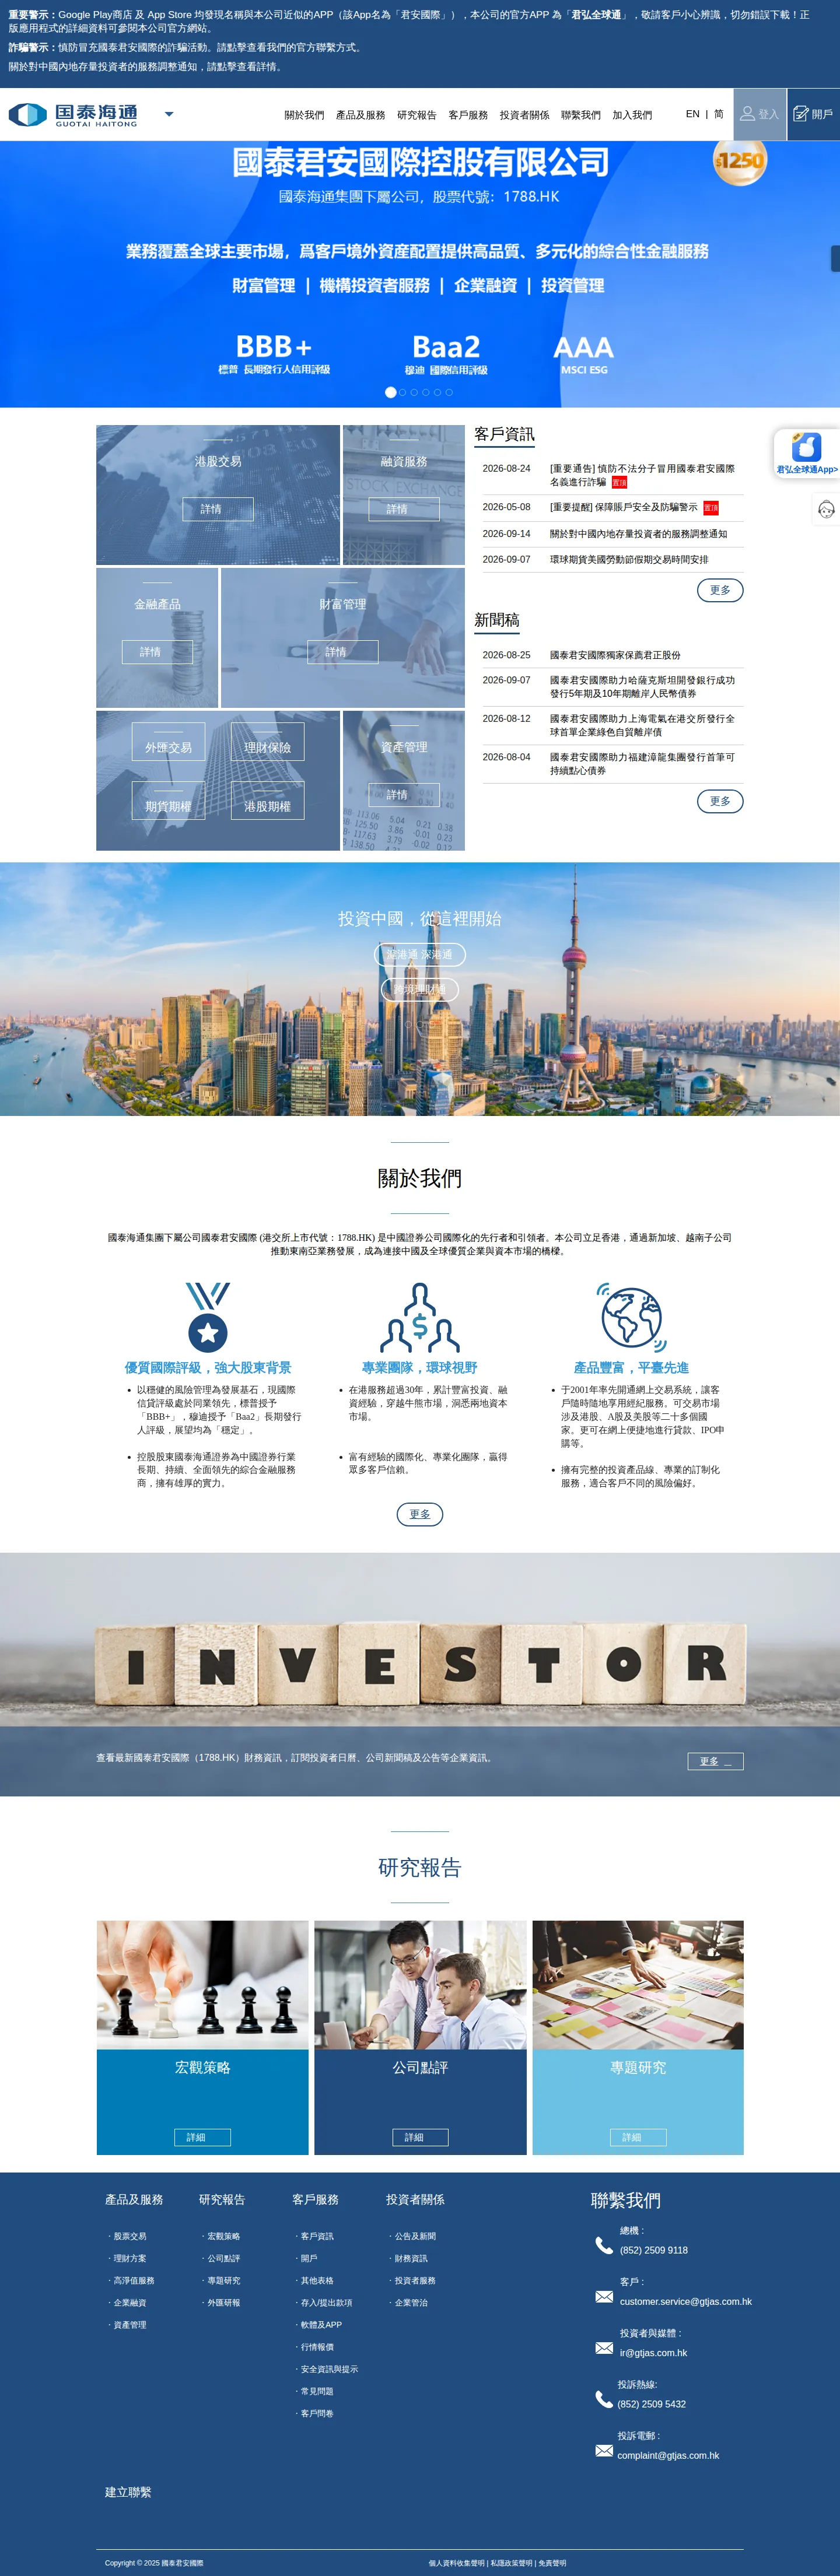
What we saw
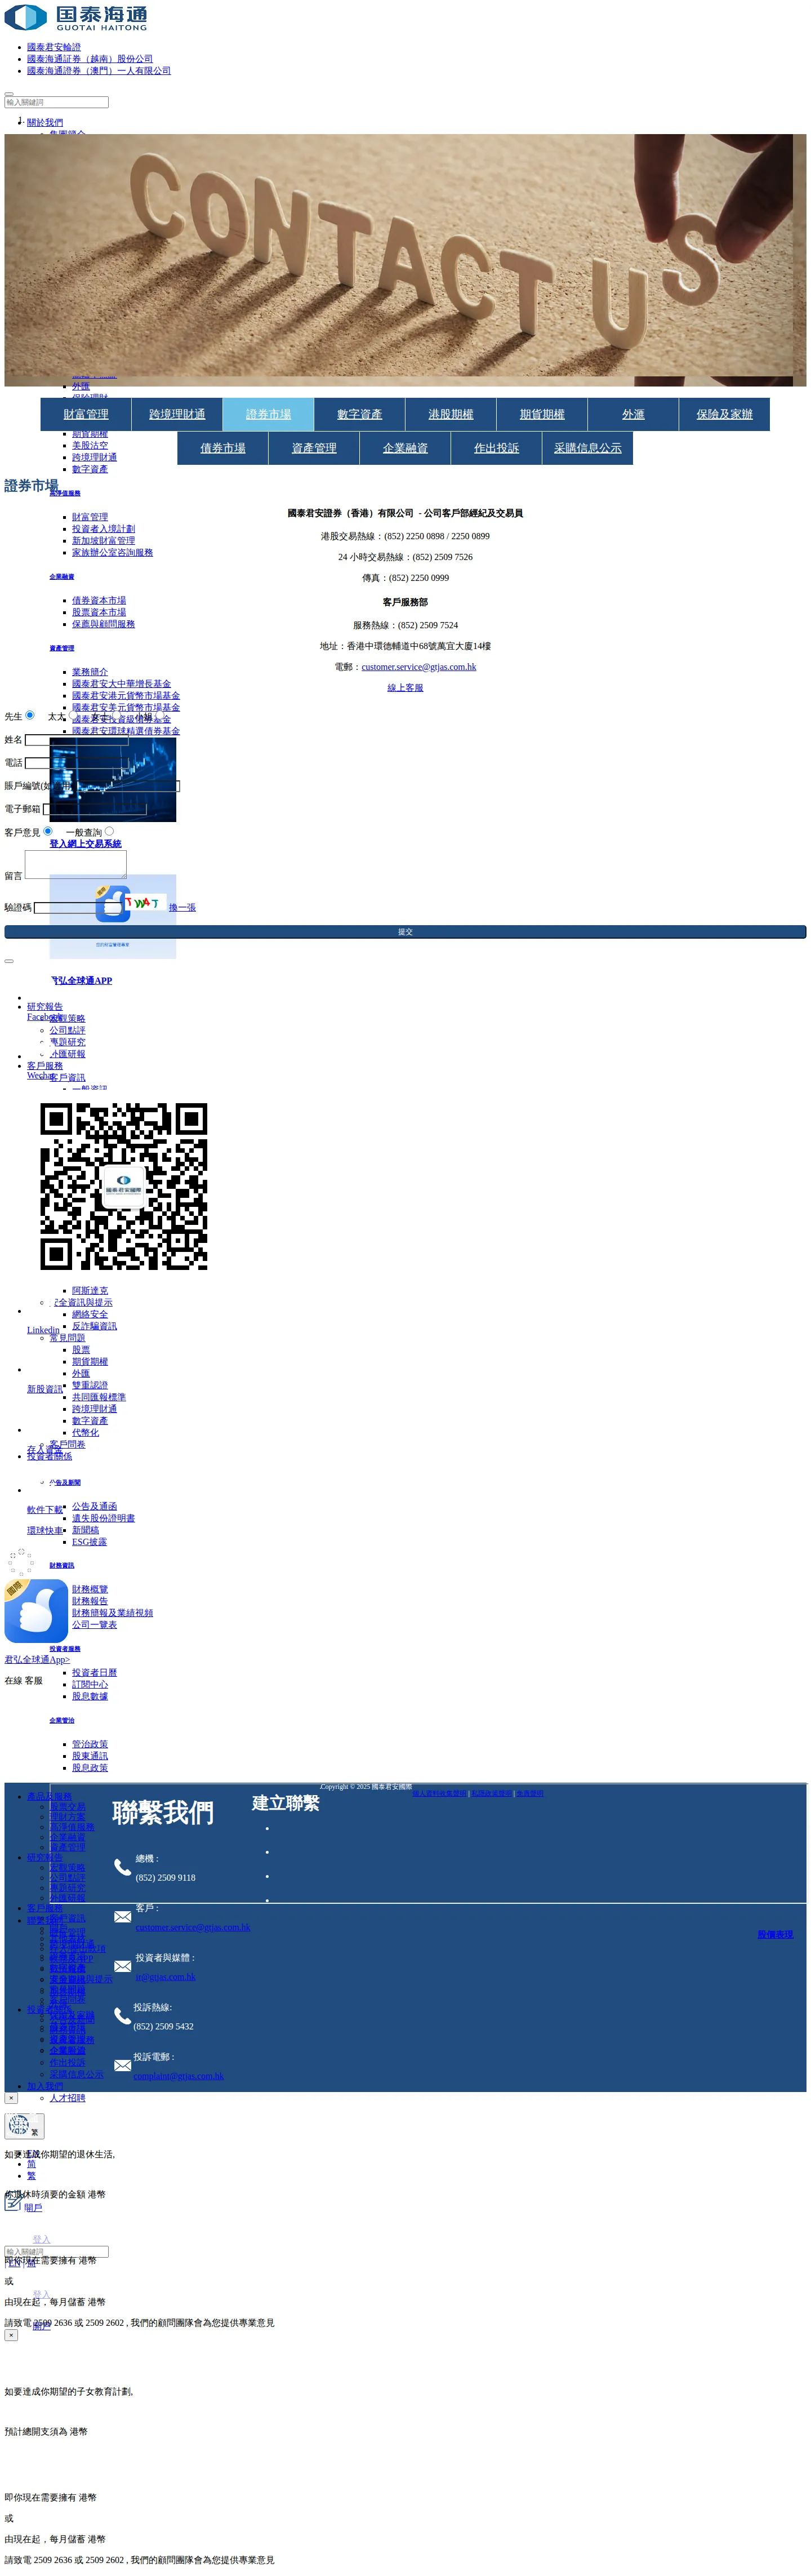
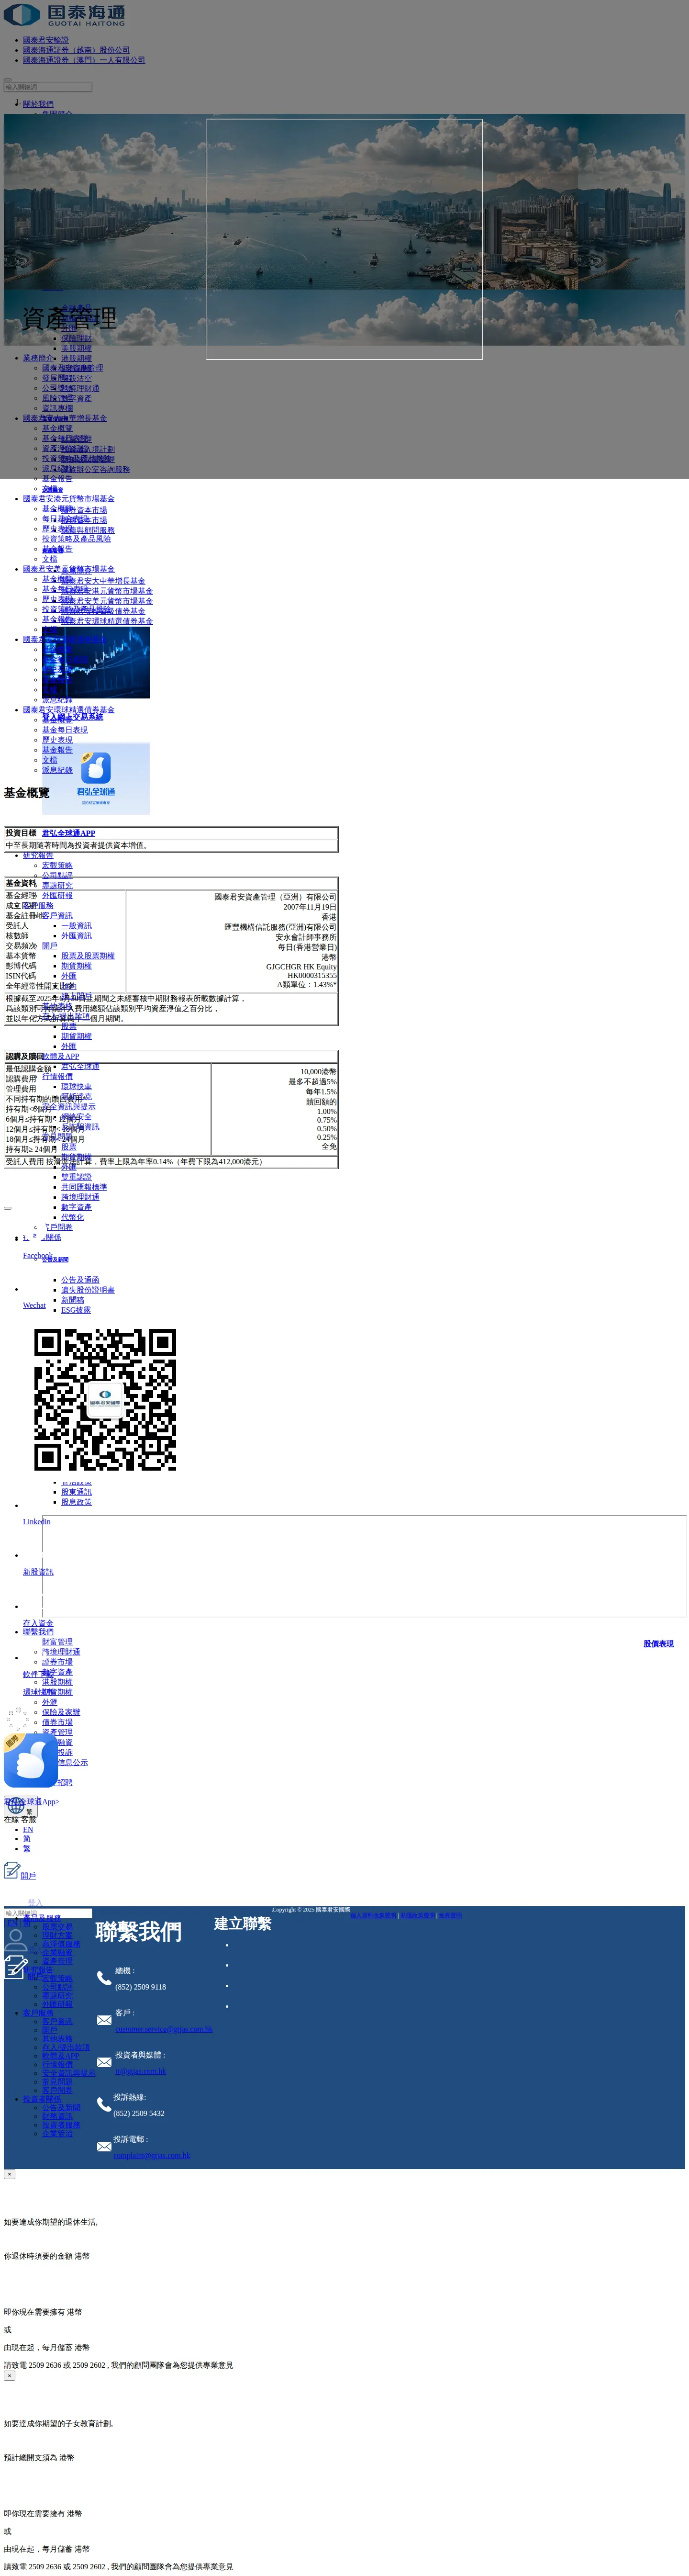
Pages captured from Guotai Junan International’s own site when this review was written. Brokers change their terms; these are what we read.
Score history
Recomputed daily; every move is on the record. The current score is always the latest row.
| Date | Score | Move |
|---|---|---|
| 2026-09-22 | 5.6 | ▲ |
| 2026-07-25 | 4.2 | ▲ |
| 2026-07-18 | 4.0 | = |
| 2026-07-11 | 4.0 | · |
FAQ
Is Guotai Junan International regulated?
Yes. Four group entities carry active SFC licences on the Hong Kong public register: ADH990, ADI115, AUZ981 and a securities licence, none flagged for discipline.
What does Guotai Junan charge to trade?
No cost of trading is published on the broker’s own pages or documents.
Does Guotai Junan International have a credit rating?
The group carries a Moody’s Baa2 and an S&P BBB+ rating, both independently verifiable.
Is Guotai Junan a listed company?
Yes, it has been listed on the HKEX Main Board since 2010.
What trading platforms does Guotai Junan offer?
MetaTrader 4, its own mobile app, a generic online trading login, plus separate platforms Global Express and Esunny; Aastocks appears to be a market-quotes tool rather than a trading platform.
How good is Guotai Junan's customer support?
It’s reachable by email, live chat and phone with published hours, but which entity handles your account and escalations depends on which unit onboarded you.
How this review works
Track Guotai Junan International live: score moves and red notices, in your pocket.