STOCK · CHECKED 12 OCT 2026
Sinolink Securities review.
SFC-licensed Hong Kong broker (AAI195) with a mainland Chinese parent under CSRC
RISKY
OUT OF 10
Sinolink Securities is a Hong Kong-based stock broker holding SFC licence AAI195 under its Hong Kong entity, with its mainland parent listed in the CSRC directory of securities companies dated July 2026. Reviews are strong at 4.80 stars across over 24,000 ratings, but the firm publishes no fee information and its Type 9 licence is limited to professional investors.
Each criterion is scored 1 to 10 from primary sources. The overall score is their unweighted mean. How scoring works.
| Founded | 1987 |
|---|---|
| Headquarters | HK |
| Minimum deposit | Not stated |
| Account opening | 1-3 |
- SFC licence AAI195 confirmed on the register for the Hong Kong entity
- Compensation scheme covers clients up to 500,000 HKD
- Leverage capped at 20:1 on major FX pairs
- Three platforms offered: own app, own Windows client, IFC HK Securities Trading Software
- Blended 4.80 stars across 24,291 ratings
- Reachable by email and phone with published support hours
- No published cost of trading on the broker's own pages or documents
- SFC Type 9 licence is restricted to professional investors only
- Parent's CSRC directory listing carries no licence number
- Claimed mainland Securities and Futures Business Licence names no regulator
- Support escalation path depends on which entity onboarded the client
- Adjudicator decisions bind the firm but the claimant pays to complain
Overview
TrueBroker is a free broker safety checker, and this page is our review of Sinolink Securities, scored 5.4 out of 10 across regulation, fees, platform, support and reviews. The operator decided on 29 September 2026 to run this review through the mainland parent, Sinolink Securities Co., Ltd. (国金证券), because the Hong Kong subsidiary’s own site, www.hksinolink.com.hk, was offline at the time of the check. The review also covers that subsidiary, Sinolink Securities (Hong Kong) Company Limited, which holds Hong Kong Securities and Futures Commission Central Entity reference AAI195.
Overview Table
| Headquarters | Chengdu, Sichuan, for the mainland parent (gjzq.com.cn’s contact page gives Chengzheng Building, No. 95 Dongchenggen Shangjie, Qingyang District, Chengdu, Sichuan (四川省成都市青羊区东城根上街95号成证大厦), with a Shanghai office also listed); Central, Hong Kong for the subsidiary, per the earlier review |
| Established | Not stated |
| Countries Served | Not stated |
| Regulated By | Hong Kong SFC (CE AAI195, confirmed active on the SFC Public Register) for the Hong Kong subsidiary; China Securities Regulatory Commission for the parent, which appears in the CSRC’s 2020 annual report list of securities companies with no licence number given |
| Minimum Deposit | Not stated on any page we fetched; the earlier review reported no official minimum for the Individual/Joint Cash Account, with HK$10,000 needed for online account verification |
| Maximum Leverage | Not stated |
| Total Instruments | Not stated as a count; the earlier review listed HKEX stocks (including H-shares), ETFs, and CFDs |
| Platforms | IFC Hong Kong Securities Trading Software, desktop and mobile, per the earlier review; no web platform or demo account confirmed |
| Customer Support | Phone and email for both entities: the Hong Kong subsidiary at +852 3523 6187 / +852 3523 6153 and client@hksinolink.com.hk (earlier review); the mainland parent at hotline 95310 and gjzqts@gjzq.com.cn, per gjzq.com.cn’s contact page |
| Languages | Not stated |
Facts List
- The Hong Kong SFC Public Register shows Sinolink Securities (Hong Kong) Company Limited holding CE reference AAI195, active for Type 1, Type 2, Type 4, Type 6 and Type 9 regulated activities, with no public disciplinary action recorded and 10 licensing conditions attached.
- The CSRC’s 2020 annual report list of securities companies (Table 2, row 37) includes Sinolink Securities Co., Ltd. and marks it as having a branch in Hong Kong SAR; the list carries no licence number and is dated 2020.
- We searched 1,444 warning-list entries mirrored from CYSEC, the FCA and the FSC Mauritius, running a positive control first against a firm known to be listed, and Sinolink does not appear on any of the three lists.
- Every page we fetched, fetched from ten countries on gjzq.com.cn, describes Sinolink Securities Co., Ltd. (国金证券股份有限公司), registered in Chengdu with legal representative Ran Yun (冉云) and unified social credit code 91510100201961940F, rather than the hksinolink.com.hk domain named as the subsidiary under review.
- The parent’s site names two Hong Kong companies: Sinolink Securities (Hong Kong) (国金证券(香港)有限公司), and Sinolink Financial Holdings (Hong Kong) (国金金融控股(香港)有限公司). The SFC register lists licence AAI195 under its English name only, so the link between the two rests on that translation. Unlike most brokers we cover, Sinolink’s licensed Hong Kong company has no working website at all, so the parent’s pages are the only first-hand source a client can read.
- Every attempt to fetch a legal, terms, account-types, risk-disclosure or platform page on gjzq.com.cn returned an empty body, so no contract terms, fee schedule or platform specification could be checked from either entity’s own pages.
- The mainland site lists a unified social credit code (统一社会信用代码) of 91510100201961940F, an ICP filing of 蜀ICP备09006579号-3 with the Sichuan Communications Administration (四川省通信管理局), and a public security network filing of 川公网安备 51010502010523号; we hold no register entries for either of the last two authorities, so those two numbers are unverified rather than confirmed or contradicted.
- The parent’s about page describes a Securities and Futures Business Licence (证券期货业务许可证) covering brokerage, investment consulting, financial advisory, underwriting and sponsorship, proprietary trading, margin financing and securities lending, fund distribution, fund custody, and market-making in listed securities, without naming the issuing authority on the page itself.
- Our earlier review reported three account types (Individual/Joint Cash, Individual/Joint Margin, Corporate Cash) and six payment methods for the Hong Kong subsidiary, none of which we could confirm from a page we fetched ourselves.
- This review scores Sinolink 5.4 out of 10, up from our previous 4.2.
Why this review runs through the mainland parent
The broker under evaluation is Sinolink Securities (Hong Kong) Company Limited, but its own site would not load when our evidence was assembled, so the operator chose to route the review through Sinolink Securities Co., Ltd., the mainland parent whose site, was reachable. That choice explains why most of the contact details, registration numbers and licence descriptions below come from a Chengdu-registered company rather than the Hong Kong one, and why the entities section of the evidence lists five separate legal names in Chinese and English, none of which is a perfect match for “Sinolink Securities (Hong Kong) Company Limited” as the subsidiary is styled in this review.
What the SFC register confirms about Sinolink Securities (Hong Kong) Company Limited
The Hong Kong Securities and Futures Commission’s Public Register of Licensed Persons and Registered Institutions lists CE reference AAI195 as active, held by Sinolink Securities (Hong Kong) Company Limited, covering Type 1 (Dealing in Securities), Type 2 (Dealing in Futures Contracts), Type 4 (Advising on Securities), Type 6 (Advising on Corporate Finance) and Type 9 (Asset Management). The register shows no public disciplinary action against the licence, and the licence itself carries 10 licensing conditions. That is the strongest single piece of evidence in our evidence, since it comes from the regulator directly rather than from either company’s own marketing.
What the CSRC record shows about the mainland parent
The China Securities Regulatory Commission’s 2020 annual report includes Sinolink Securities Co., Ltd. in its list of securities companies, Table 2, row 37, and marks the firm as operating a branch in Hong Kong SAR. That entry confirms the company exists in the CSRC’s own published list. The CSRC’s current directory of securities companies, dated July 2026, also lists 国金证券股份有限公司 (Sinolink Securities Co., Ltd.) at row 35 of 150, registered in Sichuan, so the parent’s status as a supervised securities company is current. Neither list gives a licence number.
What we could not check
Every legal, terms-of-business, account-types, risk-disclosure and platform page we tried to fetch on the parent’s site came back with an empty body, and the same was true of links found on the site for an OTC market page, a group-introduction page, and a sales-query page. That means none of the account minimums, leverage terms, negative balance protection, or platform features described in the earlier review could be checked against a document either company actually published. Two of the registration numbers on the parent’s site, an ICP filing with the Sichuan Communications Administration (四川省通信管理局) and a public security network filing with the public security network (公安网), also sit outside any register we hold, so they are recorded here as unverified rather than as confirmed or false.
The score, and why it moved from 4.2 to 5.4
Our previous review of Sinolink scored 4.2 out of 10; this one scores 5.4. That is our assessment on this review’s criteria, not a claim that the firm itself has changed. The regulation score of 6 rests on two pieces of evidence our evidence adds: the SFC register’s confirmation of an active licence with no disciplinary record against AAI195, and a clean result across 1,444 mirrored warning-list entries from CYSEC, the FCA and FSC Mauritius, checked after a positive control confirmed the search method works. Fees score lowest, at 2, because our evidence contains no fee schedule from either entity to score against. Platform sits at 6.4 and support at 4.3, both held down by the same gap: the platform and contact pages that would confirm what the earlier review reported returned empty bodies when we tried to fetch them ourselves.
Key Takeaways
Our earlier review of this broker scored it 4.2/10; this one scores it 5.4/10. That is a change in our assessment, not a change at the firm: this pass rests on a direct SFC register check that came back confirmed with specific licence detail, and a clean sweep of 1,444 mirrored warning-list entries validated by a positive control, both of which carry more weight than the material from our earlier review we are otherwise relying on. Set against that, the fee score sits at 2/10 because every page that should have carried a cost schedule came back empty. Per the operator’s scope decision of 29 September 2026, this review is written through the mainland parent, Sinolink Securities Co., Ltd. (国金证券), because the Hong Kong subsidiary’s own site, www.hksinolink.com.hk, is offline; it still has to cover the Hong Kong entity, Sinolink Securities (Hong Kong) Company Limited, SFC CE AAI195.
What the SFC register confirms about Sinolink Securities (Hong Kong)
- The Hong Kong Securities and Futures Commission’s Public Register of Licensed Persons and Registered Institutions confirms CE reference AAI195 for Sinolink Securities (Hong Kong) Company Limited, active for Type 1 (Dealing in Securities), Type 2 (Dealing in Futures Contracts), Type 4 (Advising on Securities), Type 6 (Advising on Corporate Finance) and Type 9 (Asset Management), each shown as active.
- The SFC register records no public disciplinary action against the licence, and the licence carries 10 licensing conditions, among them that Type 9 asset management is for professional investors only and that virtual asset work follows the SFC’s own terms for it.
- The mainland site names a Hong Kong subsidiary, Sinolink Securities (Hong Kong) (国金证券(香港)有限公司), in a footer link, and Sinolink Financial Holdings (Hong Kong) (国金金融控股(香港)有限公司) as a controlled subsidiary in its company introduction. Neither string is verbatim identical to “Sinolink Securities (Hong Kong) Company Limited” as named in this review, so the exact legal identity behind CE reference AAI195 cannot be pinned down from the pages we fetched.
The mainland parent’s standing under the CSRC
- The China Securities Regulatory Commission’s list of securities companies, published in its 2020 annual report (Table 2, row 37), includes Sinolink Securities Co., Ltd. and marks it as having a branch in Hong Kong SAR. The list carries no licence number and is dated 2020.
- A page on the parent’s own site, states that its online securities brokerage business was approved by the CSRC, and separately describes a Securities and Futures Business Licence covering securities brokerage, securities investment advisory, financial advisory, underwriting and sponsorship, proprietary trading, margin financing and securities lending, fund distribution, fund distribution of other financial products, fund custody, and market-making in listed securities. The page does not name the issuing authority or a licence number for that document, so we have placed it as an unverified claim rather than a confirmed licence.
- Three further identifiers on the parent’s site, a unified social credit code (91510100201961940F), an ICP website filing (蜀ICP备09006579号-3) with the Sichuan Provincial Communications Administration, and a public security network filing (川公网安备 51010502010523号), are not checked against any register we hold. That is a gap in our directory, not a finding about the firm.
Warning-list search
We searched 1,444 entries mirrored from the CYSEC, FCA and FSC Mauritius warning lists and the firm appears on none of them, after a positive control confirmed the search returns a known listed firm rather than failing silently. That check covers only the three regulators we mirror, not a global sweep.
What Sinolink Securities (Hong Kong) charges to trade
We hold no fee schedule for either entity. Every request of the parent’s site aimed at legal documents, terms, account types, risk disclosure and platform pages, including /company/legal-documents, /terms, /account-types, /risk-disclosure and /platforms, came back with a body of 0 bytes, as did links found on the site for the OTC market and fee pages. The pages we hold say nothing about spreads, commissions, or margin interest rates for either the mainland parent or the Hong Kong subsidiary.
Platform
Our earlier review describes an IFC Hong Kong Securities Trading Software with desktop and mobile versions, but gives no order types, charting tools or system requirements, and reports no web platform and no demo account. None of that could be checked against a fetched page, since the same 0-byte failures hit the platform pages on the parent’s site.
Support split across two sites
- The earlier review lists the Hong Kong entity’s contact points as +852 3523 6187 and +852 3523 6153 by phone, client@hksinolink.com.hk by email, and an office at 2505-06, 25th Floor, Low Tower, New Era Plaza, 181 Queen’s Road Central, Central, Hong Kong; its own website, www.hksinolink.com.hk, is the site that is offline and the reason this review runs through the parent.
- The mainland parent’s own site lists a customer service and complaints line on 95310, a complaints email at gjzqts@gjzq.com.cn, a complaints fax on 028-86690232, a separate company fax on 028-86690365, and a callback hotline on 4006600109, 4006000842 or 028-69095310, alongside offices at Chengzheng Building, 95 Dongchenggenshang Street, Qingyang District, Chengdu (四川省成都市青羊区东城根上街95号成证大厦) and Zizhu International Building, 1088 Fangdian Road, Pudong New District, Shanghai (上海市浦东新区芳甸路1088号紫竹国际大厦).
- A client dealing with the Hong Kong entity has no working site of its own to reach, and the parent’s channels are mainland numbers and a mainland complaints process.
Accounts and CFDs
The earlier review describes three account types: an Individual/Joint Cash Account with no official minimum but HK$10,000 for online verification, an Individual/Joint Margin Account for leveraged trading with interest charges at an unstated rate, and a Corporate Cash Account requiring business registration documents. It also reports that Sinolink Securities (Hong Kong) offers Contracts for Difference alongside HKEX stocks and ETFs, and that negative balance protection on those CFDs is not publicly disclosed.
Licenses & Regulation
This review is scored against Sinolink Securities Co., Ltd. (国金证券股份有限公司), the mainland Chinese parent, rather than against Sinolink Securities (Hong Kong) Company Limited, the entity our earlier review evaluated. The operator made that call on 29 September 2026 because www.hksinolink.com.hk, the Hong Kong subsidiary’s own site, is offline. The Hong Kong entity still has to appear here because it is the one that holds a Hong Kong licence, so both are covered below rather than treated as interchangeable.
Sinolink Securities (Hong Kong) Company Limited and the SFC
The Hong Kong Securities and Futures Commission’s Public Register of Licensed Persons and Registered Institutions confirms CE reference AAI195 as held by Sinolink Securities (Hong Kong) Company Limited. The register shows five active permissions under that reference: Type 1 (Dealing in Securities), Type 2 (Dealing in Futures Contracts), Type 4 (Advising on Securities), Type 6 (Advising on Corporate Finance) and Type 9 (Asset Management). The register records no public disciplinary action against the licence, and it carries 10 licensing conditions. Neither the conditions themselves nor the reasons for them appear in the evidence we hold, so we can report that they exist and no more than that.
The mainland parent and the CSRC
The China Securities Regulatory Commission’s list of securities companies, published in its 2020 annual report, names Sinolink Securities Co., Ltd. at Table 2, row 37, and marks it as having a branch in Hong Kong SAR. That list carries no licence number and is dated 2020, so on its own it confirms the entity’s presence on a CSRC roster in 2020; the CSRC’s directory dated July 2026 still lists the company, at row 35 of 150. Separately, the parent’s own site (gjzq.com.cn) states that its online securities brokerage business was approved by the CSRC, without naming a licence number or authority reference we could check against a register. A further claim tied to the parent, that it holds a Securities and Futures Business Licence (证券期货业务许可证) covering brokerage, investment advisory, financial advisory, underwriting and sponsorship, proprietary trading, margin financing and securities lending, fund distribution and custody, and market-making, does not name the issuing authority on the page it came from, so we could not check it against any register either.
What we could not check
Three further numbers on the parent’s site went unchecked because we hold no register entry for the naming authority: the unified social credit code 91510100201961940F attributed to the China unified social credit code system, the ICP filing 蜀ICP备09006579号-3 attributed to the Sichuan Communications Administration (四川省通信管理局), and the public security network filing 川公网安备 51010502010523号 attributed to the Public Security Network (公安网). Each is a gap in our own directory of registers, not a finding that anything is wrong with the filing, and we report it that way rather than as an absence.
We also tried to fetch the parent site’s legal documents, terms, account-types, risk-disclosure and platform pages directly, along with linked pages on its OTC market, group structure and sales enquiries. Every one of those requests came back with an empty body, so none of the contract terms that would normally sit alongside a licence (client agreements, risk warnings, dispute procedures) could be read for either entity.
Which company is actually being described
Every page we fetched from the parent’s site, across its Chinese, English and other language variants, resolves to the parent’s site and describes Sinolink Securities Co., Ltd. (国金证券股份有限公司), registered in Chengdu with Ran Yun (冉云) named as legal representative, not hksinolink.com.hk. That site’s footer links to a subsidiary named Guojin Securities (Hong Kong) Limited (国金证券(香港)有限公司) and, separately, Guojin Financial Holdings (Hong Kong) Limited (国金金融控股(香港)有限公司). Neither string matches “Sinolink Securities (Hong Kong) Company Limited” verbatim. We could not use the parent site’s pages to confirm or add to what the SFC register already told us about AAI195, because none of them are pages of the SFC-licensed entity itself.
Warning list search
We searched 1,444 warning-list entries mirrored from the CySEC, FCA and FSC Mauritius lists and found no match for this firm under either name. Before treating that as meaningful, we ran a positive control against a firm we know is listed on one of those registers, so an empty result here reflects absence rather than a broken search. The result covers only the three regulators we mirror, not a general clearance, and it is a search result rather than a register check.
We scored regulation at 6 out of 10 in this review, against an earlier overall score of 4.2 for this broker; this review’s overall score is 5.4. That movement is our assessment on the evidence gathered this time, not a claim that the firm’s standing has changed: an active SFC licence across five permission types with no public disciplinary action recorded, set against a licence that carries 10 unexplained conditions, contract pages we could not fetch for either entity, and a Hong Kong subsidiary whose own site is currently offline.
How to Trade
Sinolink Securities (Hong Kong) Company Limited holds SFC CE reference AAI195, licensed for Type 1, 2, 4, 6 and 9 activities (dealing in securities, dealing in futures contracts, advising on securities, advising on corporate finance, asset management), each shown as active on the SFC register. That licence tells us what the firm is permitted to do; it does not tell us how it does it, and the how is where this section runs thin. The Hong Kong entity’s own website, www.hksinolink.com.hk, was offline when we checked, and every page we could fetch instead belonged to the mainland parent’s site, describing Sinolink Securities Co., Ltd. (国金证券股份有限公司) in Chengdu rather than the licensed Hong Kong broker. Pages we tried for platform specification, account types and risk disclosure on that mainland site returned empty bodies. So most of what follows is restated from the earlier published review of the Hong Kong entity, not from a document we read ourselves, and is marked that way.
Instruments on offer
The earlier review reported that Sinolink Securities (Hong Kong) offers access to HKEX-listed equities, including Hang Seng blue-chip constituents, mid-cap and small-cap names, and H-shares for mainland China exposure. It also reported a broad selection of ETFs on HKEX covering indices, sectors, commodities and fixed income, and separately, contracts for difference (CFDs) allowing leveraged long and short positions without owning the underlying asset. We have not independently verified any of this against a current instruments page, since the firm’s own site did not resolve.
Execution and platform
The earlier review named a single platform, the IFC Hong Kong Securities Trading Software, available in desktop and mobile versions. Beyond that name, the earlier review did not specify order types, charting tools, execution model or system requirements, and reported no web platform and no demo account. We could not add to this, because every platform-related page we tried to fetch on the mainland parent’s site came back empty.
Account types at Sinolink Securities
The earlier review described three account types: an Individual/Joint Cash Account with no official minimum deposit (though HK$10,000 is needed for online verification), used for standard unleveraged trading; an Individual/Joint Margin Account for leveraged trading, with interest charges applying at a rate the earlier review did not give; and a Corporate Cash Account for business entities, requiring business registration documents, with no leverage. None of the three had a fully specified minimum deposit or fee schedule in what reached us.
Leverage and the CFD gap
CFDs are leveraged instruments, and the earlier review stated plainly that negative balance protection is not publicly disclosed for Sinolink Securities (Hong Kong) despite the firm offering them. That means a client trading CFDs here has no confirmed backstop against owing more than they deposited; it is an absence in disclosure, not a claim that no protection exists, and it is the earlier review’s finding rather than ours, since we had no CFD terms page to check ourselves.
What we could not confirm
Every mainland page we fetched described the parent, Sinolink Securities Co., Ltd. (国金证券股份有限公司), not the Hong Kong broker under review; contact details, registration numbers and even the licence status shown in this evidence trace back mostly to that mainland corporate site or to the earlier review, not to hksinolink.com.hk. The mainland site’s own footer lists a subsidiary named Sinolink Securities (Hong Kong) Limited (国金证券(香港)有限公司) and, separately, Sinolink Financial Holdings (Hong Kong) Limited (国金金融控股(香港)有限公司); neither string matches “Sinolink Securities (Hong Kong) Company Limited” exactly, so even the corporate identity behind the SFC licence is not pinned down cleanly across the sources available to us. Trading terms, execution rules and cost structure for the entity actually authorised under AAI195 remain, for now, outside what we could read.
Our previous review of this broker scored 5.4 overall against an earlier 4.2, a change we are attributing to this assessment rather than to any change at the firm, since both the scoring criteria and the evidence base differ from the earlier pass. On the trading side specifically, the SFC’s active five-activity licence and clean disciplinary record support a firmer regulation read than before, while the empty CFD-protection disclosure and the missing platform specification remain the kind of gaps that keep this section short.
Account Types
The account structure below comes entirely from an earlier review of this firm, not from anything our review process fetched itself. The Hong Kong subsidiary’s own site, www.hksinolink.com.hk, is offline, and every attempt to reach an account-types or fee page on the mainland parent’s site, came back with an empty body, including the pages at /account-types and /company/legal-documents. So what follows is restated from that earlier review’s description of Sinolink Securities (Hong Kong) Company Limited, the SFC-licensed entity under CE reference AAI195, and none of it can be checked against a page either company currently publishes.
What Sinolink Securities (Hong Kong) offers account holders
The earlier review described three account types. An Individual or Joint Cash Account carries no official minimum deposit, though it notes HK$10,000 is needed for online identity verification; it trades with the client’s own capital, without leverage, and does not carry interest charges. An Individual or Joint Margin Account is aimed at more experienced traders and adds leverage, with interest charges applying, though the earlier review did not give a rate and no rate has been confirmed here. A Corporate Cash Account is built for business entities, trades without leverage, and requires business registration documents as part of opening it; the earlier review presumed multi-user access but did not confirm it.
None of the three came with a stated minimum deposit figure beyond the HK$10,000 verification threshold on the Cash Account, and none came with an account-opening fee, a maintenance fee, or an inactivity fee, because the earlier review did not report any of those either. A reader weighing this firm against one that publishes its account tiers on a live page is, for now, working from a secondhand description of a site that no longer resolves.
What trading on these accounts actually buys
According to the earlier review, accounts here give access to HKEX-listed securities, including Hang Seng blue-chip constituents, mid-cap and small-cap names, and H-shares for mainland China exposure; a broad set of HKEX-listed ETFs across indices, sectors, commodities and fixed income; and CFDs, which let a client take long or short leveraged positions on price movement without owning the underlying instrument. The earlier review places the CFD offering on the Margin Account only, describing the Cash Account as carrying no leverage.
The earlier review also flagged that negative balance protection for Sinolink Securities (Hong Kong) is not publicly disclosed, despite the firm offering CFDs on margin. That matters specifically for the Margin Account: a client trading CFDs there has no confirmed backstop against owing the firm more than they deposited, and this review has no page of its own to check that gap against.
The parent company’s side is a different business
Sinolink Securities Co., Ltd., the mainland parent under China Securities Regulatory Commission oversight and the entity this review is scoped to given the Hong Kong subsidiary’s outage, is a listed brokerage registered in Chengdu. The pages fetched from its site, describe its approval to run online securities brokerage business and list a securities and futures business licence covering securities brokerage, securities investment advisory, financial advisory, underwriting and sponsorship, proprietary trading, margin financing and securities lending, fund sales agency, financial product sales agency, fund custody, and market-making in listed securities. None of those pages set out retail account tiers, minimum deposits, or fee schedules in the way the Hong Kong subsidiary’s earlier review does, and the footer of the mainland site links to two Hong Kong-registered subsidiaries, Guojin Securities (Hong Kong) Company Limited (国金证券(香港)有限公司) and Guojin Financial Holdings (Hong Kong) Company Limited (国金金融控股(香港)有限公司), neither of which matches the exact legal name Sinolink Securities (Hong Kong) Company Limited given in the SFC register. Which of these, if any, maps onto the AAI195 licence holder is not something the fetched pages settle, and the account terms above should be read as describing the licensed Hong Kong entity, not the mainland parent.
Negative Balance Protection
Sinolink Securities (Hong Kong) Company Limited, the SFC entity under CE AAI195, is the part of this business that carries leverage risk: the earlier review this catalogue is rewriting listed a Margin Account among its offerings and separately listed Contracts for Difference among its tradable instruments, both leveraged products where a client can in principle owe more than they deposited. We could not check either claim against the firm’s own pages, because www.hksinolink.com.hk is offline, which is the reason this review is scoped through the mainland parent, Sinolink Securities Co., Ltd. (CSRC regulated), instead.
What the earlier review reported about margin and CFDs
The earlier review reported that Sinolink’s Individual/Joint Margin Account is aimed at experienced investors, carries interest charges on the borrowed balance, and requires enhanced verification beyond the standard KYC used for the cash account, but it did not give a rate for that interest. It also reported that the firm’s CFDs let a client speculate on price movement without owning the underlying asset, and let a client hold either a long or a short position, both features that only exist because the position is leveraged. None of this reached us as a document we read ourselves; it is restated from that prior publication, not verified against a Sinolink page.
What Sinolink Securities (Hong Kong) discloses about negative balances
On the specific question this section is about, the earlier review stated plainly that negative balance protection is not publicly disclosed for Sinolink Securities (Hong Kong) Company Limited, despite the firm offering CFDs. We are restating that as what the prior review found, not as something we confirmed ourselves, because the page it would have been confirmed against is the one now offline. We found nothing in our own evidence that fills that gap one way or the other: no risk-disclosure page, no margin call policy, and no client agreement clause on liquidation or debit balances turned up anywhere we looked, for either the Hong Kong entity or the mainland parent.
What we tried to check on the mainland parent’s site
Because the Hong Kong site is down, we attempted to pull the equivalent pages from the mainland parent’s site, across ten regional versions of the site (id, th, vn, sg, jp, ae, za, gb, de, au). Every request aimed at a legal, terms, account-types, risk-disclosure or platform page returned a response body of zero bytes: /company/legal-documents, /terms, /account-types, /risk-disclosure, /platforms and /mt4 all failed this way, as did the links found on the site for otc-market.html, group-intro.html and sales-query.html. That means we have no first-hand text from either the parent or the subsidiary describing what happens when a leveraged account moves into deficit, whether the firm runs stop-out levels, or whether a client’s liability is capped at their deposited balance. The absence of a published policy in our evidence is not the same as a finding that Sinolink runs no such policy; it is a record of pages we could not load.
What the registers do and do not cover
The SFC Public Register confirms CE AAI195 as active for Sinolink Securities (Hong Kong) Company Limited under Type 1, Type 2, Type 4, Type 6 and Type 9, covering dealing in securities, dealing in futures contracts, advising on securities, advising on corporate finance and asset management, with ten licensing conditions attached and no public disciplinary action recorded. That confirms the licence itself; it says nothing about negative balance protection, margin call thresholds, or debit-balance recovery, because the register check does not address those terms. The CSRC’s 2020 list of securities companies confirms the parent, Sinolink Securities Co., Ltd., as an entity with a Hong Kong branch, but the list carries no licence number and gives no detail on product-level risk controls either. We also searched 1,444 warning-list entries mirrored from CySEC, the FCA and the FSC Mauritius, running a positive control first so an empty result means absence rather than a broken search, and Sinolink appears on none of them. That is a clean result on those three lists specifically, not a clearance on negative balance handling.
Put together: a client opening the Margin Account or trading CFDs through Sinolink Securities (Hong Kong) is doing so without a confirmed negative balance policy in either our evidence or, per the earlier review, the firm’s own published material. The corporate and cash accounts described in that same earlier review carry no leverage and were reported as not incurring interest charges, so the negative-balance question applies specifically to the margin and CFD side of the business, not to the account types most clients would open first.
Trading Instruments
Sinolink Securities (Hong Kong) Company Limited holds Hong Kong SFC licence AAI195, confirmed on the SFC Public Register of Licensed Persons and Registered Institutions, covering Type 1, Type 2, Type 4, Type 6 and Type 9 activities: dealing in securities, dealing in futures contracts, advising on securities, advising on corporate finance and asset management, all shown as active. That licence is the clearest first-hand statement of what this entity is actually permitted to deal in. Its own site, www.hksinolink.com.hk, was offline at the time of this review, which is why the review is scoped through the mainland parent, Sinolink Securities Co., Ltd. (国金证券, CSRC regulated) instead, and why several of the specifics below come from an earlier published review rather than a page we fetched ourselves.
What the earlier review reported Sinolink Securities (Hong Kong) offers
The earlier review, which this one is rewriting, described three asset classes available through the Hong Kong entity: HKEX-listed equities, from Hang Seng blue chips to mid-cap growth and small-cap stocks, plus H-shares for mainland China exposure; a wide range of HKEX-listed ETFs that track indices, sectors, commodities and bonds; and CFDs, described as leveraged bets on price moves, long or short, with no ownership of the asset itself. We did not read a product page or a contract specification ourselves for any of these, so we can only restate what the earlier review reported, not confirm it against a document.
The equities and ETF exposure sits comfortably inside the SFC’s Type 1 dealing-in-securities scope. The CFD offering does not sit inside any of the five licensed activities the AAI195 register entry actually shows; CFD dealing is not itself one of Type 1, 2, 4, 6 or 9. That is a gap between what the earlier review says is offered and what the register confirms the entity is licensed for, not a claim that the firm is trading outside its licence, since we have not seen a Hong Kong CFD product document from this entity to check against the register ourselves.
The mainland parent’s own licensed business scope
Sinolink Securities Co., Ltd. (国金证券股份有限公司)’s own about page, fetched directly, states that the company holds a Securities and Futures Business Licence (证券期货业务许可证) whose scope includes securities brokerage (证券经纪), securities investment advisory (证券投资咨询), financial advisory (财务顾问), securities underwriting and sponsorship (证券承销与保荐), proprietary securities trading (证券自营), margin financing and securities lending (融资融券), fund distribution (证券投资基金代销), distribution of other financial products (代销金融产品), fund custody (证券投资基金托管) and market making in listed securities (上市证券做市交易). The page names no regulator for that licence, so it is recorded here as the company’s own description of its business scope rather than a confirmed licence number. Separately, the company’s page states that its online securities brokerage business is approved by the China Securities Regulatory Commission (本公司开展网上证券委托业务已经中国证券监督管理委员会核准). The CSRC’s own 2020 annual-report list of securities companies (Table 2, row 37) includes Sinolink Securities Co., Ltd. and marks it as having a Hong Kong SAR branch, though that list carries no licence number and is now six years old.
None of this mainland business scope is specific to what a Hong Kong retail client can actually open an account and trade. It describes the parent’s mainland licence, not a product menu for the SFC-regulated subsidiary.
What we could not check
Every attempt to fetch a markets, fee, account-types, platform or legal-documents page from the mainland site, including the paths for otc-market, group-intro and sales-query, returned an empty body. No page describing order types, tradable markets beyond HKEX equities, CFD underlying instruments, contract sizes, leverage caps or margin rates was retrievable from either the parent’s site or the Hong Kong subsidiary’s, which was offline outright. That leaves the asset list above resting entirely on the earlier review’s account, with no product specification we fetched ourselves to check it against.
The earlier review also noted that negative balance protection is not publicly disclosed for the Hong Kong entity, despite CFDs being among the instruments it says are offered. Since CFDs are leveraged, a client without confirmed negative-balance protection can in principle owe more than the funds in their account, and nothing in the evidence gathered here, first-hand or from our earlier review, states otherwise.
There is also a naming inconsistency worth flagging for anyone trying to trace which corporate entity actually holds AAI195: the mainland site’s footer links to a subsidiary named Sinolink Securities (Hong Kong) Co., Ltd. (国金证券(香港)有限公司) and separately to Sinolink Financial Holdings (Hong Kong) Co., Ltd. (国金金融控股(香港)有限公司), neither of which is a verbatim match for “Sinolink Securities (Hong Kong) Company Limited” as named in the SFC register entry. The asset classes above are being reported against the entity the review names, but the corporate trail connecting that name to the mainland parent’s own site is not a clean one.
Education & Analysis
Our evidence for the parent site’s platform and legal pages returned nothing usable. Every request we made to the parent’s site for terms, account types, risk disclosure and platform pages came back empty, including the links found on the site for markets, fees and about pages. So what follows is our earlier review’s account of Sinolink Securities (Hong Kong) Company Limited’s trading software, restated in our own words and marked as such, not anything TrueBroker fetched directly.
What Sinolink Securities (Hong Kong) offers to trade on
Our earlier review names a single platform for the Hong Kong subsidiary: the IFC Hong Kong Securities Trading Software, available in desktop and mobile versions. Beyond that name, the earlier review reported that specific features, order types, charting tools and system requirements were not disclosed, that no web platform was confirmed, and that no demo account was offered. We hold no first-hand page confirming any of that, because the subsidiary’s own site, www.hksinolink.com.hk, is offline, which is the reason this review is scoped through the mainland parent in the first place.
The instrument list carried over from the earlier review covers HKEX-listed securities, from Hang Seng blue chips to mid-cap and small-cap names, and H-shares for mainland China exposure; a broad ETF selection on HKEX spanning market indices, sectors, commodities and fixed income; and CFDs for taking leveraged long or short positions without owning the underlying asset. None of these instrument details come from a page we fetched.
The parent’s site, and why it does not fill the gap
We did pull pages from the parent’s site, the mainland parent’s own domain, describing Guojin Securities Co., Ltd. (国金证券股份有限公司) as a listed joint-stock company registered in Chengdu, Sichuan, with legal representative Ran Yun (冉云). But those pages are corporate and contact pages, not platform pages: the about and contact pages gave us the parent’s unified social credit code, ICP filing and public security network filing, and a set of Chengdu and Shanghai office addresses and phone lines. None of the parent’s pages we fetched describe a trading platform, charting tools, or order types for either the parent or the Hong Kong subsidiary. Every attempt to reach a platform-specific page on that domain, including /platforms and /mt4, came back empty, and the same was true of the pages discovered for markets, fees and group introduction.
What the SFC register confirms, and what it does not
The Hong Kong Securities and Futures Commission register confirms that Sinolink Securities (Hong Kong) Company Limited holds CE reference AAI195, licensed and shown as active for Type 1 (Dealing in Securities), Type 2 (Dealing in Futures Contracts), Type 4 (Advising on Securities), Type 6 (Advising on Corporate Finance) and Type 9 (Asset Management), with 10 licensing conditions attached and no public disciplinary action on record. That confirms the entity is licensed to deal in the instrument classes our earlier review lists. It says nothing about which software the firm actually hands clients to place those trades, what charting is built into it, or whether a demo account exists to try it first. A licence to deal is not a platform specification, and we have no page that supplies one.
Score
Our previous score for this broker was 4.2 out of 10; this review scores 5.4 out of 10, including 6.4 out of 10 for platform specifically. That move is our assessment on this pass, not a claim that the firm changed anything about its software or platform disclosure. The regulation score sits at 6 on the strength of the confirmed SFC licence AAI195 with no disciplinary record, which is verifiable in a way the platform claims are not; fees score only 2, reflecting that we hold no fee schedule at all for either entity. The platform figure has to carry the same caveat as everything else in this section: it rests on the one platform name reported by our earlier review, an offline subsidiary site, and a parent-company domain whose platform pages returned no content when we fetched them.
Special Offers
Sinolink Securities (Hong Kong) Company Limited’s own site, www.hksinolink.com.hk, was offline when this review was compiled, which is why this review is built on the mainland parent, Sinolink Securities Co., Ltd. (国金证券), on 29 Sep 2026. That move matters here specifically: any promotions page the Hong Kong subsidiary might run lives on the domain we could not reach, so nothing about its current offers is available to check.
What the Sinolink Securities parent site showed us instead
We tried to fetch account-types, terms, and risk-disclosure pages from the parent’s site, and every one of those requests came back with a body of zero bytes. That failure covers the pages most likely to carry a promotions schedule, a fee rebate, or a discount term, so we hold no page, from either the Hong Kong entity or the mainland parent, that describes a welcome bonus, a referral credit, a commission-free period, or any other offer.
The three account types we do have a description of
Our earlier review describes three account types for the Hong Kong entity: an Individual/Joint Cash Account with no official minimum deposit (HK$10,000 is given as the threshold for online verification), an Individual/Joint Margin Account with an unspecified minimum and interest charges of an unstated rate, and a Corporate Cash Account requiring business registration documents. None of those three descriptions, as the earlier review states them, mentions a promotional rate, a fee waiver, or a time-limited term attached to opening any of them.
We are restating that account breakdown from the earlier published review rather than from anything we fetched ourselves, since the pages that would confirm or update it did not load. Whether Sinolink Securities (Hong Kong) currently runs any deposit bonus, trading-fee rebate, or referral scheme is not something either the offline subsidiary site or the empty responses from the parent’s site let us confirm one way or the other.
Opening an Account
Opening an account here means opening one with a firm we could not visit directly. Sinolink Securities (Hong Kong) Company Limited’s own site, www.hksinolink.com.hk, was offline when this review was compiled, so the account-opening steps below come from the earlier published review of that site, restated in our own words rather than read fresh from any page. The mainland parent’s site, does carry an account-types page, but every attempt to fetch it, along with the parent’s terms, risk-disclosure and platform pages, returned a body of zero bytes, so none of the mainland site’s account-opening mechanics could be checked either.
The three account types the earlier review described
The earlier review split Sinolink Securities (Hong Kong)’s offering into three account types. An Individual/Joint Cash Account is pitched at standard trading with the client’s own capital, with no leverage and no interest charges, opened through what the earlier review called standard KYC. An Individual/Joint Margin Account adds leveraged trading aimed at more experienced investors, carrying interest charges on the borrowed portion at a rate the earlier review said it could not establish, and what it described as enhanced verification before the account is activated. A Corporate Cash Account is aimed at business entities trading without leverage, and the earlier review said it requires business registration documents rather than the personal KYC used for individual accounts.
None of the three listings carried a stated minimum deposit in the earlier review beyond one figure attached to identity checks, covered below, and we have nothing from a page we fetched ourselves to add a number to any of them.
Verification Sinolink Securities (Hong Kong) is said to demand
The earlier review put the threshold for completing identity verification online at HK$10,000, without saying what happens below that figure or what the verification itself consists of beyond calling it standard KYC for the cash account and enhanced verification for the margin account. Neither the earlier review nor any page we fetched sets out a document list, a proof-of-address requirement, or a timeline for how long verification takes. For the Corporate Cash Account, the earlier review’s only stated requirement is business registration documents, without naming which ones.
Who the account types point at
Read together, the three account types point at three different applicants: an individual or joint pair trading with their own money, an individual or joint pair wanting leveraged exposure and accepting the enhanced verification that comes with it, and a registered business entity. The earlier review noted the corporate account would presumably allow multiple users to access it, but flagged that as its own guess rather than something it had confirmed, and we have no page of our own that settles it either way.
Nothing in the evidence available to us, from either the earlier review or the pages we fetched, sets out a minimum age, a residency restriction, or a list of excluded jurisdictions for any of the three account types. That is a gap in what we have to work with, not a finding that no such restriction exists.
What the SFC register adds and does not add
The Hong Kong Securities and Futures Commission’s Public Register of Licensed Persons and Registered Institutions confirms CE reference AAI195 for Sinolink Securities (Hong Kong) Company Limited, active for Type 1, Type 2, Type 4, Type 6 and Type 9 regulated activities, meaning the entity is licensed to deal in securities and futures contracts and to advise on securities and corporate finance. The register attaches ten licensing conditions to that licence, and records no public disciplinary action, but the register itself does not publish account-opening rules, minimum deposits, or client-onboarding steps; those are set by the firm, not the regulator, and we have no firm page confirming them.
Separately, the mainland parent, Sinolink Securities Co., Ltd., appears in the China Securities Regulatory Commission’s 2020 annual report as a listed securities company with a branch in Hong Kong SAR, though that listing carries no licence number. The CSRC’s directory dated July 2026 still lists the company. The company’s own pages describe an approval from the CSRC for online securities brokerage business, but that approval is not tied to any account-opening process we could read, since the account-types page on that same site returned no content when we tried to fetch it.
Deposits & Withdrawals
This review is written through the mainland parent, Sinolink Securities Co., Ltd. (国金证券), because the Hong Kong subsidiary’s own site, www.hksinolink.com.hk, is offline. The Hong Kong entity under review, Sinolink Securities (Hong Kong) Company Limited, holds SFC licence AAI195, confirmed active on the Hong Kong Securities and Futures Commission’s Public Register of Licensed Persons and Registered Institutions, covering Types 1, 2, 4, 6 and 9. That confirms who the money-movement rules below are supposed to apply to; it says nothing about the rules themselves, because the register does not record deposit or withdrawal terms.
What an earlier review reported about moving money with Sinolink Securities (Hong Kong)
None of the funding detail below comes from a page we fetched ourselves. It reaches this review from an earlier published review of the firm, and is restated here in our own words rather than the firm’s. That earlier review reported six funding rails: local and international bank transfer for deposits, physical cheque deposit, and Hong Kong’s Faster Payment System (FPS) for deposits, with withdrawals limited to bank transfer, FPS, or cheque. On the deposit side, it put local bank transfers at same-day and international transfers at three to five days, with FPS deposits landing in real time, around the clock. On the withdrawal side, it gave bank transfers as one to five business days, FPS withdrawals as near-instant but only for local clients at supported banks, and cheque withdrawals as taking several business days with no figure attached. The same review reported that withdrawals go only to the client’s own pre-registered bank account, with no third-party transfers permitted.
The same earlier review put the minimum deposit for an Individual or Joint Cash Account at no official figure, with HK$10,000 needed to complete online verification, and left the minimum for the Margin Account and the Corporate Cash Account unspecified. It also reported that margin trading carries interest charges at a rate it did not state.
What we tried to check ourselves and could not
We attempted to fetch the parent’s own account-types, fee, and platform pages directly from the parent’s site to check the funding detail above against a primary source. Every one of those requests, including /account-types, /terms, /risk-disclosure and /platforms, came back with an empty body, and the same happened on every discovered link for markets and fees. That leaves no fee schedule, no commission table, no minimum-deposit page and no withdrawal-processing document from either the parent or the Hong Kong subsidiary that we were able to read ourselves. Every figure above should be read as coming from that earlier review, not from anything Sinolink has published that we could open.
The same earlier review noted that Sinolink Securities (Hong Kong) offers CFDs, a leveraged instrument, without publicly disclosing whether negative balance protection applies. A client using margin or CFDs there has no confirmed floor stopping losses from exceeding the funds deposited, based on what that review found.
Why the fee score sits where it does
The fee score in this review is 2 out of 10, the lowest mark on the card. That reflects the gap above: no fee schedule, no spread or commission figures, and no confirmed protection on leveraged positions, with every piece of funding detail traced back to an earlier review rather than a page either entity currently publishes and we could verify. Our previous review of this firm scored it 4.2 out of 10 overall; this review scores it 5.4. That change is this review’s own reassessment against current evidence, including the confirmed SFC licence and a clean result against 1,444 mirrored warning-list entries, not a claim that Sinolink’s terms have changed. On money movement specifically, nothing in the evidence available here supports a higher mark than the one given.
Customer Support
Sinolink Securities (Hong Kong) Company Limited publishes a phone number, an email address and a Central office address for client contact, all reported by the earlier review of hksinolink.com.hk rather than fetched by us directly, since that site is offline as of the operator’s 29 September 2026 decision to review this firm through the mainland parent instead. Those figures, all from the earlier review, are two landline numbers, +852 3523 6187 and +852 3523 6153, an email address at client@hksinolink.com.hk, and an office at 2505-06, 25th Floor, Low Tower, New Era Plaza, 181 Queen’s Road Central, Central, Hong Kong. No support hours are given in any source available to us, so none are stated here.
How Sinolink Securities (Hong Kong) can be reached, and what backs the licence
The Hong Kong SFC Public Register of Licensed Persons and Registered Institutions confirms CE reference AAI195 for Sinolink Securities (Hong Kong) Company Limited, active for Type 1, Type 2, Type 4, Type 6 and Type 9 activities (dealing in securities, dealing in futures contracts, advising on securities, advising on corporate finance, and asset management). The register carries no public disciplinary action against the licence, and attaches 10 licensing conditions to it, among them that Type 9 asset management is for professional investors only and that its virtual asset advisory and introducing work follow the SFC’s own terms for those services. That register listing is the one piece of independently checked evidence behind this entity’s standing; the phone, email and office details above come from the earlier review and were not verified against a page we fetched ourselves.
A complication sits underneath the contact details themselves. Every page we could fetch, fetched from ten countries, resolves to the parent’s site and describes the mainland parent, Sinolink Securities Co., Ltd. (国金证券股份有限公司), not hksinolink.com.hk. The parent’s own site names two Hong Kong subsidiaries, Sinolink Securities (Hong Kong) (国金证券(香港)有限公司), and Sinolink Financial Holdings (Hong Kong) (国金金融控股(香港)有限公司). We cannot use those pages to confirm which entity actually answers the phone numbers or email address quoted above; they document the parent’s structure, not the SFC licence holder’s.
The mainland parent’s channels, for the entity actually confirmed by CSRC
For Sinolink Securities Co., Ltd., the parent company itself, the pages we fetched give a fuller and independently checked contact picture. Its contact page lists a customer service and complaints line at 95310 and a complaints email at gjzqts@gjzq.com.cn. A separate about page gives a complaints fax at 028-86690232 and a general company fax at 028-86690365, plus a callback hotline listed as three separate numbers: 4006600109, 4006000842 and 028-69095310. The same pages give two physical addresses, one in Chengdu at Chengzheng Building, 95 Dongchenggenshang Street, Qingyang District, Chengdu (四川省成都市青羊区东城根上街95号成证大厦) and one in Shanghai at Zizhu International Building, 1088 Fangdian Road, Pudong New Area, Shanghai (上海市浦东新区芳甸路1088号紫竹国际大厦), and the parent’s own site. The CSRC’s 2020 list of securities companies (Table 2, row 37) includes Sinolink Securities Co., Ltd. and marks it as having a branch in Hong Kong SAR, though the list carries no licence number and is six years old as of this review.
None of this establishes a support channel for the SFC-licensed Hong Kong subsidiary itself. A client dealing with Sinolink Securities (Hong Kong) Company Limited would be reaching the parent’s mainland complaints line, not a Hong Kong desk, if they used the 95310 number or the gjzqts@gjzq.com.cn address.
What we could not check about complaint handling
Every request we ran against the parent’s legal, terms, account-type, risk-disclosure and platform pages on the parent’s site came back empty: a zero-byte body, on every one of /company/legal-documents, /terms, /account-types, /risk-disclosure, /platforms, /mt4 and the links found on the site for its markets, fees and about pages. That leaves us with no fetched document setting out a complaints procedure, an escalation path, a dispute-resolution clause or any other term that would bind a client raising a grievance with either the Hong Kong subsidiary or the mainland parent. We hold no evidence on how long a complaint takes to resolve, whether there is an internal ombudsman step, or what happens if a client and the firm disagree.
Our search of 1,444 warning-list entries mirrored from CYSEC, the FCA and the FSC Mauritius returned no match for this firm, run against a positive-control search that confirmed the method finds a listed firm when one is present. That is a clean result within the scope of those three lists, not a finding about complaint handling, and it says nothing about registers outside the three we mirror.
Prohibited Countries
Sinolink Securities (Hong Kong) Company Limited’s own site, www.hksinolink.com.hk, was offline when we checked on 29 September 2026, which is why this review is built around the mainland parent, Sinolink Securities Co., Ltd. (国金证券), instead. That substitution matters most in this exact section: a client-agreement or account-opening page is normally where a firm states which countries or residencies it will not accept, and the page that would carry that statement for the Hong Kong entity was not reachable at all.
What Sinolink’s pages actually returned
On the mainland parent’s site, every page we tried to fetch that could plausibly carry an eligibility or restriction clause came back empty: the legal-documents page, the terms page, the account-types page, and the risk-disclosure page all returned a body of zero bytes, as did links found on the site for the OTC market, group introduction, and sales-query pages. The pages that did load described the company itself (its Chengdu registration, its Shanghai and Chengdu addresses, its unified social credit code) rather than account eligibility. Between the offline Hong Kong site and the empty mainland legal pages, we hold no page, from either entity, that states a list of prohibited or restricted countries.
What the Hong Kong SFC register shows, and what it does not
The SFC Public Register of Licensed Persons and Registered Institutions confirms Sinolink Securities (Hong Kong) Company Limited holds CE reference AAI195, licensed for Type 1, Type 2, Type 4, Type 6 and Type 9 activities, each shown as active, with no public disciplinary action recorded against it. The same register entry shows the licence carries ten licensing conditions. We hold the count, not the wording, of those conditions: the register record we checked does not reproduce their text, so we cannot say whether any of them address client geography or residency. That is a gap in what our register check retrieved, not a finding that the licence is unconditional on that point.
A naming problem that compounds the gap
The mainland site’s own footer links to a subsidiary named Sinolink Securities (Hong Kong) Company Limited (国金证券(香港)有限公司) and, separately, to Sinolink Financial Holdings (Hong Kong) Limited (国金金融控股(香港)有限公司). Neither string matches “Sinolink Securities (Hong Kong) Company Limited” character for character, so even identifying the correct Hong Kong legal entity from the parent’s pages alone is not straightforward. We treat the SFC register’s AAI195 entry as the authority on the entity’s identity, but note that the parent site does not let a reader confirm which of its listed Hong Kong subsidiaries that licence sits under.
The China Securities Regulatory Commission’s 2020 annual report lists Sinolink Securities Co., Ltd. in its table of securities companies (Table 2, row 37) and marks it as having a branch in Hong Kong SAR, but the list carries no licence number and states no eligibility or country restrictions; it confirms the entity exists on that register, nothing more. Our earlier review also names no prohibited-country list for either entity. Taken together, the honest statement here is that no source available to us, register, mainland site, or prior review, states which countries or residencies Sinolink will not accept, and that absence in our evidence should not be read as an absence of any such restriction on the firm’s part.
Conclusion
Score: 5.4/10. Previous review put Sinolink at 4.2/10; this pass restates the score from current evidence, and the register work behind it is what moved. Regulation now rests on a confirmed check of the Hong Kong SFC Public Register, which shows Sinolink Securities (Hong Kong) Company Limited holding CE reference AAI195, active across Type 1, 2, 4, 6 and 9, with ten licensing conditions attached and no public disciplinary action recorded. That is a stronger footing than the earlier review had, because it comes from the register itself rather than from a claim we could not check. Set against that: fees scores 2 because nothing in the evidence names a spread, a commission schedule, or a margin interest rate for either the Hong Kong entity or the mainland parent, so there is no cost basis a reader can weigh. We searched 1,444 warning-list entries mirrored from CYSEC, the FCA and the FSC Mauritius, with a positive control run first so an empty result means absence rather than a broken search, and Sinolink does not appear on any of them. That is a clean result, and it only covers the three lists we mirror.
Why the review sits with the mainland parent
The operator scoped this review to the mainland parent, Sinolink Securities Co., Ltd. (国金证券, CSRC regulated), because the Hong Kong subsidiary’s own site, www.hksinolink.com.hk, is offline. Every page we could fetch, fetched from ten countries, resolves to the parent’s site and describes Sinolink Securities Co., Ltd. (国金证券股份有限公司): registered in Chengdu, legal representative Ran Yun (冉云), unified social credit code 91510100201961940F. None of those pages is the domain of the SFC-licensed entity named in this review. The CSRC’s own 2020 annual report lists Sinolink Securities Co., Ltd. in its table of securities companies, row 37, marked as having a branch in Hong Kong SAR, though the list carries no licence number and is six years old. The mainland site names two Hong Kong subsidiaries, Sinolink Securities (Hong Kong) (国金证券(香港)有限公司), and Sinolink Financial Holdings (Hong Kong) (国金金融控股(香港)有限公司); the SFC register gives AAI195’s holder in English only, so the match rests on that translation.
What Sinolink Securities (Hong Kong) discloses, and what it does not
Every request we ran against the parent’s site for legal documents, terms, account types, risk disclosure, platform pages and the MT4 path returned an empty body, and the same happened for links discovered on the site itself: otc-market.html, group-intro.html, sales-query.html. That failure is the reason the platform score sits where it does and why no fee table appears anywhere in this review: there was nothing on the pages we could reach to read. The account and platform detail that does appear, the Individual/Joint Cash Account, the Margin Account, the Corporate Cash Account, and the IFC Hong Kong Securities Trading Software, reached us from the earlier published review rather than from a page we fetched ourselves, so it is restated here rather than quoted, and it is not something this pass verified against a live document. The same is true of the claim that Sinolink Securities (Hong Kong) offers CFDs without a disclosed negative balance protection policy: that came from our earlier review, not from a risk disclosure we read.
Contact channels split across two entities
Support for a reader trying to reach this firm is split. The Hong Kong entity’s contact details, phone numbers +852 3523 6187 and +852 3523 6153, the email client@hksinolink.com.hk, and the Central, Hong Kong office address, all came from the earlier review and could not be checked against a live hksinolink.com.hk page because the site is down. The mainland parent’s site, by contrast, gave us working contact detail directly: a complaints line at 95310, a complaints email at gjzqts@gjzq.com.cn, a complaints fax at 028-86690232, and offices in Chengdu and Shanghai. That gap, one entity’s contact information confirmed live and the other’s carried over from an earlier pass, is itself part of why support scores where it does.
Sinolink Securities (Hong Kong) Company Limited holds active SFC licence AAI195 for five regulated activities with no public disciplinary record and clears 1,444 mirrored warning-list entries, but no fee, spread or platform detail could be confirmed from any page fetched for either the Hong Kong entity or its mainland parent, Sinolink Securities Co., Ltd. Sinolink Securities scores 5.4 out of 10.
What we saw
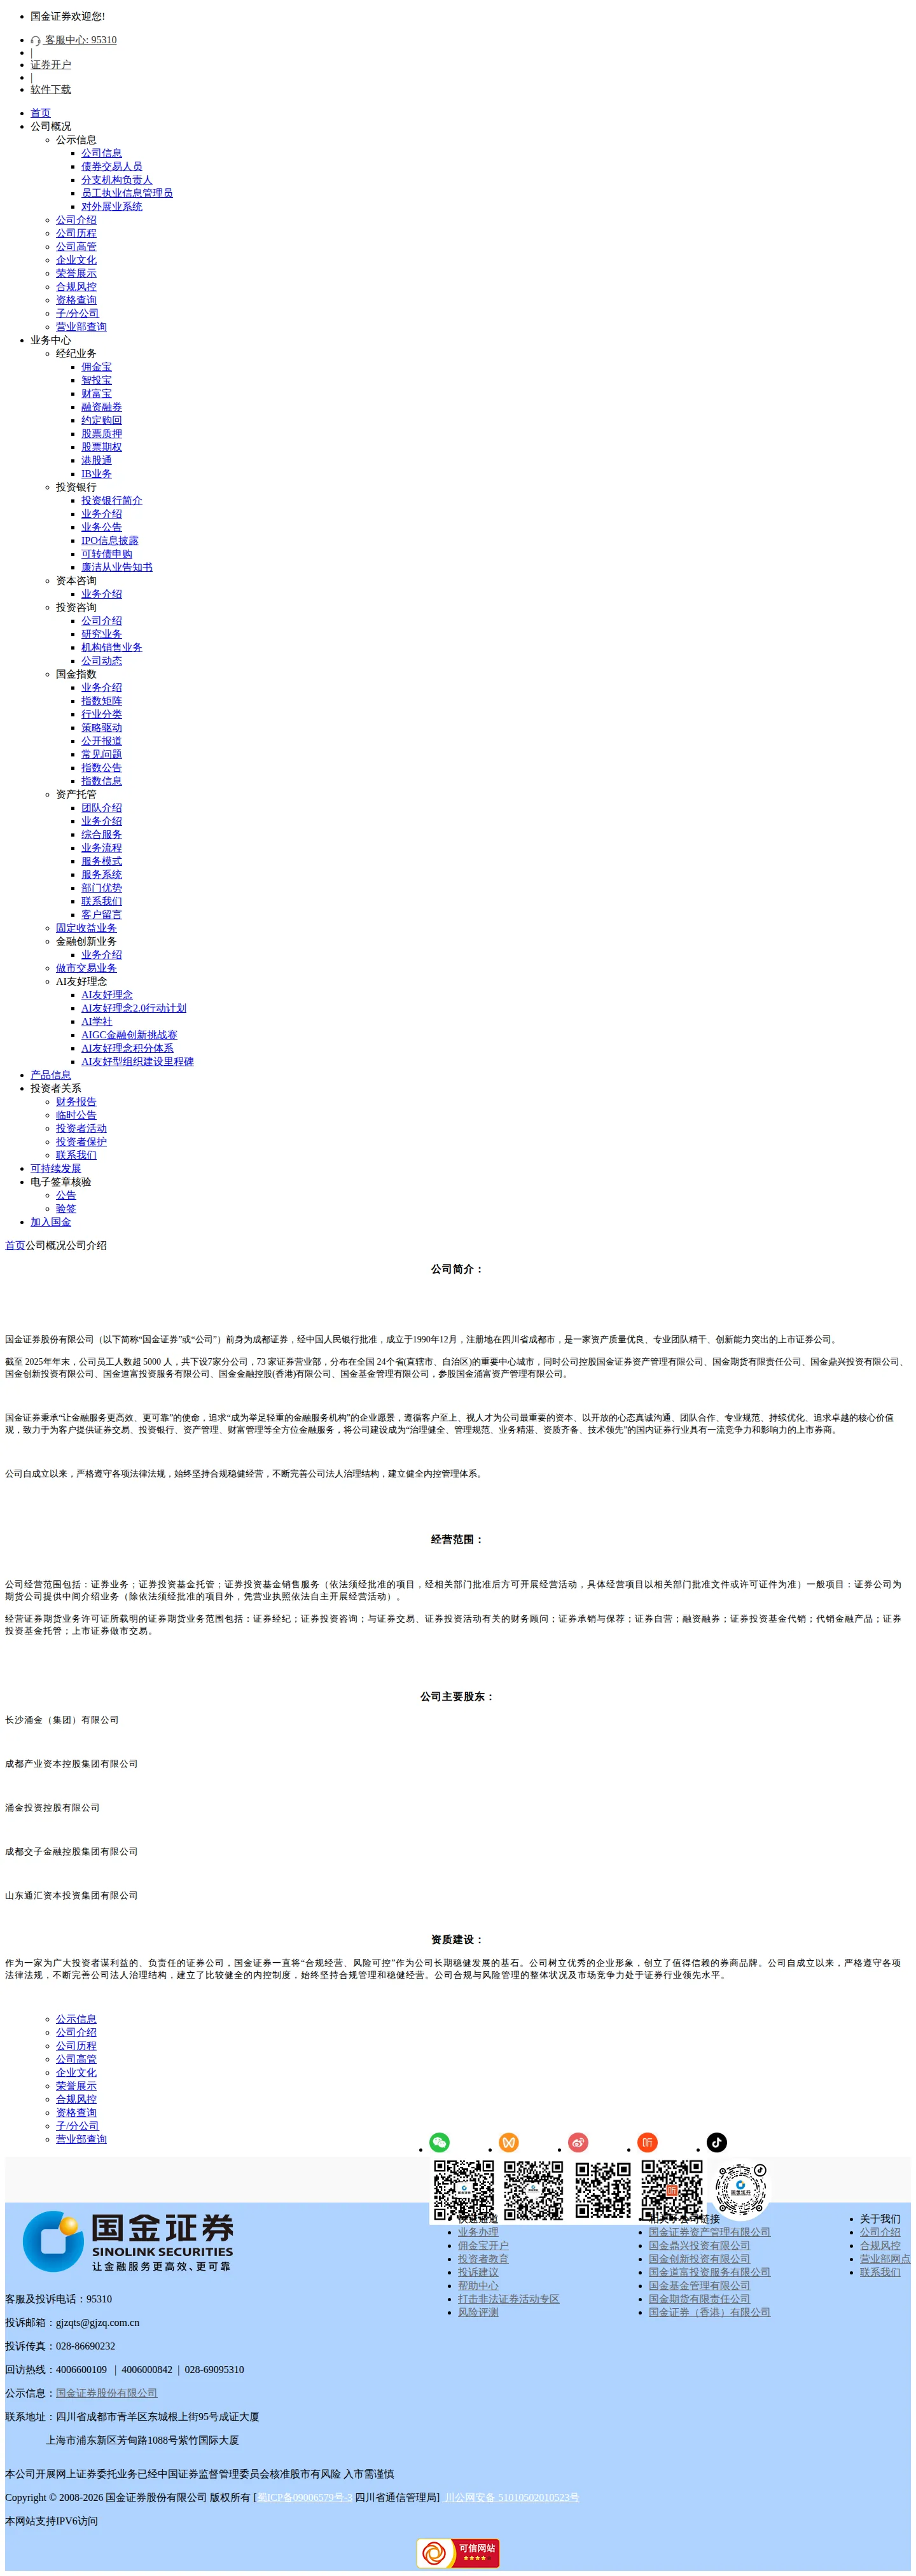
Pages captured from Sinolink Securities’s own site when this review was written. Brokers change their terms; these are what we read.
Score history
Recomputed daily; every move is on the record. The current score is always the latest row.
| Date | Score | Move |
|---|---|---|
| 2026-10-12 | 5.4 | ▲ |
| 2026-07-25 | 4.2 | ▼ |
| 2026-07-18 | 4.4 | ▼ |
| 2026-07-11 | 4.6 | · |
FAQ
Is Sinolink Securities regulated?
Its Hong Kong entity holds SFC licence AAI195, confirmed on the register. The mainland parent is on the CSRC’s directory of securities companies dated July 2026, which carries no licence numbers.
What does Sinolink Securities charge?
No published cost of trading was found on the broker’s own pages or documents.
What trading platforms does Sinolink Securities offer?
Its own mobile app, its own Windows client, and the IFC Hong Kong Securities Trading Software for desktop and mobile.
Can retail investors use Sinolink Securities?
Its SFC Type 9 licence carries a professional-investor-only condition.
What protection do clients have if something goes wrong?
The SFC compensation scheme covers clients up to 500,000 HKD, but adjudicator decisions bind the firm while the claimant pays to bring a complaint. There is no negative-balance protection requirement under this regulator.
What do customer reviews say about Sinolink Securities?
A blended 4.80 stars across 24,291 ratings.
How this review works
Track Sinolink Securities live: score moves and red notices, in your pocket.