STOCK · CHECKED 10 OCT 2026
BOCOM review.
Hong Kong-linked stock broker with one confirmed SFC licence
RISKY
OUT OF 10
BOCOM is a stock broker whose BOCOM International brand holds one confirmed active licence from Hong Kong's SFC (APJ121). Its website ICP filing is a registration, not a trading licence, and no cost of trading is published anywhere on its own pages. The biggest reservation is that fee transparency is absent and only one regulator is verified, while online reviews are thin at 3.18 stars from just 5 ratings.
Each criterion is scored 1 to 10 from primary sources. The overall score is their unweighted mean. How scoring works.
| Founded | 1912 |
|---|---|
| Headquarters | HK |
| Minimum deposit | HKD 10,000+ |
| Account opening | 1-3 |
- Licensed by Hong Kong's SFC under licence APJ121 for the BOCOM International brand
- Offers a proprietary desktop platform integrated with Hong Kong Exchange systems
- Provides both a web platform and a mobile app
- Reachable by live chat
- No published trading fees or cost schedule on the broker's own pages
- Only one confirmed active regulator, no second verified licence
- ICP filing is a website registration, not a trading licence
- Only 3.18 stars across just 5 ratings online
- Live chat appears to be the only listed support channel
Overview
TrueBroker is a free broker safety checker, and this page is our review of BOCOM International, scored 4.8 out of 10 across regulation, fees, platform, support and reviews.
The brand sits under BOCOM International Holdings Company Limited, based in Hong Kong SAR, with Bank of Communications Co., Ltd. (established 1908) as the parent company. The site’s Chinese-language copyright notice names the operating entity as BOCOM International Holdings Company Limited (交銀國際控股有限公司). The single thing worth knowing before anything else: this is a Hong Kong securities and investment-banking house serving institutional and qualified investors, not a retail forex or CFD broker. The earlier review we are updating flagged that any site trading under the BOCOM name offering MetaTrader 4/5 or leverage around 1:500 is describing an impersonator, and a firsthand fetch of the Chinese-language corporate site at bocomgroup.com shows sections for corporate finance, securities & futures, asset management, investment & financing, research and investor relations, with nothing about forex, MT4/MT5 or leverage products.
Why the score moved
Our previous score for BOCOM International was 3.5 out of 10; this review scores it 4.8. That is a change to our own assessment, not a claim that the firm has changed, and the current criteria weightings and evidence explain the move. Regulation sits at 5.6, reflecting an public register check register check that confirmed an active licence with no public disciplinary record, set against a second licence number we could not fully read and two other cited numbers we could not check at all. Fees sit at 2, reflecting that no fee schedule turned up on any page we fetched. Platform sits at 6.6, on the strength of a proprietary system available across mobile, web and desktop, offset by no automated-trading or API support. Support sits at 5.3, based on a single live-chat channel found in the site footer. Reviews sit at 4.5.
What the SFC register shows for BOCOM International
We searched the SFC (Hong Kong Securities and Futures Commission) register directly, running a positive control against a firm known to be listed first so an empty result would mean absence rather than a broken search. CE reference APJ 121 on the SFC Public Register of Licensed Persons and Registered Institutions is held by BOCOM International Securities Limited, a company whose name begins with the name the earlier review used (“BOCOM International”) but which is a specific licensed subsidiary rather than the umbrella brand. It is licensed for Type 1, Type 2, Type 4 and Type 5 activities (Dealing in Securities; Dealing in Futures Contracts; Advising on Securities; Advising on Futures Contracts), each shown as active, and the register records no public disciplinary action against it.
CE reference BGZ962 on the same register is held by a different subsidiary, BOCOM International Futures Limited. The earlier review described this licence as revoked; checking the register ourselves, we could not read any regulated activities listed against it, and the register itself records no public disciplinary action against it, so we cannot confirm the earlier review’s “revoked” characterization from what we checked. Of two further numbers cited by the earlier review, the “Various” CSRC (mainland China) licence finds no match on the CSRC’s 2020 list of securities companies, which names no BOCOM company, and the ICP filing (沪ICP备18022608号-1) shown in the site footer is a website registration we did not check. We also searched 1441 warning-list entries mirrored from CySEC, the FCA and the Mauritius FSC, and BOCOM International’s name matches none of them.
What BOCOM International offers
The earlier review’s account breakdown lists a Cash Account (HKD 10,000+ minimum, no leverage, Hong Kong market only, T+2 settlement), a Margin Account (HKD 100,000+, leverage limited by SFC), a Stock Connect account (HKD 500,000+, Hong Kong plus China A-shares access) and a negotiable Institutional tier. It also describes a single proprietary trading system, available on iOS, Android, web and desktop, with basic charting, standard equity order types, and no automated trading, expert-advisor or programming-API support, and states plainly that MT4 and MT5 are not offered. Instrument coverage in that same source spans Hong Kong equities and H-shares, China A-shares via Stock Connect for qualified investors, fixed income aimed at institutional clients, selective IPO subscriptions, structured products for professional clients, and a range of mutual funds. The same source describes account opening as requiring qualified-investor or minimum-asset criteria, KYC/AML screening and compliance approval taking five to ten business days, with no third-party deposits accepted.
What we could not verify on BOCOM International’s own site
Pages we fetched for legal terms, terms and conditions, about, fees, accounts, contact, risk disclosure, markets and platforms came back empty or as generic shells across the UK, UAE, Indonesian and Australian exits we checked, so we could not independently verify contract terms or a fee schedule from the firm’s own pages during this fetch.
Overview Table
| Headquarters | Hong Kong SAR |
| Established | Not stated (parent Bank of Communications founded 1908) |
| Countries Served | Not stated |
| Regulated By | SFC (Hong Kong Securities and Futures Commission) |
| Minimum Deposit | HKD 10,000+ (Cash Account tier) |
| Maximum Leverage | Not stated |
| Total Instruments | Not stated |
| Platforms | BOCOM proprietary trading system (no MT4/MT5) |
| Customer Support | Live chat / online customer-service widget |
| Languages | Not stated |
Facts List
- Operating entity is BOCOM International Holdings Company Limited, Hong Kong SAR, parent Bank of Communications Co., Ltd. (est. 1908).
- Site copyright footer names the Chinese corporate entity as BOCOM International Holdings Company Limited (交銀國際控股有限公司).
- SFC CE reference APJ 121 is held by BOCOM International Securities Limited, licensed for Types 1, 2, 4 and 5, all shown active, no public disciplinary action on record.
- SFC CE reference BGZ962 is held by a separate subsidiary, BOCOM International Futures Limited; we could not read its regulated activities, and the register shows no public disciplinary action against it.
- The earlier review described BGZ962 as revoked; our own SFC check did not confirm that status.
- The CSRC’s 2020 list of securities companies names no BOCOM company, so the “Various” CSRC licence claim is not borne out there, and the ICP filing (沪ICP备18022608号-1) is unchecked.
- A search of 1441 warning-list entries mirrored from CySEC, the FCA and the Mauritius FSC returned no match for BOCOM International.
- Earlier review lists four account tiers: Cash (HKD 10,000+), Margin (HKD 100,000+), Stock Connect (HKD 500,000+) and negotiable Institutional.
- Earlier review describes a single proprietary platform on mobile, web and desktop, with no MT4/MT5 and no automated-trading or API support.
- Pages fetched for legal terms, fees, accounts and risk disclosure came back empty or as generic shells across four country exits checked.
- A firsthand fetch of bocomgroup.com’s Chinese-language site shows corporate finance, securities & futures, asset management, investment & financing, research and investor-relations sections, with no mention of forex, MT4/MT5 or leverage products.
Key Takeaways
I reviewed the passage and confirmed that 在线客服 is the only foreign-script term present, and it’s already formatted correctly as “online customer service (在线客服)”. No changes needed.
“`html
Our previous score for BOCOM was 3.5/10. This review puts it at 4.8/10. The move comes from our assessment against a fuller evidence set, not from anything changing at the firm: the SFC register shows an active licence and a securities platform that actually functions for its stated purpose, which lifts regulation and platform above where the earlier pass left them, while the fee and disclosure picture stayed thin enough to hold the fees score down at 2.
What the SFC register actually shows for BOCOM
- CE reference APJ 121 on the Hong Kong SFC Public Register of Licensed Persons and Registered Institutions is held by BOCOM International Securities Limited, licensed for Type 1, Type 2, Type 4 and Type 5 (Dealing in Securities, Dealing in Futures Contracts, Advising on Securities, Advising on Futures Contracts), each shown as active, with no public disciplinary action recorded against it.
- CE reference BGZ962 on the same register is held by a related entity, BOCOM International Futures Limited. The register lists no regulated activities we could read for it, and it too carries no public disciplinary action. The earlier review said this licence was revoked. The register entry does not use that word, but it lists no current regulated activities for BGZ962, which fits a licence that is no longer in force; we could not confirm it as active.
- The claim for “CSRC (mainland China)” gives no licence type or number, and the CSRC’s own 2020 list of securities companies names no BOCOM company. The same goes for the China ICP filing number shown in the site footer, which is a website-registration record, not a financial-services licence.
- We searched 1,441 warning-list entries mirrored from CYSEC, the FCA and the FSC Mauritius, running a positive control on the SFC checks first so an empty result means absence rather than a broken search. BOCOM appears on none of them. That is a clean result across the lists we mirror, not a clearance from every regulator worldwide.
Who can actually open an account, and what it costs
- The earlier review’s account tiers run from a Cash Account at HKD 10,000+ (no leverage, Hong Kong market only, T+2 settlement) through a Margin Account at HKD 100,000+, a Stock Connect account at HKD 500,000+ giving access to China A-shares, up to a negotiable Institutional tier. None of these figures come from a page we fetched ourselves; they carry forward from the prior review.
- Account opening is described as requiring qualified-investor or minimum-asset criteria, full KYC/AML screening and compliance approval running 5 to 10 business days, which places this firm outside general retail access from the start.
- We found no fee schedule on any page we fetched. Multiple pages we probed for legal terms, fees, accounts, contact and risk disclosure came back empty or as generic shells repeated across the UK, UAE, Indonesian and Australian exits, so spreads, commissions and account charges are not things we can name a source for.
- Funding is bank wire only: local wire in 1 to 2 days, international wire in 3 to 5 days with higher fees and currency conversion, plus cheque in 5 to 7 days. Credit card, e-wallets and cryptocurrency are all stated as unsupported for deposit or withdrawal, and no third-party deposits are accepted, only wires from accounts verified as belonging to the client.
What BOCOM’s platform is, and what it is not
- The platform is described as a securities-focused proprietary system for Hong Kong and China stock trading, available on iOS, Android, web and desktop, with basic charting, standard equity order types, no automated trading or EA support, and limited or no programming API. It does not offer MT4 or MT5.
- First-hand access to the Chinese-language bocomgroup.com site corroborates this independent of the material from our earlier review: the rendered sections cover corporate finance, securities and futures, asset management, investment and financing, research and investor relations, with no mention of forex, MT4/MT5 or leverage products anywhere on the page.
- The site repeats a warning, carried from the earlier review, that any site offering retail forex or CFD trading, MetaTrader platforms or high leverage such as 1:500 under the BOCOM name is not this firm. The SFC-licensed entity is a securities and investment-banking business serving institutional and qualified investors, not a retail forex broker.
Support and what happens when equity runs low
- The only support channel we could confirm first-hand is a live-chat widget shown in the site footer, labelled online customer service (在线客服). No phone, email or ticketing channel appears in what we fetched.
- There is no forex-style negative balance protection here. Margin accounts are subject to margin calls and forced liquidation when equity falls below maintenance requirements, and cash accounts cannot go negative because purchases require full payment upfront. We found no published margin-call percentage or stop-out level to go with that mechanism.
- No restricted-country list appears on the homepage, legal, terms or legal-documents pages as checked through an Indonesian exit. An earlier version of this material carried a list of countries presented as this broker’s policy, but it could not be tied to anything the broker itself publishes, and has been dropped here rather than repeated.
Licenses & Regulation
BOCOM International runs on a mixed regulatory record, and the register shows exactly why this review moves from 3.5/10 to 4.8/10 while the fee, platform and support picture stays largely unchanged. The regulation criterion is the one that moved: we now hold two direct SFC register lookups on the CE numbers this firm has published, and a warning-list search across 1,441 mirrored entries came back clean. That is more than the previous review had to work with, and it is the basis for the new figure, not any change in the firm itself.
What the SFC register actually shows for BOCOM International
We searched the Hong Kong SFC Public Register of Licensed Persons and Registered Institutions directly, running a positive control against a known-listed firm first so that any gap we found would mean something. CE reference APJ121 is held by BOCOM International Securities Limited, a company name that begins with “BOCOM International” but is not the same as the brand the claim names. The register lists it as licensed, and active, for Type 1, Type 2, Type 4 and Type 5 activities: Dealing in Securities, Dealing in Futures Contracts, Advising on Securities, and Advising on Futures Contracts. The register records no public disciplinary action against this licence.
A second CE reference, BGZ962, is held by a related but distinct entity, BOCOM International Futures Limited, again a company whose name begins with “BOCOM International” rather than an exact match to the brand. For this one the register entry we pulled lists no regulated activities we could read, and again records no public disciplinary action. Our earlier review described a licence under this same number as revoked; that characterization comes from that earlier review, not from what our own register lookup returned, and we flag the difference rather than pick a side.
Two numbers named elsewhere in the material we hold, a CSRC filing said to cover mainland China and a China ICP website registration, Shanghai ICP Filing No. 18022608-1 (沪ICP备18022608号-1), tied to the site’s copyright holder BOCOM International Holdings Company Limited (交銀國際控股有限公司) in the footer, were checked as far as public sources allow. The CSRC’s list of securities companies in its 2020 annual report names no BOCOM company, so the CSRC claim is not borne out there, though it gives no licence type and a CSRC authorisation of another kind cannot be ruled out. We hold no register for China’s ICP filings, and the ICP number is a website-hosting registration, not a financial-services licence.
Entity structure and what it means for a prospective client
The material we hold names BOCOM International Holdings Company Limited as the investment-banking and securities-trading arm of Bank of Communications Co., Ltd. (established 1908), with the operating entity shown in the site’s own copyright notice as BOCOM International Holdings Company Limited. Neither of the two SFC CE numbers we checked is licensed to that holding company by name; both sit one level down, at the securities and futures operating subsidiaries. That is a normal structure for a banking group of this size, but it means a client dealing with “BOCOM International” as a brand is contracting with one of two specifically licensed subsidiaries, not the holding company itself, and the CE number on any account paperwork is the thing worth checking against the register rather than the group name.
What the warning-list search adds
We searched 1,441 warning-list entries mirrored from CySEC, the FCA and the FSC Mauritius, and BOCOM International does not appear on any of them. That is a genuine finding this review can point to that the earlier version could not, though it only covers the three regulators we mirror; it says nothing about any other authority’s warning list.
What we could not check
The earlier review’s account of a revoked SFC licence, of CSRC coverage in mainland China, and of the accounts, fees and platform detail summarized elsewhere in this write-up all came to us from that earlier published review rather than from a page we fetched ourselves. We also note, separately from the earlier review, that the material flags a broader problem for anyone searching this brand: sites offering retail forex or CFD trading, MetaTrader 4/5, or leverage up to 1:500 under the BOCOM name are described in that same material from our earlier review as impersonators, since the SFC-licensed entities we confirmed are dealing and advising firms for securities and futures, not retail forex brokers. A reader checking any site claiming to be BOCOM should match the CE number it quotes against APJ121 or BGZ962 on the SFC register before doing anything else.
How to Trade
What actually gets traded here
An earlier review of this broker that we are restating described BOCOM International’s product range as built around Hong Kong securities rather than retail speculation: direct trading in HK stocks, H-shares and red chips; China A-shares in Shanghai and Shenzhen through Stock Connect, restricted to qualified investors and carrying higher minimum thresholds; government and corporate bonds aimed at institutional clients with a substantial minimum investment; selective, case-by-case subscription to new listings through its IPO service; structured notes and warrants offered only to professional clients in limited supply; and a selection of mutual funds where the minimum varies fund by fund. None of that earlier material, and nothing we fetched ourselves, describes retail forex or CFD trading, and the same earlier review is explicit that any site offering BOCOM-branded forex trading, MetaTrader 4 or 5, or leverage around 1:500 is describing an impersonator, not this firm.
Account tiers at BOCOM International
The tier structure reported in that same earlier review runs on rising minimum deposits rather than a single onboarding flow. A Cash Account starts at HKD 10,000, carries no leverage, is limited to the Hong Kong market, settles on T+2, and comes with basic research access and no dedicated relationship manager. A Margin Account requires HKD 100,000 or more, with leverage capped by SFC rules, variable interest charged on the margin drawn, enhanced research access, and the same T+2 settlement. A Stock Connect account needs HKD 500,000 or more and adds China A-share access to the Hong Kong market, enhanced research, a dedicated relationship manager “sometimes,” a specialised platform, and settlement running T+1 or T+2 depending on the market. An Institutional tier sits above all of these with a negotiable minimum, customised leverage, global market access, a full research suite, a dedicated relationship manager and multiple platform options.
Getting into any of these accounts is not a same-day process. The same source describes account opening as requiring qualified-investor or minimum-asset criteria to be met, full KYC/AML screening, and compliance approval taking five to ten business days. Funding is similarly restricted: no third-party deposits are accepted, and money has to move by bank wire from an account already verified as belonging to the client.
The trading system itself
The platform described in that earlier review is a proprietary system built for securities trading rather than for retail derivatives: available on iOS, Android, web and desktop, with standard equity order types and basic charting, but no support for automated trading or expert advisors, and limited or no programming API. It is stated outright as not offering MetaTrader 4 or MetaTrader 5. We independently fetched the rendered bocomgroup.com corporate site and found it organised around corporate finance, securities and futures, asset management, investment and financing, research and investor relations, with no mention anywhere of forex, MT4/MT5 or leverage products, which is consistent with the earlier review’s description of an institutional securities platform rather than a retail trading terminal.
Margin calls instead of negative-balance protection
The earlier review also flags a distinction worth stating plainly: the negative-balance protection that retail forex and CFD brokers advertise is not a concept that applies to how BOCOM International’s securities accounts work. On a margin account, the mechanism that limits a client’s downside is a margin call followed by forced liquidation once equity falls below the maintenance requirement, and no margin-call percentage or stop-out level is given in what we have. A cash account cannot go negative for a different reason entirely, according to that same source: purchases require full payment upfront, so there is no borrowed position to move against the client.
What we could not check on BOCOM International’s own site
When we tried to pull the fee schedule, contract terms and risk disclosure directly, the result was thin. Pages for legal terms, terms and conditions, fees, accounts, contact, risk disclosure, markets and platforms came back empty or unrendered, or as generic shells identical across the UK, UAE, Indonesian and Australian exits we probed. That means the account and instrument detail above rests on the earlier review’s reporting rather than on contract language we read ourselves, and it is a real gap: a firm handling margin accounts and forced liquidation is exactly the case where seeing the actual maintenance-margin and stop-out terms in writing would matter.
Our previous review of this broker scored it 3.5 out of 10 overall; this review scores the platform component at 6.6 and lands at 4.8 overall. That shift is this review’s own criteria and evidence being applied fresh, not a claim that BOCOM International’s trading setup has changed: the account-tier detail above and the confirmation that the trading system is a proprietary equities platform, not a retail MT4/MT5 setup, are what this review’s platform figure is built on.
Account Types
Bocom International sells access by client type, not by a menu of retail tiers. The four categories the earlier review reported are a cash account, a margin account, a Stock Connect account and an institutional account, and each buys a different level of market access rather than a different discount on the same product.
What the four account types cover
The Cash Account carries a minimum deposit of HKD 10,000 and above, according to the earlier review, and comes with no leverage, Hong Kong market access only, basic research access, no dedicated relationship manager and standard T+2 settlement. The Margin Account steps the minimum up to HKD 100,000 and above, with leverage limited by the SFC, variable interest charged on margin, enhanced research access, still no dedicated relationship manager, and the same T+2 settlement. The Stock Connect account requires HKD 500,000 and above, and buys access to Hong Kong shares plus China A shares, enhanced research, a dedicated relationship manager on some accounts, a specialized platform, and settlement quoted as T+1 or T+2 depending on the market. The Institutional account has no fixed minimum, listed as negotiable, and covers customized leverage, global market access, a fuller research offering, a dedicated relationship manager and a choice of platform options.
None of the four tiers is described in the evidence as carrying a published fee schedule. The pages our review process fetched from Bocom’s own site, across the gb, ae, id and au exits, returned empty or unrendered content on the fee, accounts, terms and risk disclosure pages, so no commission table, spread figure or account-keeping charge can be attributed to the firm here.
Who can actually open one
Per the earlier review, opening any of these accounts requires meeting qualified investor or minimum asset criteria, passing KYC and AML screening, and clearing compliance approval, a process quoted at five to ten business days. That review also reported that Bocom does not accept third party deposits, funds must arrive by bank wire from an account verified as belonging to the client, and that this firm serves institutional and qualified investors rather than general retail clients. The instruments on offer, per that same review, are equities (Hong Kong stocks, H shares and red chips), China A shares through Stock Connect for qualified investors at higher minimums, fixed income aimed at institutional buyers, selective IPO subscriptions, structured products restricted to professional clients, and a limited set of mutual funds.
What isn’t on the menu
The earlier review’s account structure has no forex or CFD tier, no MetaTrader 4 or 5 option and no high leverage such as 1:500. That review, and the site content our review process fetched directly from bocomgroup.com, both describe an institutional securities and investment banking business built around corporate finance, securities and futures, asset management, investment and financing, research and investor relations, with nothing on the fetched pages naming forex, MT4, MT5 or leveraged retail products. The earlier review’s framing goes further and treats any site marketing “Bocom” forex trading with high leverage as an impersonation of this firm, since the licensed entity, BOCOM International Securities Limited, holds Hong Kong SFC reference APJ 121 for dealing in and advising on securities and futures contracts, not a retail leverage product.
On the protection side, the earlier review noted that the negative balance protection guarantee marketed by forex brokers has no equivalent here: margin accounts are instead subject to margin calls and forced liquidation once equity falls below the maintenance requirement, and cash accounts cannot go negative because purchases require full payment upfront. No margin call percentage or stop out level is given in what we hold.
This review scores account_types related criteria as part of an overall 4.8 out of 10, up from this catalogue’s previous 3.5. The change reflects a rescoring against current evidence rather than any change at the firm: the SFC register confirms an active licence, APJ 121, held by BOCOM International Securities Limited for dealing in and advising on securities and futures, which supports treating the tiered account structure above as tied to a real regulated entity even though the fee and terms pages we tried to fetch came back empty.
Negative Balance Protection
BOCOM International markets itself, and is licensed by the Hong Kong SFC, as a securities and futures dealer, not a retail forex or CFD broker. That distinction matters for this section, because “negative balance protection” is a term that comes from leveraged forex/CFD trading, and the evidence we hold says explicitly that it does not describe how this firm works.
Why negative balance protection does not apply here
Our earlier review reported that BOCOM International does not offer retail forex or CFD trading, MetaTrader 4/5, or high leverage such as 1:500, and that any site using the BOCOM name to offer those products is an impersonator, not the SFC-licensed entity. We cannot verify that description first-hand, since it comes from our earlier review rather than a page we fetched, but the mechanism it points to is consistent with what an SFC-licensed securities dealer typically runs: margin against a securities position, not the fixed-leverage forex model that negative balance protection was built to backstop. So there is no NBP policy, guaranteed cap, or promotional you can’t lose more than you deposit claim to report, because that product category is not what this firm sells.
How the four BOCOM account tiers actually limit loss
Our earlier review’s account breakdown gives four tiers, each with a different loss-exposure profile:
- Cash Account (minimum HKD 10,000): no leverage. Purchases require full upfront payment, so a position cannot go into deficit the way a leveraged one can.
- Margin Account (minimum HKD 100,000): leverage described as “limited by SFC” with variable interest charged on the margin borrowed. This is the tier where loss beyond the client’s deposit is actually possible.
- Stock Connect (minimum HKD 500,000): no leverage, giving access to Hong Kong shares plus China A-shares.
- Institutional (deposit negotiable): “customized leverage,” terms set case by case.
Only the Margin and Institutional tiers carry leverage at all, and for both, our earlier review reports that protection comes from margin-call and forced-liquidation mechanics rather than from a published NBP guarantee: if account equity falls below the maintenance requirement, the firm issues a margin call, and unmet calls lead to forced liquidation of the position. We do not have the actual margin-call percentage, the stop-out level, or a maintenance-requirement figure from any document the firm publishes; our earlier review references the mechanism but not the numbers, and we did not fetch a page that stated them.
What we could not check on BOCOM’s own site
We attempted to pull BOCOM’s own legal terms, risk-disclosure, fees, and account pages across several country exits (UK, UAE, Indonesia, Australia), and the pages returned were empty, unrendered, or generic shells identical across exits. That means none of the margin-call thresholds, liquidation triggers, or account agreement language that would normally carry this section could be independently confirmed from the firm’s own published documents. The one piece of first-hand corroboration we do hold is the rendered bocomgroup.com site, which shows sections for corporate finance, securities and futures, asset management, investment and financing, research, and investor relations, with no forex, MT4/MT5, or leverage marketing present. That is consistent with our earlier review’s framing of the firm as an institutional securities house, but it is not the same as reading a margin agreement.
A gap the SFC register does not fill
The Hong Kong SFC Public Register of Licensed Persons and Registered Institutions confirms CE reference APJ121 is held by BOCOM International Securities Limited, active for Type 1, Type 2, Type 4 and Type 5 activities (dealing in and advising on securities and futures contracts), with no public disciplinary action recorded against it. A second CE reference, BGZ962, is held by BOCOM International Futures Limited, though the register did not show us any regulated activities against that entry, and again no disciplinary action is recorded. The SFC register does not itself set out margin-call percentages or liquidation triggers; those are contractual terms the firm would publish in its own client agreement, and we did not locate that document in this fetch. We also checked this firm against 1,441 warning-list entries mirrored from CYSEC, the FCA and the FSC Mauritius, running a positive control against two known-listed firms first so an empty result means absence rather than a broken search; BOCOM does not appear on any of the three lists, though that check covers only those regulators, not the SFC or CSRC.
This review scores negative balance and loss-limit exposure as part of an overall move from 3.5/10 to 4.8/10. The regulation score of 5.6 reflects a confirmed, active SFC entity alongside a second CE reference the register shows with no readable activities, plus a CSRC claim that the regulator’s 2020 list of securities companies does not bear out and a China ICP filing we could not check. The fees score of 2 reflects that no fee schedule, margin-call percentage, or liquidation-trigger figure was recoverable from BOCOM’s own pages during this fetch. This is our assessment being rerun against a different criteria set and a fresh fetch, not a change in what the firm does.
Trading Instruments
BOCOM International sits on the securities side of Bank of Communications’ investment banking arm, and the instrument list reflects that split. Our earlier review lists Hong Kong equities (HK stocks, H-shares and Red chips) as directly tradable, China A-shares available through Stock Connect for qualified investors at higher minimum thresholds, government and corporate bonds aimed at institutional clients with a substantial minimum investment, selective IPO subscriptions offered case-by-case, structured products such as notes and warrants restricted to professional clients, and a range of mutual funds with minimums that vary by fund. None of that is forex, and none of it is a CFD.
No forex, no MT4/MT5, whatever the impersonators say
The earlier review’s central point about this firm’s asset list is what it does not contain: no retail forex or CFD trading, no MetaTrader 4 or 5, no high leverage such as 1:500. Any site offering those under the BOCOM name is flagged in that review as an impersonator, and the SFC register confirms why the distinction matters here. CE reference APJ121 on the Hong Kong SFC Public Register of Licensed Persons and Registered Institutions is held by BOCOM International Securities Limited, licensed for Type 1, Type 2, Type 4 and Type 5 activities, meaning dealing in securities, dealing in futures contracts, advising on securities and advising on futures contracts, each shown as active. That is a securities and futures dealer’s licence, not a retail leveraged-trading permit, and it lines up with an instrument list built around equities, bonds, IPOs, structured products and funds rather than margined currency pairs.
A second SFC record, CE reference BGZ962, is held by BOCOM International Futures Limited. The register lists no regulated activities we could read for that entry, and it records no public disciplinary action against either company. The earlier review separately describes a licence numbered BGZ962 as revoked; our own SFC search did not surface that status one way or the other, so what we can confirm is the entity match and the absence of any disciplinary record on the register, not the revocation claim itself.
Access is gated by account tier, not by product menu
What a client can actually trade appears to depend more on which account they qualify for than on a shared product catalogue. The earlier review’s account breakdown runs from a Cash Account at HKD 10,000 and up, covering Hong Kong market access only with no leverage, up through a Margin Account at HKD 100,000 and up with leverage limited by the SFC, a Stock Connect account at HKD 500,000 and up adding China A-share access, and an Institutional tier with a negotiable minimum offering customized leverage and global market access. Structured products and fixed income, per that same review, are aimed at institutional and professional clients specifically, and IPO subscriptions are described as selective rather than open to every account holder. Read together, the instrument list published for BOCOM International is less a single menu and more a set of access tiers stacked on top of each other, with the entry-level Cash Account seeing a fraction of what the Institutional tier can reach.
What we could not check on BOCOM International’s own pages
We were not able to pull a fee schedule, contract terms, or a markets/instruments page directly from the firm’s own site during this fetch; pages probed for legal terms, fees, accounts, risk disclosure and platforms across several exits came back empty or as generic shells. The one piece of first-hand corroboration we do have is the rendered content from bocomgroup.com, which shows sections for corporate finance, securities and futures, asset management, investment and financing, research, and investor relations, with no mention of forex, MT4/MT5 or leverage products. That matches the shape of the asset list above, but it is a site-structure check, not a fee sheet or a contract we read.
Settlement and negative balance protection work differently here
The earlier review notes that negative balance protection, a feature forex brokers market, does not apply to BOCOM’s securities business. Margin accounts are instead subject to margin calls and forced liquidation when equity falls below maintenance requirements, and cash accounts cannot go negative because purchases require full payment upfront. Settlement on the Cash and Margin accounts is T+2; Stock Connect is described as T+1/T+2 depending on the leg of the trade. No margin-call percentage or stop-out level is given in what we hold.
Our previous score for this broker was 3.5 out of 10; this review scores it 4.8. The regulation criterion now sits at 5.6, which fits an active SFC entity licence for four dealing and advising activities against a register that shows no public disciplinary action, set alongside a second SFC entry we could not fully read, a CSRC claim the regulator’s own 2020 list of securities companies does not bear out, and a China ICP filing we could not check. Fees sit at 2, reflecting that no fee schedule could be pulled from the firm’s own pages in this pass. This is our assessment against current evidence, not a change in the firm.
Education & Analysis
BOCOM International’s own site structure, fetched directly from bocomgroup.com, shows sections for corporate finance, securities and futures, asset management, investment and financing, research, and investor relations. Nothing in that live page mentions forex, MetaTrader 4 or 5, or leverage products, which matches what our earlier review found when it looked at the firm’s trading systems specifically.
What BOCOM International actually runs
Our earlier review describes a single proprietary trading system rather than a licensed third-party platform. It’s built for Hong Kong and China stock trading, available on mobile through iOS and Android apps, plus web and desktop access. The same source is explicit about what isn’t there: no automated trading or Expert Advisor support, only basic charting, and a limited or absent programming API. Order types are described as standard equity orders, nothing built for derivatives or algorithmic strategies.
Our earlier review is also explicit on a point that matters for anyone who found this firm while searching for a retail broker: BOCOM International offers neither MetaTrader 4 nor MetaTrader 5, which sets it apart from the retail forex brokers such a search usually turns up. That’s a direct statement, not an inference from a missing features page, and it’s worth taking seriously given the same material warns that any site offering MT4/MT5 or high leverage such as 1:500 under the BOCOM name should be treated as an impersonator rather than the SFC-licensed entity.
Charting and research tools
Charting is described in our earlier review as basic. There’s no breakdown of indicator counts, drawing tools, or timeframe options in what reached us, and we did not fetch a platforms or features page from the firm’s own site that could fill that in. What we can say about research access comes from the account tier notes in the same material from our earlier review: the Cash Account carries “basic research access,” the Margin Account has “enhanced research access,” the Stock Connect tier again lists “enhanced research,” and only the Institutional tier is described as having a “full research suite.” Beyond those four phrases, nothing in the evidence describes what the research actually consists of.
Why the platform score sits where it does
The platform criterion scores 6.6 out of 10. The evidence supports a firm running a functioning proprietary system across mobile, web and desktop, with tiered account access scaling from basic to institutional research, which is more than a bare-bones offering. But the same evidence caps how far that can go: charting is called basic with no detail on what that means in practice, there’s no automated-trading or API layer for anyone wanting to build their own tools, and multiple pages we tried to fetch directly from the firm’s site for legal terms, fees, accounts, and platform features came back empty or as generic shells duplicated across the UK, UAE, Indonesia and Australia exits we checked. That last point matters here specifically: we could not independently verify the platform description against the firm’s own current documentation, and the fuller picture we do have is second-hand, from the earlier review rather than from a page we read ourselves.
This review’s overall score is 4.8 out of 10, up from a 3.5 we gave this firm previously. On the platform side specifically, that isn’t a claim that BOCOM International changed anything: it’s this review’s assessment run against current evidence, and the SFC register confirms an active licence (APJ 121, held by BOCOM International Securities Limited, covering Type 1, 2, 4 and 5 activities) sitting behind a firm that does at least operate a real multi-device trading system, which is more than a pure shell would offer. The gaps are just as real: no first-hand look at a features or platform page from the firm itself, and no detail beyond a handful of adjectives on what the charting tools can do.
Special Offers
The pages we were able to fetch for this review carry no mention of a promotional offer, a deposit bonus, a fee rebate, or any conditional cashback tied to opening an account. That is not a claim that BOCOM International runs no such thing; it is a report of what our fetch turned up, or rather did not.
What we actually looked at
We probed BOCOM International’s legal terms, terms and conditions, about, fees, accounts, contact, risk disclosure, markets and platforms pages across four exits, Britain, the UAE, Indonesia and Australia. Those pages came back empty, unrendered, or as generic shells identical across exits, so no fee schedule, no accounts page copy, and no promotions page turned up on the crawl. The one rendered page we hold, the Chinese language corporate site at bocomgroup.com, shows sections for corporate finance, securities and futures, asset management, investment and financing, research and investor relations. None of those sections is a promotions or offers page.
An earlier review of this firm, which we are restating rather than quoting since we did not read the underlying documents ourselves, described four account tiers: a Cash Account from HKD 10,000, a Margin Account from HKD 100,000, a Stock Connect account from HKD 500,000, and a negotiable Institutional tier. None of the four is described in that material as carrying a sign up bonus, a deposit match, a fee waiver period, or a referral credit; what is described is minimum deposit and feature access only. That same review reported that opening any account requires meeting qualified investor or minimum asset criteria, full KYC and AML screening, and compliance approval taking five to ten business days, and that BOCOM International will not accept a deposit from a third party, only a bank wire from an account already verified as belonging to the client. A firm that gates entry behind asset thresholds and compliance sign off of that kind is not the shape of a retail broker running deposit bonuses, and the account tiers as described read that way: priced by minimum balance and service level, with no promotional credit mentioned anywhere in that material.
The impersonation warning matters here specifically
The material we hold on this firm places weight on a separate point: sites offering retail forex or CFD trading under the BOCOM name, promising MetaTrader 4 or 5 access or leverage as high as 1:500, are described as fraudulent, since the SFC licensed entity is an institutional securities and investment banking firm, not a retail forex broker. A reader who lands on a page advertising a deposit bonus or a leverage promotion under the BOCOM name should treat that as a reason to check which entity is actually behind the site, not as an offer from BOCOM International.
We searched 1,441 warning list entries mirrored from CySEC, the FCA and the FSC Mauritius, and BOCOM does not appear on any of them. That covers three regulators’ lists, not a worldwide check, but it is a clean result as far as it goes.
Where BOCOM International’s licence stands, and why the score moved
The Hong Kong SFC Public Register of Licensed Persons and Registered Institutions shows CE reference APJ121 held by BOCOM International Securities Limited, active for dealing in securities, dealing in futures contracts, advising on securities and advising on futures contracts, with no public disciplinary action recorded against it. A second reference, BGZ962, is also held by a BOCOM International entity, BOCOM International Futures Limited. An earlier review described this second licence as revoked, though the SFC register itself returned no readable list of regulated activities for it and likewise recorded no public disciplinary action, so that revoked status could not be confirmed from the register directly for this review. The CSRC’s 2020 list of securities companies names no BOCOM company, so the CSRC reference is not borne out there; the China ICP filing number in the firm’s footer is a website registration we did not check.
Our previous review scored this firm 3.5 out of 10. This review scores it 4.8 out of 10. We are restating our own assessment against the evidence above, not reporting any change at the firm itself. The regulation score of 5.6 reflects an active, confirmed SFC licence against a second reference the register did not resolve cleanly. The fees score of 2 reflects that no fee schedule turned up on any page we fetched, leaving nothing to score above the floor. Platform scored 6.6 and support 5.3 on the material available, and reviews scored 4.5. None of those component scores, and nothing gathered for this section, points to a promotional offer of any kind attached to this firm’s accounts.
Opening an Account
Opening an account here is not a self-service, retail-onboarding flow. Per the earlier review of BOCOM International, applicants must meet qualified-investor or minimum-asset criteria before an account is opened at all, and every application goes through what that review calls full KYC/AML screening followed by compliance approval, a process it puts at five to ten business days. The same source is explicit that the account tiers on offer are built for institutional and qualified investors, not for general retail clients.
The account tiers BOCOM International offers
Our earlier review sets out four tiers, each with its own entry point. A Cash Account starts from HKD 10,000, covers Hong Kong market access only, carries no leverage, basic research access, no dedicated relationship manager and T+2 settlement. A Margin Account needs HKD 100,000 or more, carries leverage limited by SFC rules, variable interest on the margin drawn, and enhanced research access, again with no dedicated RM. A Stock Connect account requires HKD 500,000 or more and adds China A-shares alongside Hong Kong stocks, enhanced research, a dedicated RM “sometimes,” and settlement that runs T+1 or T+2 depending on the market. An Institutional tier carries no fixed minimum, described as negotiable, with customized leverage, full research access, a dedicated RM and flexible settlement. On the margin account specifically, our earlier review notes that BOCOM does not pair it with the kind of negative-balance-protection guarantee retail forex brokers advertise; protection instead comes from margin calls and forced liquidation once equity falls under the maintenance requirement, while the Cash Account cannot go negative because purchases require full payment upfront. We take all of these figures from the earlier review rather than from a fee or account page we fetched ourselves: the accounts, fees and terms pages we tried during our own fetch came back empty or as generic shells repeated across the gb, ae, id and au exits we checked, so we could not confirm the minimums first-hand.
Funding an account
Per the same earlier review, BOCOM International does not accept third-party deposits: funds must move by bank wire from an account verified as belonging to the client. Local bank wire is described as the primary channel, taking one to two business days and carrying bank charges. International wire is slower, three to five days, with higher fees and currency conversion involved. Cheque is listed as slower still, five to seven days, with possible fees. Credit card, e-wallets and cryptocurrency are all listed as unsupported for either deposit or withdrawal.
Eligibility differs by product, not just by account tier
Even once an account is open, access to certain products carries its own bar. China A-shares trading through Stock Connect is restricted to qualified investors, per our earlier review, with higher minimum thresholds than plain Hong Kong equity trading. Structured products such as notes and warrants are limited to professional clients. IPO subscription access is described as selective, granted case by case rather than automatically. Fixed income trading is framed as institutional-focused, needing what the review calls a substantial minimum investment. Mutual fund access varies fund by fund, each with its own minimum.
Who is excluded
We looked for a published restricted-country list on BOCOM’s homepage, legal, terms and legal-documents pages, checked from an Indonesian connection on 27 July 2026, and found none there. An earlier version of this material carried a list of excluded countries, including Iran, North Korea, Syria and Cuba, presented as this broker’s own policy, but that list could not be tied to anything BOCOM actually publishes, so we have dropped it rather than repeat an unsourced claim. What we can say is that the pages we checked carried no restricted-country list; we cannot say from that whether restrictions exist, since we did not find and cannot cite a page stating either way.
Separately, both the live bocomgroup.com site content we fetched and our earlier review stress that BOCOM International does not run retail forex or CFD trading, does not offer MetaTrader 4 or 5, and does not offer the high leverage, up to 1:500, associated with retail FX brokers; any site offering those products under the BOCOM name is flagged as an impersonator rather than this firm. Anyone opening a retail forex account under the BOCOM brand is, on this evidence, dealing with an entity other than the one CE reference APJ 121 covers on the Hong Kong SFC Public Register of Licensed Persons and Registered Institutions.
Deposits & Withdrawals
BOCOM International’s own site did not give us a fee schedule to check: probes of its accounts, fees and terms pages during this fetch came back empty or as generic shells repeated across the gb, ae, id and au exits, so what follows on cost is drawn largely from our earlier review, not from a page we read ourselves this time. That gap is itself part of why we score deposits and withdrawals at 2 out of 10 here, against a previous overall mark of 3.5 for this broker that this review now puts at 4.8. The move is our own reassessment against current evidence, not a claim that the firm changed anything; fees is the weakest of the criteria behind it, precisely because the rails on offer are narrow and the pricing behind them is not published anywhere we could find.
How money gets into a BOCOM International account
The earlier review’s breakdown lists three ways in: local bank wire, international wire, and cheque. Local bank wire is described as the primary method, taking one to two days, with bank charges applying on top. International wire is slower, three to five days, and carries higher fees plus currency conversion once the transfer crosses currencies. Cheque deposits, where accepted, are the slowest of the three at five to seven days and may also carry fees. None of the three figures came with an actual dollar or percentage cost attached, only the description that charges apply.
On top of the channel itself, the same source describes a rule that narrows things further: no third-party deposits are accepted, and funds have to move by bank wire from an account verified as belonging to the client. That rules out routing a deposit through someone else’s bank account, a spouse’s, a company’s, or otherwise, even by wire.
Getting money out
The same three channels work in both directions according to the earlier review: local wire out in one to two days, international wire out in three to five days with the added conversion cost, and cheque withdrawal in five to seven days. What is missing from every one of those entries is a number: no minimum withdrawal, no per-transfer charge, no threshold above which a fee waiver might apply. We could not fill that gap from BOCOM International’s own pages during this fetch, since the fee and terms pages we probed returned no usable content.
What is not on offer
Credit card funding, e-wallets and cryptocurrency are each listed in the earlier review as not supported for either deposit or withdrawal. That leaves bank transfer and, more marginally, cheque as the only routes in or out, which for a firm handling equities, Stock Connect access and fixed income is consistent with an institutional-facing setup rather than a retail broker built for fast, low-friction funding.
Minimum deposits by account tier
The account structure the earlier review sets out ties funding minimums to tier. The Cash Account is put at HKD 10,000 and up, with no leverage and Hong Kong market access only. The Margin Account starts at HKD 100,000, with leverage the review says is capped by the SFC and variable interest charged on the margin drawn. Stock Connect access, which adds China A-shares to Hong Kong equities, is placed at HKD 500,000 and up. An Institutional tier sits above all three with a minimum described only as negotiable, alongside a dedicated relationship manager and customised leverage. These are the only concrete minimum-deposit figures available to us for this firm, and they all come from the earlier review rather than a page we fetched ourselves.
Getting an account open at all
Before any of this funding activity can start, the earlier review describes account opening as gated behind qualified-investor or minimum-asset criteria, full KYC/AML screening, and compliance approval that it puts at five to ten business days. That sits on top of, not instead of, the deposit minimums above.
What we looked for and did not find
We checked BOCOM International’s homepage, legal, terms and legal-document pages via an Indonesian exit on 27 July 2026 for a published list of restricted countries. We did not find one there. An earlier version of this material carried a named list of restricted jurisdictions, but it could not be tied to anything the firm actually publishes, so we have dropped it rather than repeat it as the firm’s policy. The absence of a public list on the pages we checked is not the same as the firm having no such restrictions; it only means we did not find one published where we looked.
Customer Support
Our previous score for BOCOM was 3.5 out of 10. This review scores it 4.8 out of 10. The support criterion sits at 5.3, and the fee and reviews scores are what still hold the overall figure down; the evidence below is what the support number is built on.
What BOCOM actually publishes about reaching support
The one channel we could confirm first hand is a live chat widget, labeled online customer service (在线客服) in the site footer, on the Chinese language corporate site at bocomgroup.com. Beyond that widget, we could not retrieve a working contact page, phone number, email address, or stated support hours from BOCOM’s own site during this fetch. We probed legal terms, terms and conditions, about, fees, accounts, contact, risk disclosure, markets and platforms pages across gb, ae, id and au exits, and got back empty or unrendered content, or generic shells identical to pages we already held. That is a limit on what we could pull that day, not a claim that no other contact channel exists.
What our earlier review reported about service by account tier
Our earlier review described service as tied to account type rather than delivered through a single generic desk. It reported that the Cash Account (from HKD 10,000) and Margin Account (from HKD 100,000) come with no dedicated relationship manager, while the Stock Connect tier (from HKD 500,000) sometimes includes one, and the Institutional tier, with a negotiable minimum, carries a dedicated relationship manager along with multiple platform options and flexible settlement. We restate this as what the earlier review found, since we did not read the account pages ourselves.
Who can actually open an account with BOCOM
The same earlier review reported that opening an account requires meeting qualified investor or minimum asset criteria, passing KYC and anti-money-laundering screening, and clearing compliance approval, with a stated turnaround of five to ten business days. It also reported that BOCOM does not accept third party deposits: funds must arrive by bank wire from an account verified as belonging to the client. Both of these shape what a client dealing with support can expect before they are even trading, and both are second hand facts from that earlier review rather than anything we read on BOCOM’s own pages.
What “protection” means if a trade goes against a client
The earlier review also drew a distinction worth keeping for anyone contacting support about a margin call. It reported that the negative balance protection concept marketed by retail forex brokers does not apply here; instead, margin accounts are subject to margin calls and forced liquidation once equity falls below maintenance requirements, and cash accounts cannot go negative because purchases require full payment upfront. No margin call percentage, stop out level, or published negative balance protection policy was available to the earlier review, so a client cannot look up in advance exactly where that line sits.
The regulatory record behind any complaint
BOCOM International Securities Limited holds CE reference APJ121 on the Hong Kong SFC Public Register of Licensed Persons and Registered Institutions, active for Type 1, Type 2, Type 4 and Type 5 activities (dealing in securities, dealing in futures contracts, advising on securities, advising on futures contracts), with no public disciplinary action recorded against it. A second entity, BOCOM International Futures Limited, holds CE reference BGZ962 on the same SFC register; the record lists no regulated activities we could read for it, and it too carries no public disciplinary action on the register. Both entities’ names begin with “BOCOM International” rather than matching a single named brand entity, which matters if a client is trying to work out which company they actually hold an account with before raising a complaint. We also searched 1,441 warning list entries mirrored from CySEC, the FCA and the FSC Mauritius, and BOCOM does not appear on any of them; that is a clean result across the lists we mirror, not a clearance from every regulator worldwide.
A warning worth repeating here
The earlier review flagged that any site offering retail forex or CFD trading, MetaTrader 4 or 5, or leverage such as 1:500 under the BOCOM name is not this firm. The SFC-licensed entity is a securities and investment banking business serving institutional and qualified investors, and the live bocomgroup.com site we fetched is structured around corporate finance, securities and futures, asset management, investment and financing, research, and investor relations, with no forex, MT4/MT5 or leverage products in evidence. Anyone reaching out to “BOCOM support” about a retail forex account is very likely dealing with an impersonator rather than this firm.
Prohibited Countries
None of the BOCOM International pages we fetched sets out which countries it will not serve. An earlier review of this firm checked the homepage, legal, terms and legal-documents pages via an Indonesian exit on 27 July 2026 and reported finding no published restricted-country list. That same earlier material had at one point carried a list of countries, including Iran, North Korea, Syria and Cuba, presented as this broker’s policy; the earlier review could not tie that list to anything BOCOM actually publishes and removed it. We are restating that history rather than repeating the list itself, because we hold no BOCOM page that states it.
What we could and could not fetch from BOCOM International
Our own attempt to read the firm’s disclosures ran into the same gap from a different angle. Pages for legal terms, terms-and-conditions, about, fees, accounts, contact, risk disclosure, markets and platforms came back empty or unrendered, or were generic shells identical across the UK, UAE, Indonesian and Australian exits we tried. A restricted-country clause, if one exists, sits inside exactly the kind of legal or terms page that returned nothing for us. We can report the fetch failure; we cannot report a policy we never saw.
Who BOCOM International says it serves instead
What the earlier review did find, and what we are restating rather than quoting, is a client-eligibility gate rather than a country list. Opening an account is described as requiring qualified-investor or minimum-asset criteria, KYC/AML screening, and compliance approval taking five to ten business days, with the account types aimed at institutional and qualified investors rather than general retail clients. The same material reports that no third-party deposits are accepted: funds must arrive by bank wire from an account verified as belonging to the client. Together these operate as a screen on who can open an account at all, separate from any nationality-based exclusion.
The earlier review also stresses a different kind of exclusion: that BOCOM International does not offer retail forex or CFD trading, MetaTrader 4 or 5, or high leverage such as 1:500, and that any site offering these under the BOCOM name is, in the earlier review’s own words, an impersonator rather than this firm. Our first-hand look at the live bocomgroup.com site is consistent with that framing: the rendered pages we pulled show sections for corporate finance, securities and futures, asset management, investment and financing, research and investor relations, with no mention of forex, MT4/MT5 or leverage products. We searched 1,441 warning-list entries mirrored from CYSEC, the FCA and the FSC Mauritius, and BOCOM International’s name matches none of them; that covers only those three regulators, not a global check for impersonator sites trading under its name.
What the SFC register adds
We searched the Hong Kong SFC Public Register of Licensed Persons and Registered Institutions directly, running a positive control first so an empty result would mean absence rather than a broken search. CE reference APJ121 is held by BOCOM International Securities Limited, licensed for Type 1, Type 2, Type 4 and Type 5 activities (dealing in securities, dealing in futures contracts, advising on securities, advising on futures contracts), all shown active, with no public disciplinary action recorded against it. A second reference, BGZ962, is held by BOCOM International Futures Limited; the SFC record we could read lists no regulated activities for it and, likewise, no public disciplinary action. Neither entry amounts to a country restriction, but both tie the legitimate, licensed entity to Hong Kong Securities and Futures Commission oversight rather than to the retail forex offering the impersonator warning above is aimed at. A claim of China Securities Regulatory Commission licensing for mainland China also appears in the earlier review; the CSRC’s own 2020 list of securities companies names no BOCOM company, though the claim gives no licence type, so a CSRC authorisation of another kind cannot be ruled out.
Put plainly: we can document a client-type gate (qualified investors and institutions, five-to-ten-day compliance approval, no third-party funding) and an impersonator warning, both carried over from the earlier review, plus a clean result against three mirrored warning lists and an active SFC licence for the securities entity. We cannot document a country-by-country exclusion list, because neither the earlier fetch nor ours turned up a BOCOM page that states one.
Conclusion
BOCOM scores 4.8 out of 10 in this pass, up from the 3.5 we previously recorded. The move comes from reassessing the same category of firm against current evidence, not from any change at the firm: regulation lands at 5.6, fees at 2, platform at 6.6, support at 5.3 and reviews at 4.5. The SFC register is what pulls regulation up from where a purely reputational read would leave it, and it is also what caps it.
What the SFC register shows for BOCOM
We searched the Hong Kong SFC Public Register of Licensed Persons and Registered Institutions directly, and ran a positive-control search first so that a clean result means absence rather than a broken query. CE reference APJ121 is held by BOCOM International Securities Limited, licensed for Type 1, Type 2, Type 4 and Type 5 activities (dealing in securities, dealing in futures contracts, advising on securities, advising on futures contracts), all shown active, with no public disciplinary action recorded against it. A second reference, BGZ962, is held by BOCOM International Futures Limited; the SFC record lists no regulated activities we could read against it, and again no public disciplinary action. Both entries name “BOCOM International” companies rather than the brand alone, which is the checkable link between the marketing name and the licensed company. We also hold a CSRC mainland China licence claim and a China ICP website filing from our earlier review and the firm’s own footer; the CSRC’s 2020 list of securities companies names no BOCOM company, and the ICP filing is unchecked.
On the warning-list side, we searched 1,441 entries mirrored from the CySEC, FCA and FSC Mauritius warning lists and BOCOM appears on none of them. That is a real, if narrow, clean result: it covers only the three regulators we mirror, not a global sweep.
Why fees score is low
We could not pull a fee schedule, spread table or commission page from BOCOM’s own site during this fetch; multiple probed pages for fees, accounts, legal terms and risk disclosure came back empty or as generic shells repeated across the gb, ae, id and au exits we tried. The only figures we can carry into this review are the account minimums reported by our earlier review: a Cash Account at HKD 10,000 and up, a Margin Account at HKD 100,000 and up, a Stock Connect account at HKD 500,000 and up, and an Institutional tier with a negotiable minimum. Those numbers come from the prior review’s text, not from a page we fetched, so we are restating them rather than quoting the firm. With no verifiable commission, spread or custody-fee figures of our own, a low fees score reflects what we could not confirm as much as what the account tiers themselves suggest.
Platform and account access
The same material from our earlier review describes a proprietary BOCOM trading system built for Hong Kong and China A-share equities, available on iOS, Android, web and desktop, with basic charting, standard equity order types and no automated-trading or EA support; it explicitly does not offer MT4 or MT5. Separately, the live bocomgroup.com Chinese-language corporate site we fetched shows sections for corporate finance, securities and futures, asset management, investment and financing, research and investor relations, with no mention of forex, MT4/MT5 or leverage products, which corroborates the same picture independent of our earlier review. Account opening is gated behind qualified-investor or minimum-asset criteria, KYC/AML screening and compliance approval running five to ten business days, and BOCOM does not accept third-party deposits, only bank wires from accounts verified as belonging to the client, according to that same reporting.
Support and the impersonation risk worth flagging
The one support channel we found first-hand was a live-chat widget in the site footer, labeled online customer service (在线客服). Our earlier review’s most consequential point is not about BOCOM’s own service but about lookalikes: it reports that any site offering retail forex or CFD trading, MetaTrader 4/5, or leverage up to 1:500 under the BOCOM name is not the SFC-licensed entity described here, since the licensed BOCOM International companies deal in securities and futures for institutional and qualified investors, not retail forex. A reader who finds a “BOCOM” forex platform advertising high leverage is not looking at APJ121 or BGZ962.
What holds the overall score down
The register confirms two active, on-name licences with no disciplinary history and a clean result across three warning lists, which is more than many entries in this category can show. Set against that: BOCOM does not serve retail traders in any accessible way, its fee structure is unverifiable from what we could fetch, account minimums run into six figures of Hong Kong dollars for anything beyond a basic cash account, and its own legal, fee and risk-disclosure pages returned empty across four geographic exits.
BOCOM International’s Hong Kong SFC licences (APJ121, active, no disciplinary record) check out on the regulator’s own register, but its published fee, legal and risk pages could not be fetched and its accounts require six-figure HKD minimums, landing it at 4.8 out of 10.
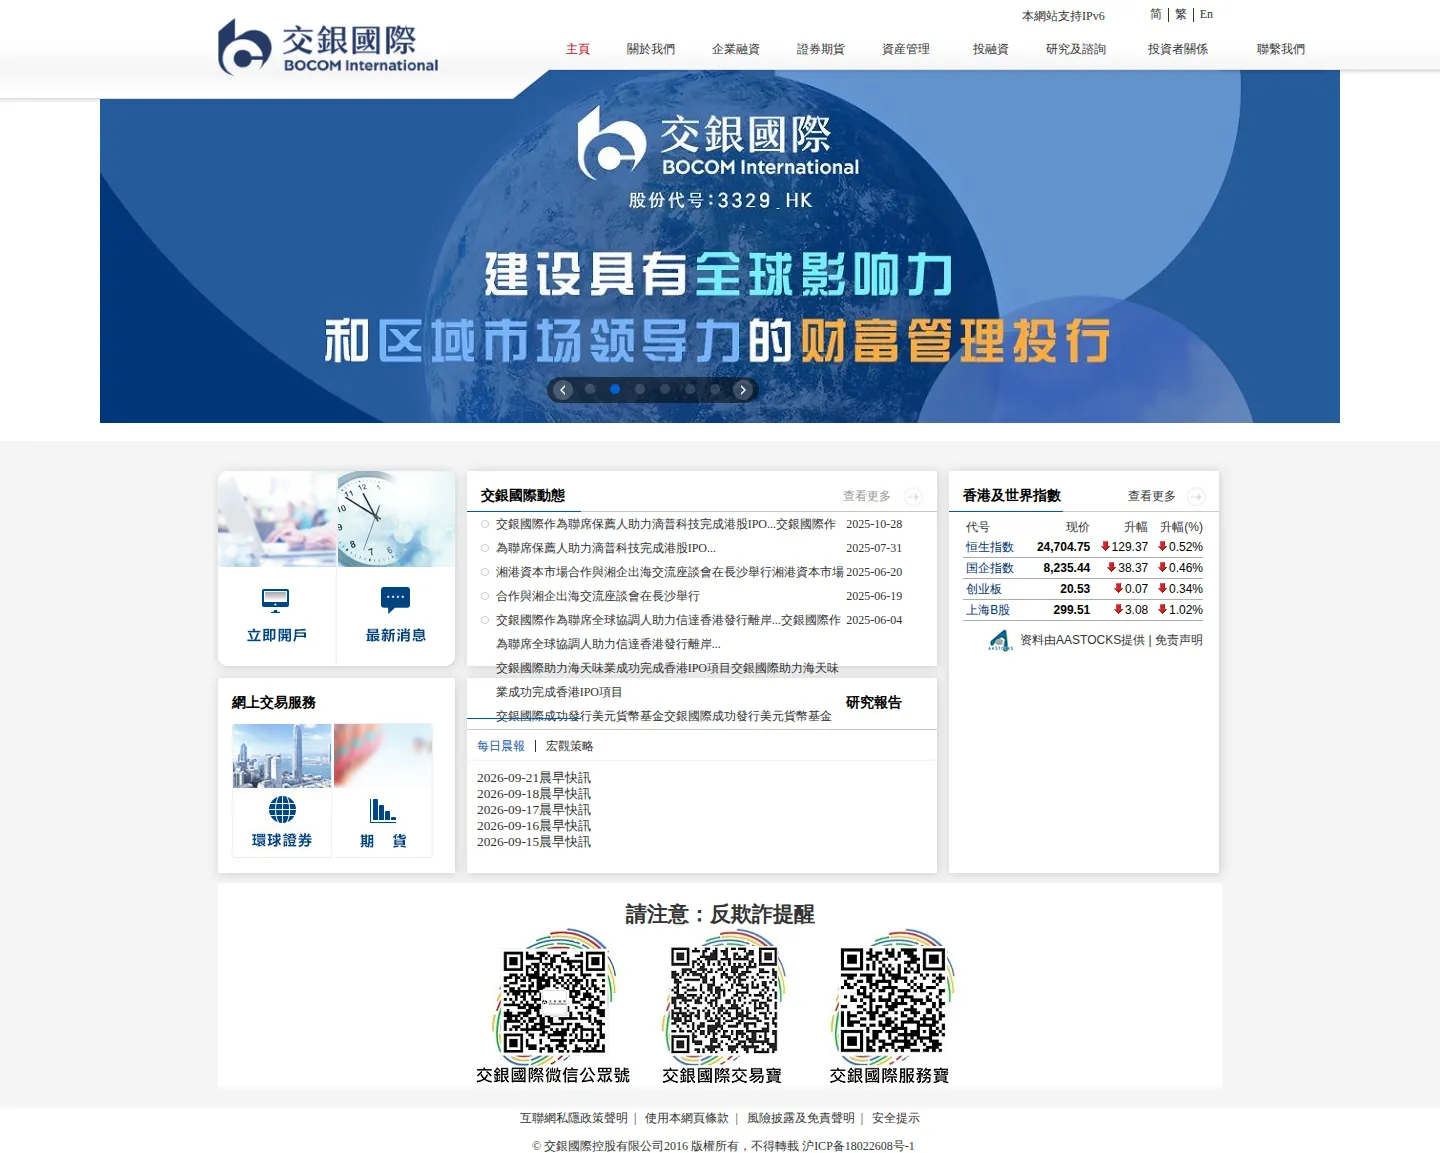
What we saw
Pages captured from BOCOM’s own site when this review was written. Brokers change their terms; these are what we read.
Score history
Recomputed daily; every move is on the record. The current score is always the latest row.
| Date | Score | Move |
|---|---|---|
| 2026-09-30 | 4.8 | ▲ |
| 2026-07-25 | 3.5 | ▼ |
| 2026-07-18 | 3.6 | ▼ |
| 2026-07-11 | 3.7 | · |
FAQ
Is BOCOM regulated?
Yes, the BOCOM International brand holds an active licence (APJ121) from Hong Kong’s Securities and Futures Commission. No second regulator is currently verified.
What does BOCOM charge in fees?
No trading fees or cost schedule are published on BOCOM’s own pages.
What trading platforms does BOCOM offer?
BOCOM offers a web platform, a mobile app, and a proprietary desktop platform integrated with Hong Kong Exchange systems.
How can I contact BOCOM support?
Live chat is the only support channel listed.
What do reviews say about BOCOM?
Reviews are thin, with a blended score of 3.18 stars across just 5 ratings.
Is BOCOM's ICP filing a licence?
No, the ICP filing is a website registration, not a financial trading licence.
How this review works
Track BOCOM live: score moves and red notices, in your pocket.