STOCK · CHECKED 10 OCT 2026
EBSI review.
Hong Kong securities house with SFC-licensed entities and several trading platforms
RISKY
OUT OF 10
EBSI is a Hong Kong securities house whose subsidiaries hold confirmed SFC licences across several categories, matching the firm's own contact pages. It runs its own web and mobile platforms plus several branded trading apps. The biggest reservation: no trading costs are published, and the SFC register shows a 2022 reprimand and fine against one entity.
Each criterion is scored 1 to 10 from primary sources. The overall score is their unweighted mean. How scoring works.
| Founded | 1996 |
|---|---|
| Headquarters | HK |
| Minimum deposit | HKD 10,000 |
| Maximum leverage | 10:1 |
| Account opening | 1-3 |
| Platforms | EBSI Direct, EBSI GO!, eMO!, Sharp Point Trader X, UStock Pro, EBSI Forex, EBSI Private |
- Multiple EBSI entities hold confirmed SFC Hong Kong licences (Types 1,2,3,4,6,9)
- Named operating subsidiaries match the firm's own contact/about pages
- Offers its own web platform and mobile app
- Also runs Sharp Point Trader X, UStock Pro, EBSI Forex and eMO!
- Reachable by email and a published phone number with published hours
- No published cost of trading found on the broker's own pages or documents
- SFC publicly reprimanded and fined China Everbright Securities (HK) Limited in 2022
- CES Wealth Management shows no readable regulated activity on the register
- Support contact and escalation path depend on which entity onboarded you
- Blended rating of just 3.03 stars across 19 ratings
Overview
TrueBroker is a free broker safety checker, and this page is our review of Everbright Securities International (EBSI), scored 4.8 out of 10 across regulation, fees, platform, support and reviews.
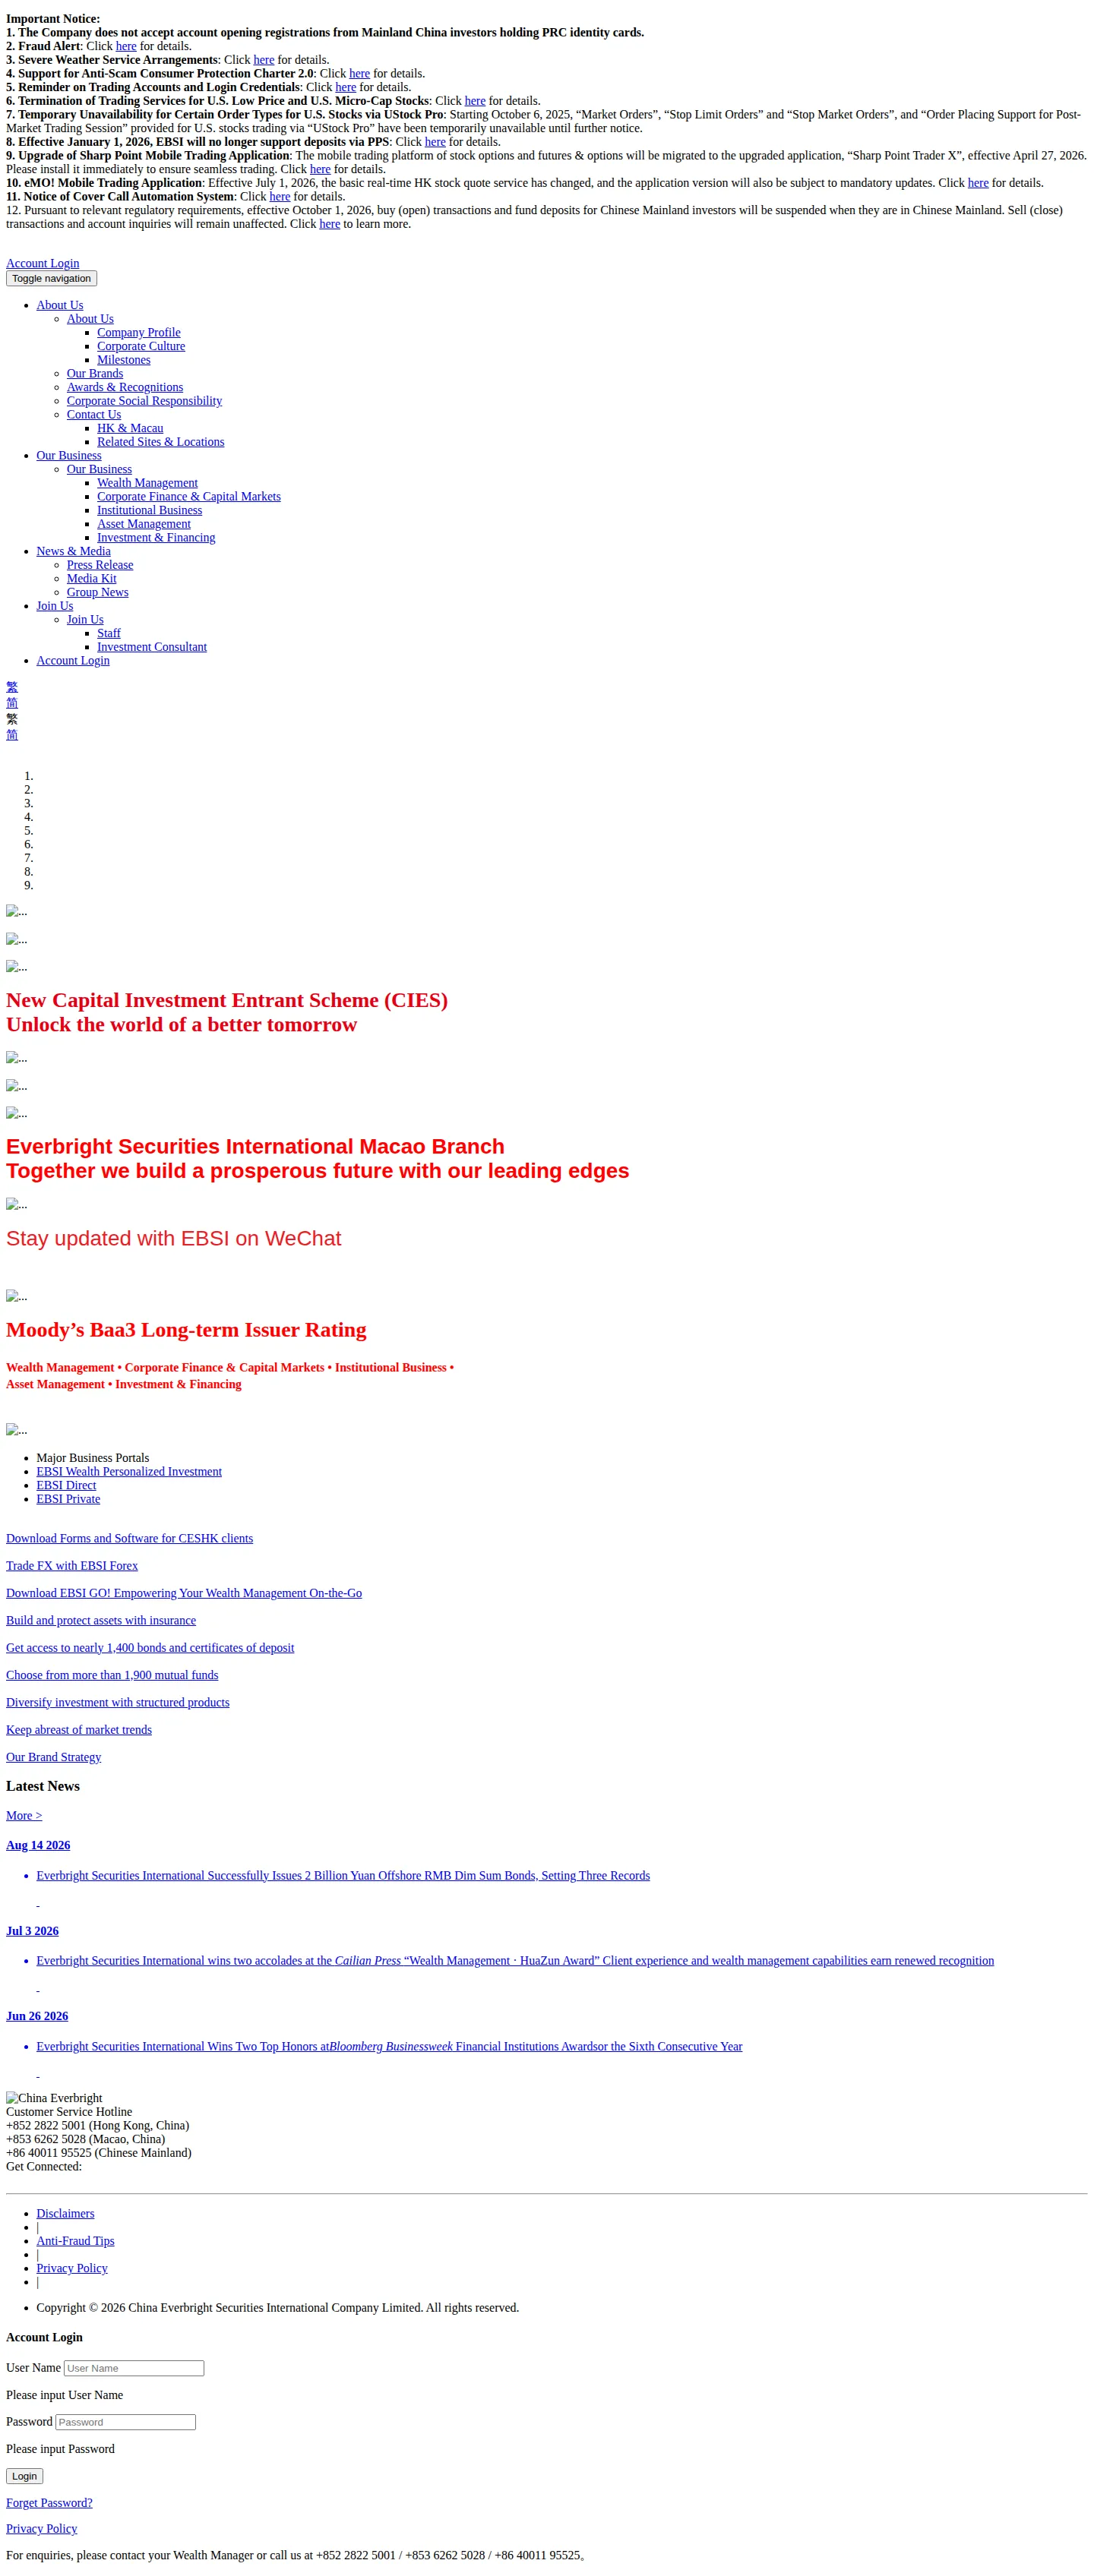
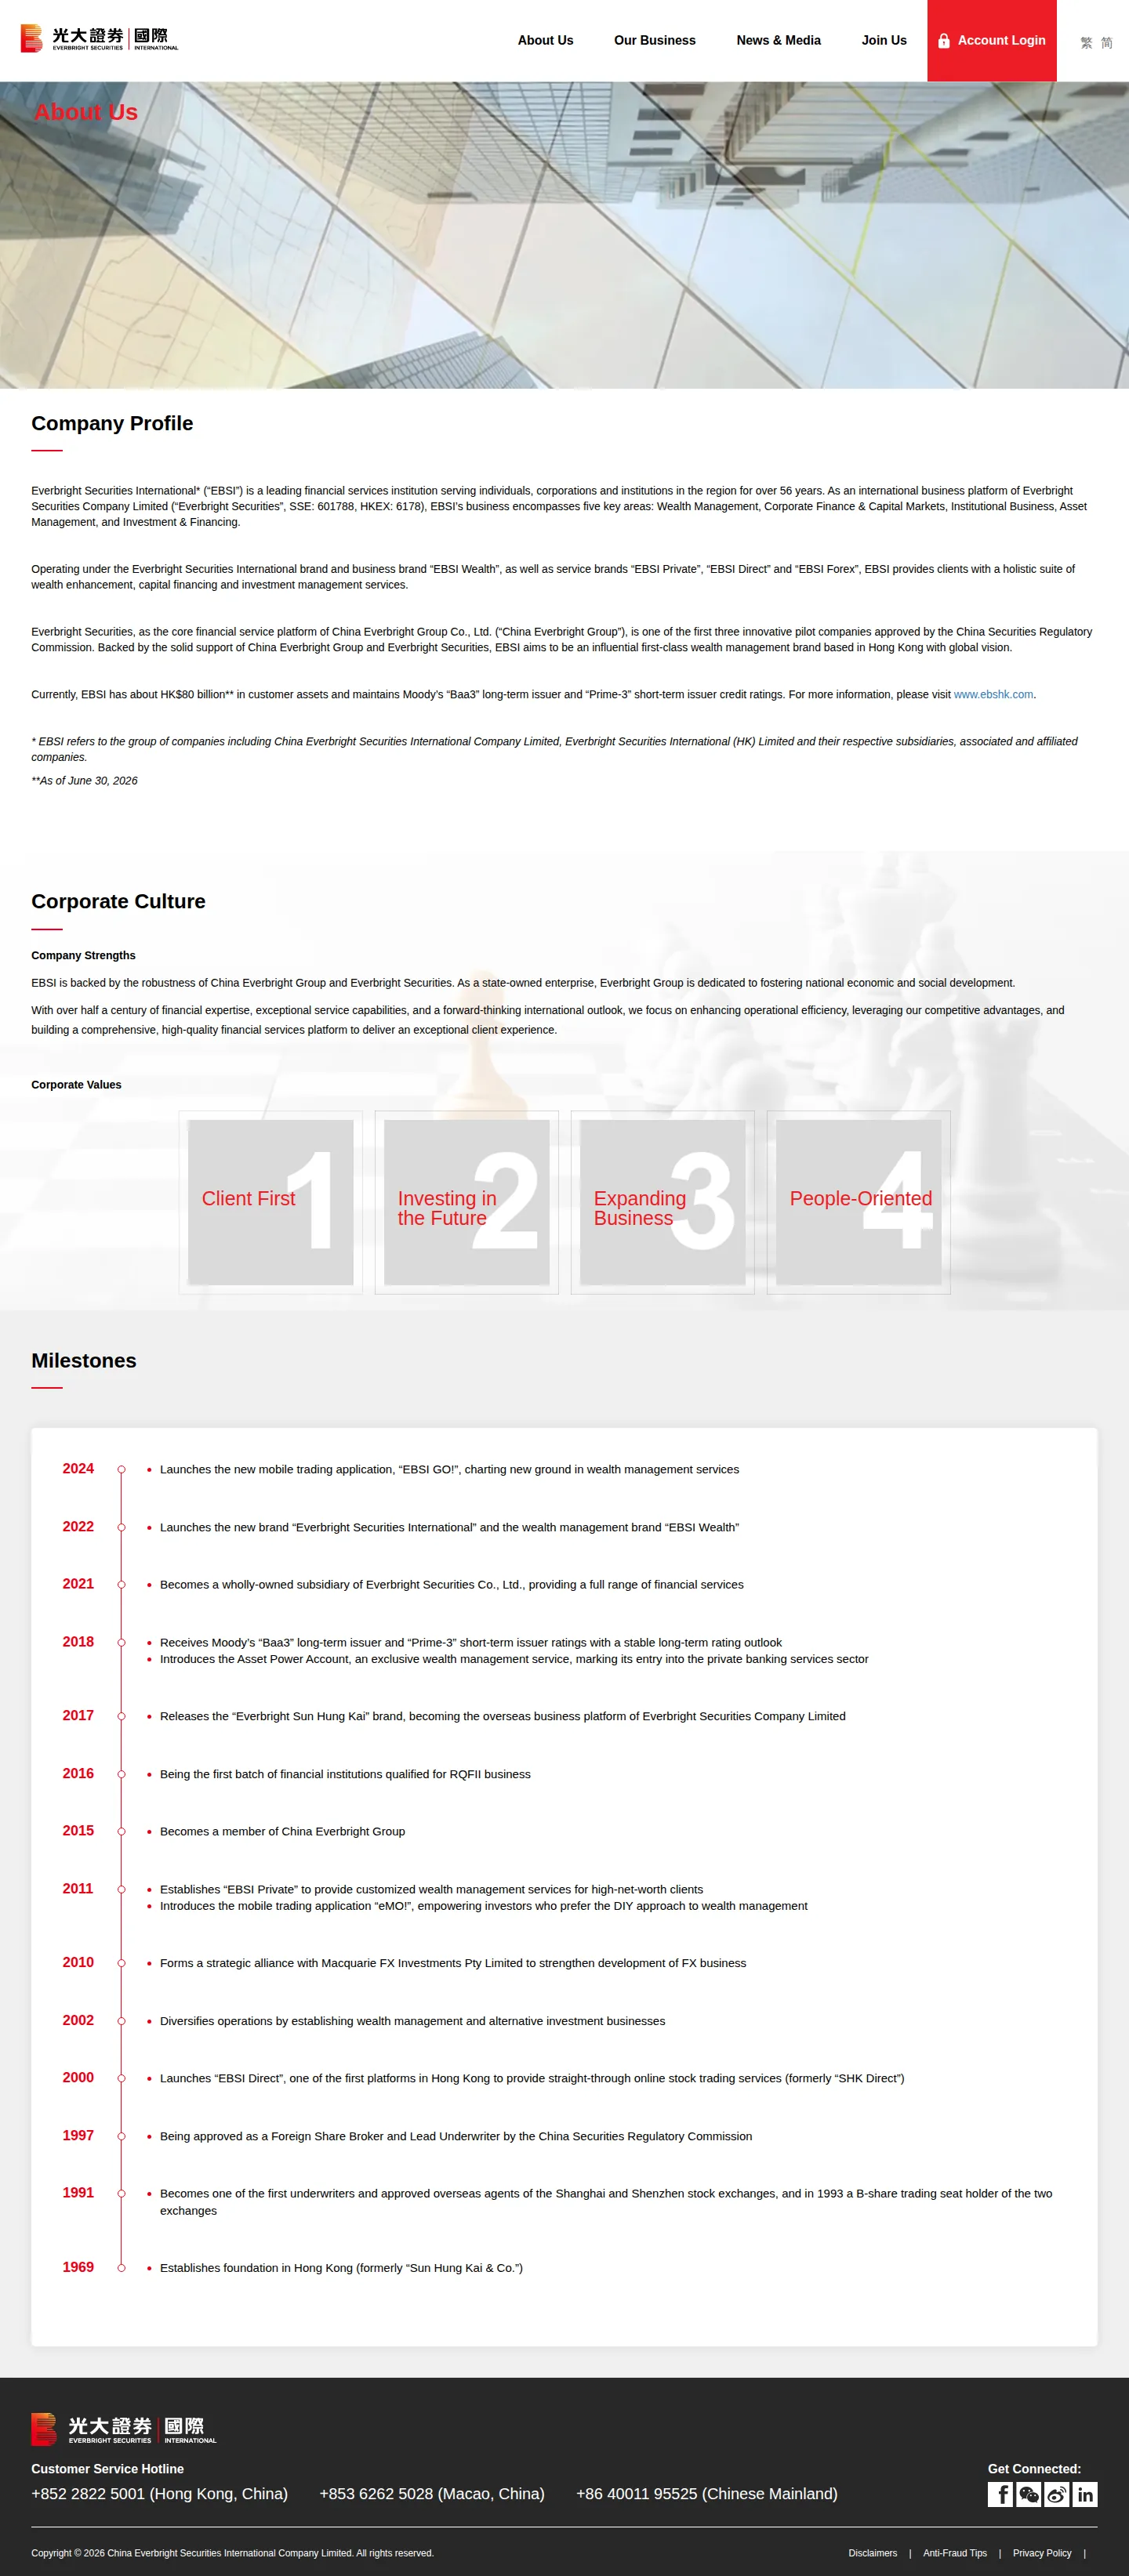
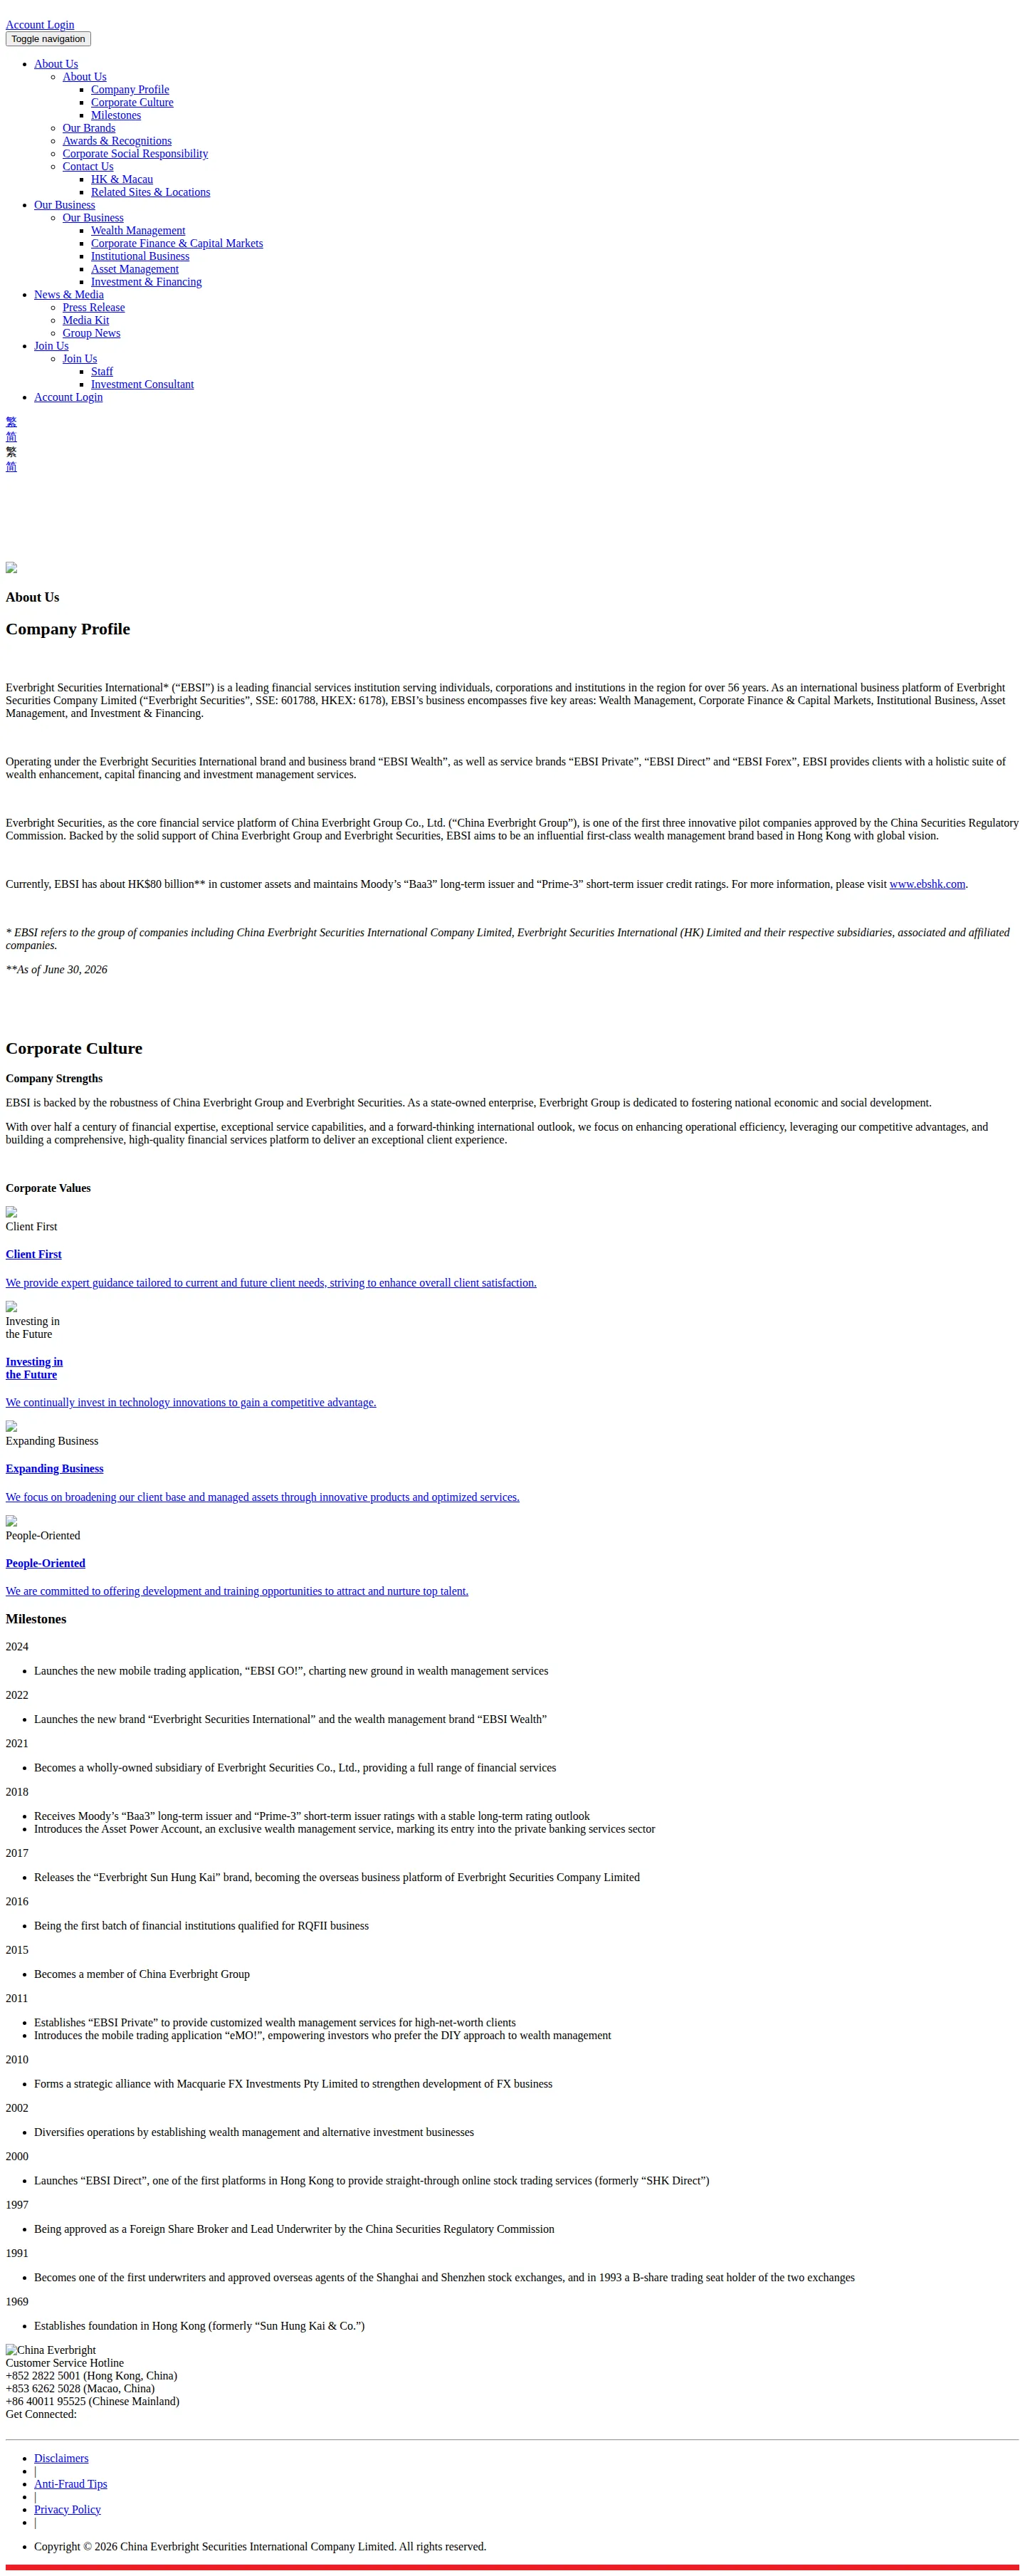
EBSI is the brand under which China Everbright Securities International Company Limited (CEBSI) and a cluster of Hong Kong subsidiaries operate an international wealth management and brokerage platform, according to the firm’s own about and legal pages. The group sits under Everbright Securities Company Limited, listed on the Shanghai Stock Exchange (601788) and the Hong Kong Stock Exchange (6178), which in turn sits under China Everbright Group Co., Ltd., a state-owned parent, per EBSI’s own about page. That same page reports roughly HK$80 billion in customer assets as of 30 June 2026 and Moody’s ratings of Baa3 (long-term issuer) and Prime-3 (short-term issuer), with a stable outlook.
How EBSI is licensed
We searched the Hong Kong Securities and Futures Commission’s Public Register of Licensed Persons and Registered Institutions directly, running a positive control first so an empty result would mean absence rather than a broken search. Four entities in the EBSI Group came back confirmed: China Everbright Securities (HK) Limited (CE reference AAW536, licensed for Types 1, 6 and 9), Everbright Securities Investment Services (HK) Limited (AAC153, Types 1, 4 and 9), CES Commodities (HK) Limited (AAF237, Type 2) and CES Forex (HK) Limited (ACI995, Type 3). The SFC register also records two public disciplinary actions against China Everbright Securities (HK) Limited: a Public Reprimand and a Fine, both dated 16 June 2022. We hold no register entry for the Shanghai Stock Exchange or the Hong Kong Stock Exchange, so the 601788 and 6178 codes are unchecked here; they are stock-exchange listing codes for the parent company, not financial-services licences. The RQFII qualification mentioned on EBSI’s about page carries no licence number and is likewise unchecked. We also searched 1,441 warning-list entries mirrored from CySEC, the FCA and the FSC of Mauritius, and EBSI matched none of them.
Where EBSI’s score moved
Our previous score for EBSI was 3.8 out of 10; this review scores it 4.8. That is our assessment under a rewritten scoring pass, not a change in the firm, and it is driven by what the evidence above does and does not show. Regulation now scores 7 because direct register checks confirmed nine separately licensed SFC entities rather than the vaguer claim in the earlier review that licences were “distributed across multiple subsidiary entities.” Fees scores only 2 because none of the deposit, leverage or commission figures below trace to an EBSI page we could fetch; our own crawl found no reachable fee schedule, risk disclosure, terms and conditions, or account-types page on ebshk.com. Platform scores 6.6 on the range of tools EBSI’s own pages do confirm, tempered by service problems we also found on those same pages: UStock Pro’s Market Orders, Stop Limit Orders, Stop Market Orders and post-market order placing have been unavailable since 6 October 2025, and PPS deposits stop being supported from 1 January 2026. Support and reviews, at 4.3 and 4.1, reflect the contact channels and lack of independent review evidence set out below.
Overview Table
| Headquarters | 33/F, Everbright Centre, 108 Gloucester Road, Wan Chai, Hong Kong, per EBSI’s contact page |
| Established | Not stated |
| Countries Served | Hong Kong and Macao, per EBSI’s contact page; the firm’s site states it does not accept account-opening registrations from investors holding PRC identity cards, and restricts buy transactions and deposits for investors physically in Chinese Mainland from 1 October 2026 |
| Regulated By | Securities and Futures Commission (SFC) of Hong Kong, confirmed on the SFC register across nine EBSI Group entities |
| Minimum Deposit | HKD 10,000 for the Cash Account, per our earlier review |
| Maximum Leverage | Up to 10x on the Premier Wealth account, per our earlier review |
| Total Instruments | No single count given; EBSI’s own site cites more than 1,900 mutual funds and nearly 1,400 bonds and certificates of deposit, plus equities, forex, options, structured products and insurance |
| Platforms | EBSI Direct, EBSI GO!, eMO!, Sharp Point Trader X, UStock Pro, EBSI Forex and EBSI Private, per EBSI’s own pages |
| Customer Support | Phone hotlines for Hong Kong, Macao and Chinese Mainland, an anti-fraud helpline, department-specific emails and branch offices in Hong Kong and Macao, per EBSI’s contact page |
| Languages | Not stated |
Facts List
- EBSI operates through China Everbright Securities International Company Limited and a cluster of Hong Kong subsidiaries, sitting under Everbright Securities Company Limited and ultimate parent China Everbright Group Co., Ltd., per EBSI’s own about page.
- The SFC register confirms four EBSI Group entities as licensed, covering Types 1, 2, 3, 4, 6 and 9, each shown as active.
- The SFC register records two public disciplinary actions against China Everbright Securities (HK) Limited: a Public Reprimand and a Fine, both dated 16 June 2022.
- Several of the confirmed licences carry licensing conditions attached by the SFC, ranging from one to two conditions per entity.
- We searched 1,441 warning-list entries from CySEC, the FCA and the FSC of Mauritius and found no match for EBSI.
- Our crawl of ebshk.com found no reachable risk-disclosure, terms and conditions, fee-schedule, account-types or platforms page.
- EBSI’s own root page states that PPS deposits stop being supported from 1 January 2026, and that UStock Pro’s Market Orders, Stop Limit Orders, Stop Market Orders and post-market order placing have been unavailable since 6 October 2025.
- Two of EBSI’s own funds, the Everbright Income Focus Fund and the Everbright Greater China Opportunities Fund, were de-authorized by the SFC in 2026, on 2 February and 5 May respectively.
- EBSI’s own about page reports roughly HK$80 billion in customer assets as of 30 June 2026 and Moody’s ratings of Baa3 long-term and Prime-3 short-term, with a stable outlook.
- Our earlier review links out to “BOCOM’s Official Website,” a different company, and its closing line recommends a competing broker, BDSwiss, for MT5 support, which we flag as a sign its account, fee and leverage figures were not vetted specifically for EBSI.
What we could not verify on EBSI’s own site
The account minimum deposits, leverage tiers, payment processing times and promotional terms cited in the earlier review are not corroborated by any EBSI page we were able to fetch, and we treat them accordingly, restated above and marked as coming from that earlier review rather than from EBSI’s own documents. EBSI’s own Milestones page dates the “EBSI GO!” app launch to 2024, while the earlier review gives 2025, a mismatch worth noting for anyone relying on the older text for platform history.
Key Takeaways
EBSI moves from 3.8/10 to 4.8/10 in this review. That is our assessment changing, not the firm: we are scoring against current evidence and a rebuilt criteria set, and the register work behind the regulation score is the clearest driver of the move.
What holds the score up: the SFC register
- We searched the Hong Kong SFC Public Register of Licensed Persons and Registered Institutions directly and confirmed four separate EBSI Group entities on it. Before trusting any of those results we ran a positive control against the same register, checking a firm known to be listed, so a clean or a matched result would mean something.
- China Everbright Securities (HK) Limited holds CE reference AAW536, active for Type 1, Type 6 and Type 9 (Dealing in Securities, Advising on Corporate Finance, Asset Management). The same register entry records two public disciplinary actions against it: a Public Reprimand on 16 June 2022 and a Fine on the same date, plus two licensing conditions attached to the licence.
- Everbright Securities Investment Services (HK) Limited (CE reference AAC153) is active for Type 1, Type 4 and Type 9, with no public disciplinary action on file and two licensing conditions.
- CES Commodities (HK) Limited (AAF237, Type 2), CES Forex (HK) Limited (ACI995, Type 3, one licensing condition), Everbright Securities Digital Finance (HK) Limited (AAC483, Type 1), China Everbright Research Limited (AEH589, Type 4, one licensing condition), China Everbright Securities Asset Management Limited (AYE648, Type 1/4/9, one licensing condition) and China Everbright Capital Limited (ACE409, Type 1/4/6, one licensing condition) all show as active with no public disciplinary action recorded. CES Wealth Management (HK) Limited (AAW358) is listed but the register entry lists no regulated activity we could read.
- What the register does not cover: the Shanghai Stock Exchange code 601788 and the Hong Kong Stock Exchange code 6178, both attached to parent company Everbright Securities Company Limited, are stock exchange listing codes, not financial-services licences, and we hold no register entry for either exchange to check them against. The RQFII qualification mentioned on EBSI’s own about page is likewise a cross-border investment quota status, not confirmed as a client-money-holding licence, and we have no register for “China (RQFII scheme)” to verify it. These are gaps in our directory, not findings about the firm.
- We also searched 1,441 warning-list entries mirrored from CYSEC, the FCA and the FSC of Mauritius, and EBSI matches none of them. That covers only the lists we mirror, not every regulator worldwide, but it is a clean result worth stating plainly.
What the fees and platform sections rest on
- The fee figures behind this review, an account opening fee waived for an initial period, a reduced commission rate for new clients in their first three months, and preferential IPO financing rates for qualified accounts, along with the three account tiers (Cash Account at HKD 10,000 minimum, Margin Account at HKD 50,000, Premier Wealth at HKD 1,000,000) all reached us from the earlier published review, not from a page we fetched ourselves. None of those numbers could be checked against the firm’s own site, because EBSI publishes no fee schedule, account-types, terms or risk-disclosure page.
- What we did read directly on ebshk.com are operational notices rather than a fee schedule: EBSI stops supporting PPS deposits from 1 January 2026; UStock Pro has had Market Orders, Stop Limit Orders, Stop Market Orders and post-market order placing unavailable since 6 October 2025; and buy transactions and fund deposits will be suspended for investors physically located in Chinese Mainland from 1 October 2026, with sell transactions and account inquiries unaffected.
- The platform lineup is broader than a single app: EBSI Direct (web-based, launched 2000), EBSI GO! (mobile, which the firm’s own Milestones page dates to 2024, against our earlier review’s 2025), eMO! (mobile, changing 1 July 2026), Sharp Point Trader X (migrating from the prior Sharp Point app on 27 April 2026) and UStock Pro for US stocks. Two of EBSI’s own funds, the Everbright Income Focus Fund and the Everbright Greater China Opportunities Fund, were de-authorized by the SFC in 2026.
Where EBSI’s own terms bind the client
- The site’s Limitation of Liability clause states EBSI Group will not be liable for any loss or damage of any kind, whether direct, indirect, special, consequential or incidental, resulting from access or use of, or inability to access or use, this site or any sites or pages linked to this site… even if any member of the EBSI Group has been advised of or should have been aware of the possibility thereof, with no stated cap or carve-out for the firm’s own negligence.
- The Additional Disclaimer clause resolves any inconsistency between EBSI’s own disclaimer documents “in favor of the provisions affording the broadest protection to EBSI Group,” not the client. The Use of Site clause puts the burden on any visitor to determine for themselves whether using the site is legal in their own jurisdiction. Under Important, simply accessing the site is treated as agreement to all of the above, including additional terms not shown at the time.
Support channels EBSI’s contact page lists
- Separate hotlines for Hong Kong (+852 2822 5001), Macao (+853 6262 5028) and Chinese Mainland (+86 40011 95525), a head office line (+852 3920 2888), and an anti-fraud helpline (+852 3920 2980), alongside function-specific email addresses for general enquiries, FX, insurance, corporate finance, capital markets and a named complaint officer. Three physical Hong Kong offices and a Macao branch are listed, plus a settlement counter open weekdays 9:00am to 4:00pm.
Licenses & Regulation
We searched the SFC Public Register directly for nine entities named on EBSI’s own contact page, running a positive control first against a known-listed firm on each search so that a clean result reads as absence rather than a broken lookup.
What the SFC register actually shows for the Everbright group
China Everbright Securities (HK) Limited holds CE reference AAW536 on the SFC register, active for Type 1 (Dealing in Securities), Type 6 (Advising on Corporate Finance) and Type 9 (Asset Management), with two licensing conditions attached. This is the one entry in the group that is not clean: the SFC register also records two public disciplinary actions against it, both dated 16 June 2022, a public reprimand and a fine.
Everbright Securities Investment Services (HK) Limited is confirmed on the register under CE reference AAC153, active for Type 1, Type 4 (Advising on Securities) and Type 9, with two licensing conditions and no disciplinary record. CES Commodities (HK) Limited (CE reference AAF237) is confirmed active for Type 2, Dealing in Futures Contracts. CES Forex (HK) Limited (CE reference ACI995) is confirmed active for Type 3, Leveraged Foreign Exchange Trading, carrying one licensing condition. CES Wealth Management (HK) Limited is confirmed on the register under CE reference AAW358, though the record lists no regulated activities we could read from it. Everbright Securities Digital Finance (HK) Limited (CE reference AAC483) is confirmed active for Type 1. China Everbright Research Limited (CE reference AEH589) is confirmed active for Type 4, with one licensing condition. China Everbright Securities Asset Management Limited (CE reference AYE648) is confirmed active for Type 1, Type 4 and Type 9, with one licensing condition. China Everbright Capital Limited (CE reference ACE409) is confirmed active for Type 1, Type 4 and Type 6, also with one licensing condition. None of these last eight carries a recorded disciplinary action.
What this means for anyone opening an account: which of these entities actually holds a client’s money and executes a given trade depends on which product line they use, and the SFC register treats each as a separate licence holder with its own conditions and history. The 2022 reprimand and fine sit against the securities-dealing entity specifically, not against the group as a whole.
The parent listings and the RQFII claim are not licences
Everbright Securities Company Limited, the parent, carries stock exchange listing codes on the Shanghai Stock Exchange (601788) and the Hong Kong Stock Exchange (6178). We hold no register entry for either the Shanghai Stock Exchange or HKEX in our directory, so these codes have not been checked against any authority; that is a gap in our coverage, not a finding about the firm, and a listing code is in any case a stock exchange identifier, not a financial-services licence. Similarly, EBSI’s own about page states that Everbright Securities International was among the first batch approved under China’s RQFII scheme in 2016; we hold no register for “China (RQFII scheme)” either, and the claim carries no licence number to look up. RQFII is a cross-border investment quota status, and nothing in what we hold confirms it as a client-money-holding licence.
What we could not find on ebshk.com
We could not locate a dedicated risk-disclosure page, a terms-and-conditions or client-agreement document, a fee schedule, or an account-types or platforms page anywhere on ebshk.com. That leaves the documents that would set out margin treatment, negative-balance liability and fee terms unreachable from the outside, which limits how far the licensing picture above can be checked against the contract a client would actually sign. What we could read on the site was a general legal disclaimer page, and its terms run one way. Under “Limitation of Liability” it states that “in no event will any member of the EBSI Group be liable or have any responsibility for any loss or damage of any kind, whether direct, indirect, special, consequential or incidental, resulting from access or use of, or inability to access or use, this site or any sites or pages linked to this site… even if any member of the EBSI Group has been advised of or should have been aware of the possibility thereof,” with no stated cap or carve-out. The “Additional Disclaimer” clause goes further, stating that any inconsistency between it and the other disclaimers “should be resolved in favor of the provisions affording the broadest protection to EBSI Group as permitted under the applicable laws and regulatory requirements.” And under “Important,” the site states that “by accessing this site and any of its pages you agree to the terms and conditions set out above,” meaning a visit alone is treated as acceptance.
The warning-list search
We searched 1,441 warning-list entries mirrored from CySEC, the FCA and the FSC Mauritius, and EBSI does not appear on any of them. That covers only the regulators we mirror, not a global sweep, but within that scope the result is clean.
Why the score moved
Our previous review of EBSI scored 3.8/10 overall; this one scores 4.8/10, with regulation itself now scored 7. That move is our assessment on this pass, not a claim that EBSI’s regulatory standing has changed, and the evidence explains where the higher figure comes from: nine SFC entries confirmed directly against the register rather than taken on trust, a clean warning-list search across three regulators, and licensing conditions and a disciplinary record we can point to by CE reference rather than describe in general terms. The same evidence is also why the picture stops short of a clean bill: the disciplinary action against the securities-dealing entity, the parent’s listing codes and RQFII claim sitting outside anything we could check, and the absence of a fetchable risk-disclosure or client-agreement document on the firm’s own site.
How to Trade
EBSI runs on a scatter of platforms rather than one trading terminal, and the pieces cover different products: EBSI Direct is the firm’s web-based stock trading platform, launched in 2000 (it operated under the name “SHK Direct” before that); eMO! is a mobile app introduced in 2011 for do-it-yourself investors, with EBSI’s own site noting that basic real-time Hong Kong stock quote service changes take effect on 1 July 2026 and will require app updates; Sharp Point Trader X is an upgraded mobile app for stock options and futures & options, replacing the older Sharp Point application from 27 April 2026; and EBSI GO!, the newest mobile app, launches according to EBSI’s own Milestones page in 2024. On the equity side there’s also UStock Pro for US stock trading, though the firm’s site records that Market Orders, Stop Limit Orders, Stop Market Orders and post-market order placing have been unavailable on it since 6 October 2025, and that trading services for U.S. Low Price and U.S. Micro-Cap Stocks have been terminated outright.
What EBSI actually lets you trade
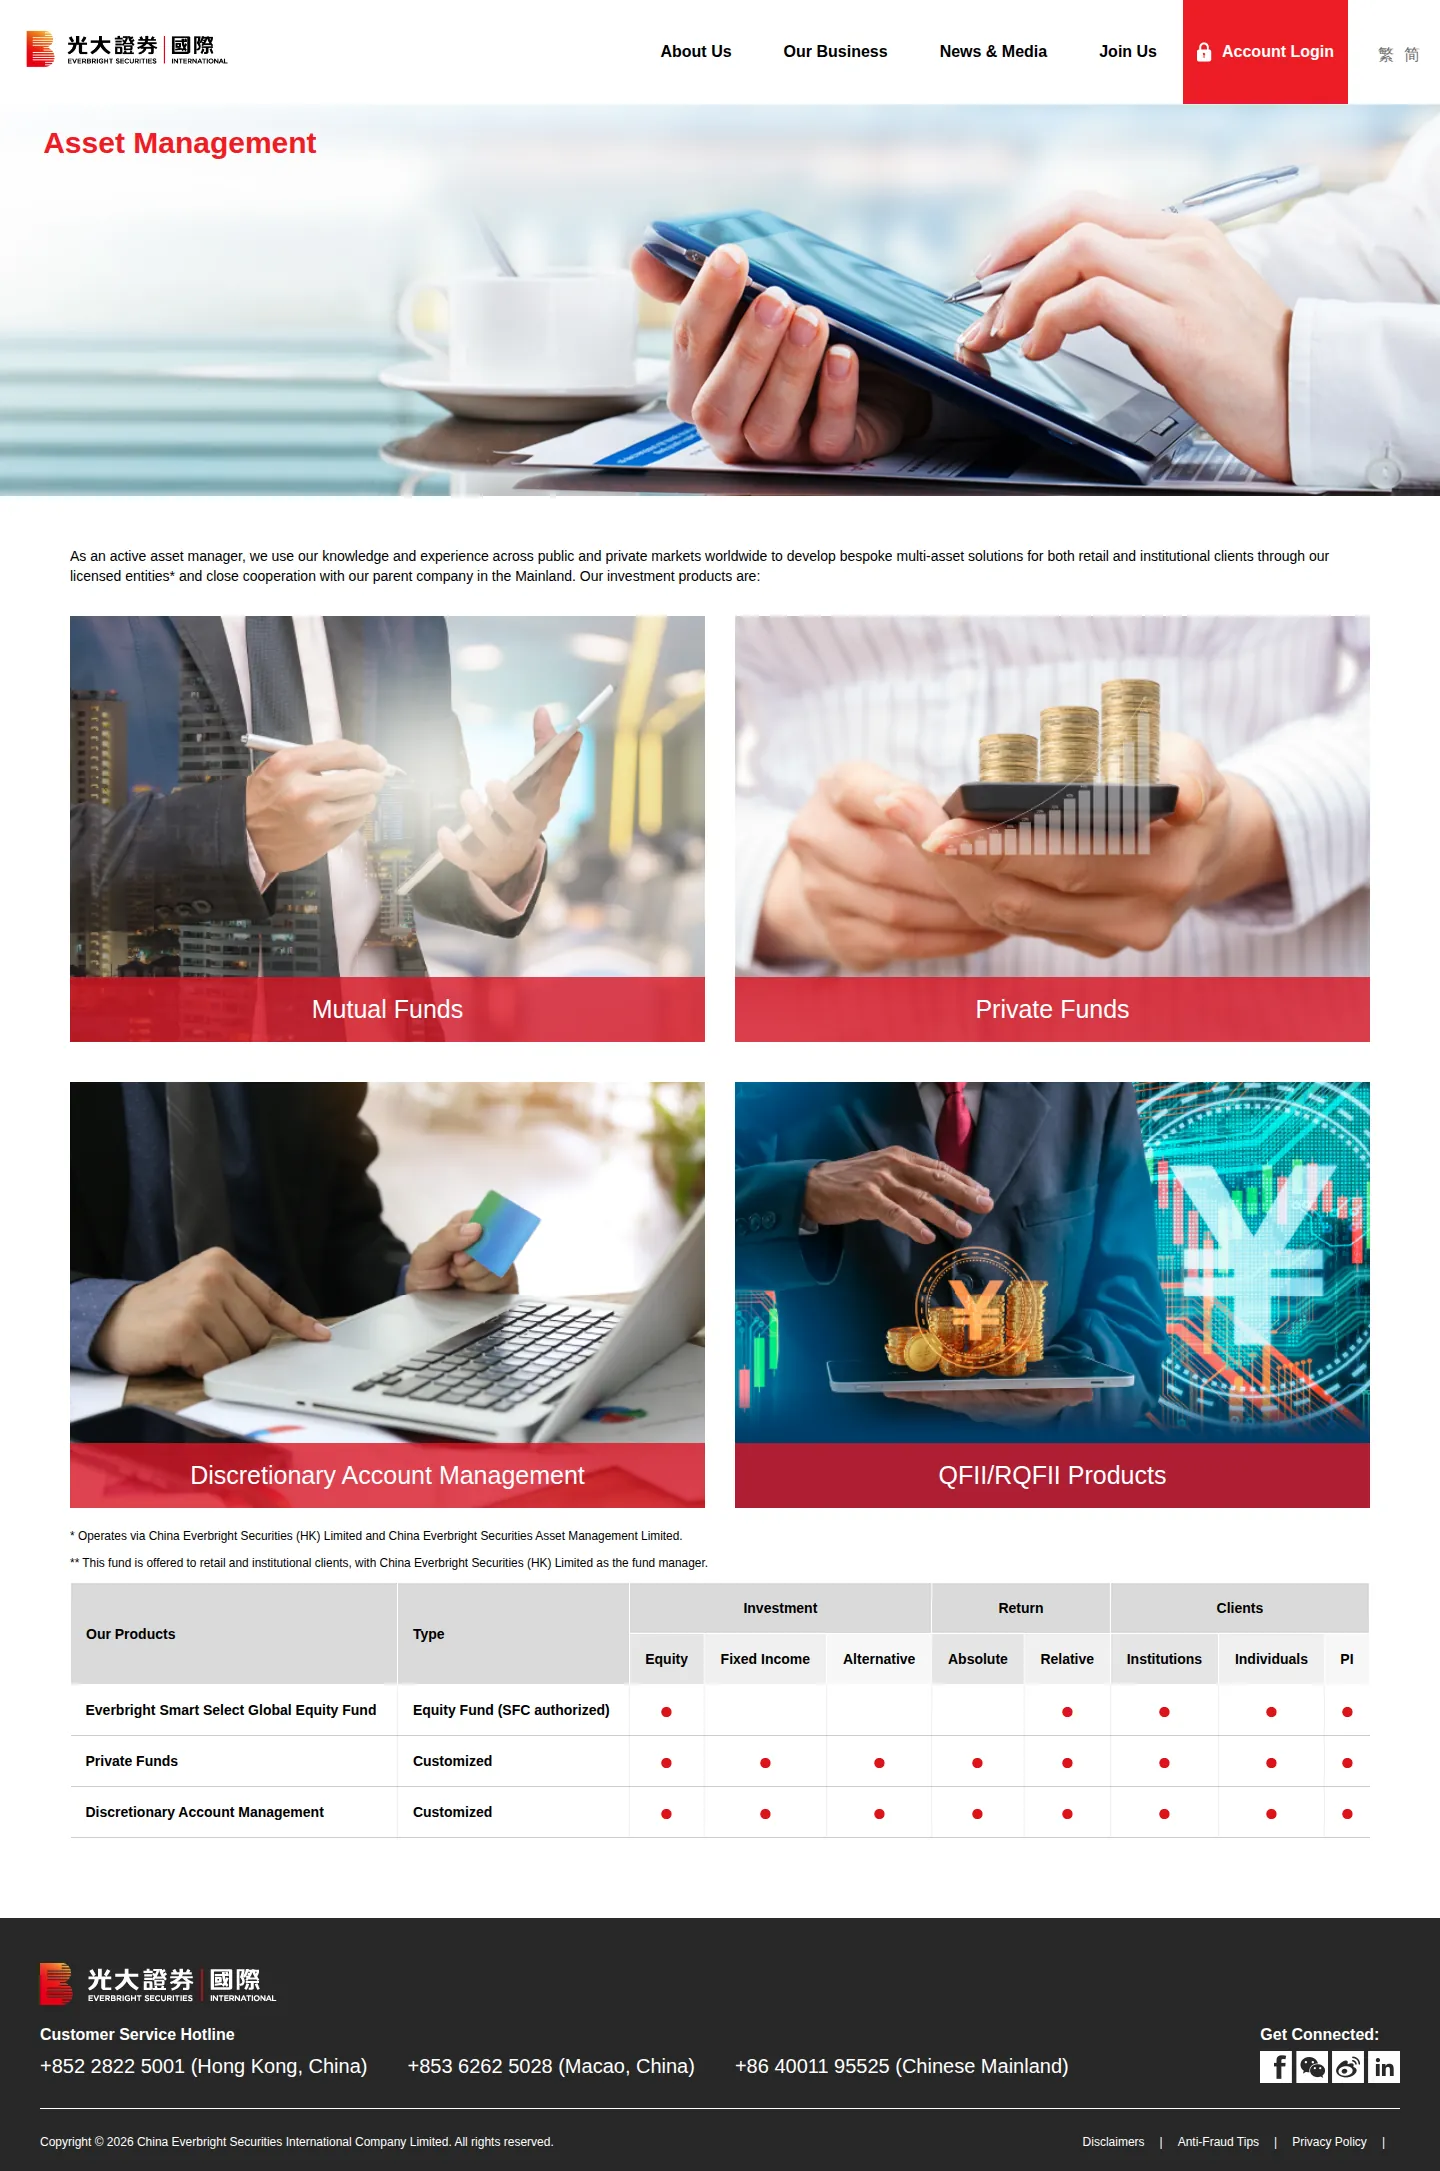
The firm’s own pages describe a fairly wide product shelf: Hong Kong equities through EBSI Direct, US stocks through UStock Pro, forex under the EBSI Forex brand, stock options and futures & options through Sharp Point Trader X, and structured products including equity-linked notes offered via Private Funds. The site advertises access to “more than 1,900 mutual funds”, including the SFC-authorized Everbright Smart Select Global Equity Fund, and to “nearly 1,400 bonds and certificates of deposit”. Private Funds extend to leveraged bond funds, private equity funds, hedge funds and structured notes, aimed at institutional, corporate and high-net-worth clients, and there are QFII/RQFII products for those with access to that scheme. Insurance is sold alongside the investment products. Two of EBSI’s own funds, the Everbright Income Focus Fund and the Everbright Greater China Opportunities Fund, were closed and de-authorized by the SFC in 2026, on 2 February and 5 May respectively, which narrows the fund lineup for anyone who was in either.
Account tiers, on the earlier review’s word only
We could not find EBSI’s own account-types, fee-schedule or risk-disclosure pages. So the tier structure here comes from the earlier published review, not from anything we fetched, and should be read that way. That review described a Cash Account from HKD 10,000 with no leverage, no short selling and no IPO financing; a Margin Account from HKD 50,000 offering leverage up to 5x, short selling and IPO financing; and a Premier Wealth tier from HKD 1,000,000 with leverage up to 10x, priority IPO financing, a dedicated manager and preferential fees. The same earlier review is the only source for the leverage figures, the deposit minimums and the IPO financing terms; none of it appears on the pages we were able to fetch from EBSI itself.
Where you’re allowed to trade from
EBSI’s own site sets out geographic limits that bind on execution, not just marketing. It does not accept account-opening registrations from investors holding PRC identity cards. Separately, effective 1 October 2026, buy (open) transactions and fund deposits are suspended for any investor physically located in Chinese Mainland, while sell (close) transactions and account inquiries stay unaffected. Anyone trading from the mainland after that date can close positions and check balances but cannot add to them or fund the account. The earlier review also noted that US resident or citizen applicants face case-by-case compliance review under FATCA restrictions, though that detail is not confirmed on EBSI’s own pages.
The terms that bind once you’re on the site
EBSI’s own legal page carries a broad liability disclaimer: “In no event will any member of the EBSI Group be liable or have any responsibility for any loss or damage of any kind, whether direct, indirect, special, consequential or incidental, resulting from access or use of, or inability to access or use, this site or any sites or pages linked to this site… even if any member of the EBSI Group has been advised of or should have been aware of the possibility thereof.” There is no stated cap or carve-out for the firm’s own negligence. The same page states that site information is provided “as is” and “as available,” with no warranty of accuracy or completeness, and that if the firm’s Additional Disclaimer ever conflicts with its other disclaimers, “such inconsistency should be resolved in favor of the provisions affording the broadest protection to EBSI Group as permitted under the applicable laws and regulatory requirements.” The legal page also puts the burden of legal compliance on the visitor: anyone relying on the site “must satisfy himself that he is not subject to any local requirement which restricts or prohibits him from doing so,” and simply accessing the site is treated as agreement to all of the above, including additional terms not necessarily shown to the visitor at that point.
Deposits and the execution gaps we found
EBSI’s own site states that it will no longer support deposits via PPS, effective 1 January 2026. Beyond that, payment method details (wire transfer timing, local transfer, checks, and the absence of credit cards or e-wallets) come from the earlier review rather than from EBSI’s own fee or payments pages, which we could not locate. What we can attribute directly to EBSI’s own site is the standing order-type gap on UStock Pro and the platform migration on the options and futures side, both of which affect how and when a position can actually be entered or closed, not just where the account is opened.
We scored this section 6.6/10 for platform and 2/10 for fees. Our previous review of EBSI scored 4.8 overall against 3.8 before; the platform side benefits from EBSI’s own pages documenting a working, if fragmented, set of trading apps across stocks, options, futures and FX, while the fee score stays low because the account minimums, leverage tiers and fee structure all rest on the earlier review rather than on any fee schedule EBSI itself publishes. That gap between what the firm’s own site shows and what the account terms actually cost is the main reason the fees mark stays where it is.
Account Types
Our earlier review describes EBSI running three account tiers rather than a single account: a Cash Account asking for a minimum deposit of HKD 10,000, carrying no leverage, and blocking short selling and IPO financing, leaving basic research as the only extra; a Margin Account stepping the minimum up to HKD 50,000, adding leverage of up to 5x, permitting short selling, opening IPO financing, and adding limited advisory support on top of standard research; and a Premier Wealth tier sitting at a HKD 1,000,000 minimum, raising leverage to 10x, giving priority IPO financing, a dedicated manager, what the earlier review called full advisory and premium research, and a preferential fee structure with extra platform tools. We could not verify any of these minimums, leverage caps, or fee terms against a page EBSI itself publishes.
That last point matters more than usual here. We went looking for a dedicated account-types page, a fee schedule, a risk-disclosure document or terms and conditions, asking for more than 30 addresses on ebshk.com, and every one came back 404 or empty. EBSI does not appear to publish a page we could fetch that lays out what its accounts cost or what they unlock. The tier structure above, and every figure attached to it, comes only from the earlier review, restated in our own words rather than quoted, because we did not read the document it describes.
There is a further reason to hold those figures loosely. The same earlier review points readers to “BOCOM’s Official Website” for more on EBSI, BOCOM being Bank of Communications, a separate company. Text that misattributes the firm it is reviewing to an outside company reads as templated rather than checked specifically against EBSI, and that casts doubt on the account minimums and leverage figures it also carries. We are repeating them because they are the only account-tier numbers available, not because we have confirmed them.
What the earlier review said EBSI charges to open an account
| Tier | Minimum deposit | Leverage | Notable features |
|---|---|---|---|
| Cash Account | HKD 10,000 | None | No short selling, no IPO financing, basic research |
| Margin Account | HKD 50,000 | Up to 5x | Short selling, IPO financing, limited advisory, standard research |
| Premier Wealth | HKD 1,000,000 | Up to 10x | Priority IPO financing, dedicated manager, premium research, preferential fees |
The same source describes an account opening fee waived for an initial period, a reduced commission rate for new clients in their first three months, and preferential IPO financing rates for accounts it calls qualified. All three read as promotional terms rather than a standing price list, and none of them appears on a page EBSI itself makes reachable, so we cannot say whether they are still running or what “qualified” means in practice.
What EBSI’s own pages show instead
Away from the account-tier question, EBSI’s own site does describe a wider product shelf that any of these accounts would presumably sit on top of: more than 1,900 mutual funds, nearly 1,400 bonds and certificates of deposit, and a Private Funds line covering leveraged bond funds, private equity funds, hedge funds and structured notes aimed at institutional, corporate and high-net-worth clients. EBSI Private, a customised wealth management service for high-net-worth clients, has been running since 2011 according to the firm’s own about page, which lines up loosely with the Premier Wealth description in the earlier review but is not the same document. Two of EBSI’s own funds, the Everbright Income Focus Fund and the Everbright Greater China Opportunities Fund, were de-authorized by the SFC in 2026, on 2 February and 5 May respectively, which narrows the fund shelf an account holder would actually be choosing from today.
Our previous score for this broker was 3.8 out of 10; this review scores it 4.8 out of 10. That change is ours, driven by the criteria and evidence available to this review, not a claim that EBSI’s accounts or pricing have changed. Fees score 2 out of 10 here specifically because there is no fee schedule or account-types page on ebshk.com that we could fetch and check, and the only pricing detail available, the tiered minimums and the promotional waivers, comes from a review whose own outbound references point to the wrong company. A reader who wants to know what an EBSI account actually costs today has nothing from the firm itself to check that against.
Negative Balance Protection
EBSI publishes no risk-disclosure statement, client agreement or margin-call policy that we could find on ebshk.com. That leaves no firm-published document setting out what happens to a client’s account when a margin position moves against them, whether a stop-out level applies, or whether a client can end up owing EBSI more than they deposited. Everything below is what we could find standing in for that gap, and none of it is a substitute for it.
The leverage tiers, as the earlier review described them
An earlier published review described three account tiers, and we are restating its figures here rather than treating them as EBSI’s own words, since we did not read a page that confirms them. A Cash Account, with a stated minimum of HKD 10,000, was described as carrying no leverage, no short selling and no IPO financing. A Margin Account, with a stated minimum of HKD 50,000, was described as carrying leverage up to 5x with short selling and IPO financing permitted. A Premier Wealth tier, with a stated minimum of HKD 1,000,000, was described as carrying leverage up to 10x. None of these minimums or leverage multiples appear on any EBSI page we fetched, so they should be read as what the earlier review reported, not as a figure EBSI currently publishes. The same earlier review also pointed readers toward “BOCOM’s Official Website”, which is Bank of Communications, a separate company, for more information on EBSI, and closed by recommending a competing broker for MT5 support, which is why we are treating its numeric claims about leverage and account minimums with caution rather than repeating them as fact.
What EBSI’s website disclaimers actually cover
The one liability document we could read on ebshk.com is a general website-use disclaimer, not a margin or negative-balance policy, and it is worth being precise about the difference. Under the heading “Limitation of Liability” it states: “In no event will any member of the EBSI Group be liable or have any responsibility for any loss or damage of any kind, whether direct, indirect, special, consequential or incidental, resulting from access or use of, or inability to access or use, this site or any sites or pages linked to this site… even if any member of the EBSI Group has been advised of or should have been aware of the possibility thereof.” That clause disclaims liability for loss arising from using the website itself, with no stated cap and no carve-out for EBSI’s own negligence; it says nothing about what happens when a leveraged position runs against a client. Under “Additional Disclaimer”, the same page states that any inconsistency between that disclaimer and the site’s other disclaimers “should be resolved in favor of the provisions affording the broadest protection to EBSI Group as permitted under the applicable laws and regulatory requirements”, so where EBSI’s own documents conflict, the conflict is resolved in EBSI’s favor, not the client’s. We read these on the firm’s legal page. Neither clause tells a reader what triggers a margin call, what stop-out level applies, or whether a shortfall becomes a debt owed to EBSI, because that document is about site content and linked pages, not trading positions.
The SFC register on the entities that would carry this risk
The Hong Kong SFC Public Register of Licensed Persons and Registered Institutions shows China Everbright Securities (HK) Limited, the principal operating company named on EBSI’s contact page, holding CE reference AAW536, licensed for Type 1, Type 6 and Type 9 activities, each shown as active. The same register entry records two public disciplinary actions against this entity: a Public Reprimand on 16 June 2022 and a Fine on 16 June 2022, and the licence carries two licensing conditions. The register shows CES Forex (HK) Limited, the group’s foreign exchange entity, holding CE reference ACI995 for Type 3, Leveraged Foreign Exchange Trading, active, with one licensing condition attached and no public disciplinary action recorded against it. Neither entry sets out margin or negative-balance terms; a register records licensing status and disciplinary history, not a firm’s internal drawdown rules. We also searched 1,441 warning-list entries mirrored from CySEC, the FCA and FSC Mauritius, and EBSI does not appear on any of them, though that check covers only the three regulators we mirror, not a global sweep.
Taken together, the picture is a set of leverage figures we could not confirm against EBSI’s own pages, a website disclaimer that protects EBSI’s liability for site content rather than trading losses, and a regulator record that confirms licensing and one disciplinary history but says nothing about margin treatment. A prospective client asking what happens if a leveraged position moves sharply against them, and whether they could owe EBSI money beyond their deposit, has no EBSI-published document to answer that question with.
Trading Instruments
EBSI’s product range comes almost entirely from the firm’s own site rather than our earlier review, which is a stronger footing than most sections of this catalogue get. The firm’s homepage lists equities, US stocks, mutual funds, bonds and certificates of deposit, forex, structured products, insurance, private funds, stock options and futures & options, and QFII/RQFII products.
What EBSI actually lists as tradeable
The firm’s own pages put a number on two of these ranges: “more than 1,900 mutual funds” and “nearly 1,400 bonds and certificates of deposit”. Equities trade through EBSI Direct, the web-based platform the firm’s about page says launched in 2000 under the earlier name “SHK Direct”. US stocks route through a separate platform, UStock Pro, and stock options and futures & options route through Sharp Point Trader X, which the firm’s site says is migrating from a prior Sharp Point application effective 27 April 2026. Forex is branded separately as EBSI Forex. Private Funds cover leveraged bond funds, private equity funds, hedge funds and structured notes, and the firm’s accounts page restricts these to institutional, corporate and high-net-worth clients. QFII/RQFII products are also listed on that accounts page, tied to the RMB Qualified Foreign Institutional Investor and Qualified Foreign Institutional Investor schemes.
Structured products get one line on the homepage (“Diversify investment with structured products”), and equity-linked notes are offered specifically through Private Funds. Insurance is listed as a product line (“Build and protect assets with insurance”) but the evidence gathered here does not go further than that single phrase.
Where the range is thinner than it looks
Two of EBSI’s own funds were closed and de-authorized by the SFC in 2026: the Everbright Income Focus Fund on 2 February 2026 and the Everbright Greater China Opportunities Fund on 5 May 2026. That is a direct contraction in the firm’s own fund lineup, not a general market comment, and it happened this year.
UStock Pro, the platform carrying the US stocks range, has had Market Orders, Stop Limit Orders, Stop Market Orders and post-market order placing unavailable since 6 October 2025, and trading services for U.S. Low Price and U.S. Micro-Cap Stocks have been terminated outright. A reader who signs up expecting the full order-type range on US equities is not getting what the platform currently supports.
The account tiers, minimum deposits and leverage figures (Cash Account at HKD 10,000 with no leverage, Margin Account at HKD 50,000 with leverage up to 5x, Premier Wealth at HKD 1,000,000 with leverage up to 10x) come from our earlier review, not from any EBSI page fetched for this rewrite. We could not locate a dedicated account-types, fee-schedule or platforms page on ebshk.com. That means the specific leverage caps and short-selling and IPO-financing terms attached to each tier are second-hand and unconfirmed against the firm’s own documentation, not something we read ourselves.
Access restrictions that cut into the advertised range
EBSI’s own site states it does not accept account opening registrations from investors holding PRC identity cards. Separately, the firm’s site states that buy (open) transactions and fund deposits will be suspended when the investor is physically in Chinese Mainland, effective 1 October 2026, while sell (close) transactions and account inquiries remain unaffected. Anyone assessing the “forex” or “equities” range against their own location should weigh this restriction rather than the general product list above.
The regulation score for this review is 7, built on Hong Kong SFC records for the group’s operating entities rather than on ebshk.com itself; several of those SFC licences (Type 1, Type 2, Type 3, Type 4, Type 6, Type 9) sit behind separate legal entities within the EBSI Group, which is worth keeping in mind when matching a specific product, like futures & options or FX, to the licence that actually covers it.
Education & Analysis
This review scores EBSI 4.8/10, up from a previous 3.8/10. That move is ours, not the firm’s: the earlier score used different criteria, and this pass rests on what the firm’s own site pages, the SFC register and the warning-list search actually show, weighted differently across the same categories. Platform scores 6.6/10, the strongest of the five, on the strength of a genuinely wide bench of named applications; support sits at 4.3, fees at 2, and both drag the overall figure down even where the tools themselves are not in question.
What EBSI actually runs
EBSI’s own about page names EBSI Direct as a web-based straight-through online stock trading platform launched in 2000 under the name “SHK Direct,” described there as one of the first platforms of its kind in Hong Kong. Alongside it, the firm’s Milestones page dates the launch of a newer mobile application, “EBSI GO!,” to 2024, describing it as “charting new ground in wealth management services.” Our earlier review gives a 2025 launch year for the same app; since that figure came to us from an earlier publication rather than a page we fetched, and it conflicts with what EBSI’s own Milestones page states, we treat the firm’s own dating as the one to rely on.
The firm’s root page lists three further named applications. eMO!, a mobile trading app introduced in 2011 for DIY investors, is having its basic real-time Hong Kong stock quote service changed from 1 July 2026, with mandatory app updates tied to that change. Sharp Point Trader X is an upgraded mobile application for stock options and futures & options, migrating clients off the prior Sharp Point application effective 27 April 2026. UStock Pro handles U.S. stock trading, and on that platform the firm’s root page states that Market Orders, Stop Limit Orders, Stop Market Orders and post-market order placing have been temporarily unavailable since 6 October 2025. A reader wanting to place any of those order types on U.S. stocks through EBSI would not currently be able to on that platform, per the firm’s own page.
Instruments reachable through these platforms
The firm’s root page advertises access to “more than 1,900 mutual funds” and “nearly 1,400 bonds and certificates of deposit.” The same page names structured products, insurance, and FX trading under the EBSI Forex brand as available lines. Separately, the firm’s accounts page lists Private Funds, covering leveraged bond funds, private equity funds, hedge funds and structured notes for institutional, corporate and high-net-worth clients, and QFII/RQFII products for qualifying investors. Stock options and futures & options are traded through the Sharp Point Trader X app named above.
Against that breadth, one fact cuts the other way: EBSI’s own accounts page shows that two of the firm’s own funds, the Everbright Income Focus Fund and the Everbright Greater China Opportunities Fund, were closed and formally de-authorized by the SFC in 2026, on 2 February and 5 May respectively. Anyone holding, or considering, either of those specific funds should treat that as current and firm-sourced, not carried over from an older snapshot.
What we could not verify about EBSI’s tools
We were unable to locate a dedicated platforms page, risk-disclosure page, terms-and-conditions or client-agreement, or fee-schedule page anywhere on ebshk.com. That means claims elsewhere about margin treatment on the platforms above, negative-balance handling, or platform-specific fee schedules could not be checked against a page the firm publishes. Where our earlier review gives numeric detail on leverage tiers by account (Cash Account with no leverage, Margin Account up to 5x, Premier Wealth up to 10x) or on account minimums, that detail came to us from the earlier review rather than from a page we fetched, and none of the platform pages we did reach corroborate or contradict it.
The legal page we did reach carries terms that touch directly on use of the firm’s site and, by extension, any of the platforms above accessed through it. Under “No Warranty,” information on the site is provided “as is” and “as available,” subject to change without notice, with EBSI Group disclaiming warranties of merchantability or fitness for a particular purpose. Under “Limitation of Liability,” the same page states that “In no event will any member of the EBSI Group be liable or have any responsibility for any loss or damage of any kind, whether direct, indirect, special, consequential or incidental, resulting from access or use of, or inability to access or use, this site or any sites or pages linked to this site… even if any member of the EBSI Group has been advised of or should have been aware of the possibility thereof.” That clause covers the platforms themselves, not just the marketing pages around them, and it sets no cap and carves out no exception for EBSI’s own negligence. A client whose order failed to route, or who lost access to a trading tool mid-session, would be relying on a document that disclaims responsibility for exactly that outcome.
Special Offers
We could not locate a promotions page anywhere on ebshk.com. EBSI publishes no dedicated fee-schedule, account-types or terms-and-conditions page. That absence does not tell us EBSI runs no promotions; it tells us we did not find a page that lists them. What follows on discounts and preferential rates is second-hand: it comes from the earlier published review of EBSI that this catalogue is rewriting, not from anything we read on the firm’s own site, and it carries that caveat throughout.
What the earlier review reported about EBSI’s offers
The earlier review described three separate promotional items. It said the account opening fee is waived for an initial period, framed as a promotional offer, without stating how long that period runs or which of EBSI’s account tiers it covers. It said the commission rate is reduced for new clients for the first three months, again without a figure for either the standard rate or the discounted one. And it said EBSI offers preferential IPO financing rates to “qualified accounts,” without defining what qualifies an account for that rate or what the preferential rate actually is.
None of these three items comes with an expiry date, a minimum deposit or trade size, or a sign-up mechanism in the source material available to us. A reader who wants the actual numbers behind “waived,” “reduced,” or “preferential” has nothing here to check them against, and we have no EBSI page of our own to point to instead.
Where this sits against EBSI’s account tiers
The same earlier review lists three account tiers: a Cash Account at a HKD 10,000 minimum with no leverage and no IPO financing, a Margin Account at HKD 50,000 with IPO financing available, and a Premier Wealth tier at a HKD 1,000,000 minimum that it describes as carrying “priority IPO financing” and a “preferential fee structure” on top of a dedicated relationship manager and premium research access. That pairing suggests the IPO financing discount and any fee preference are tied to which tier a client funds into, rather than being a time-limited promotion open to any new client. We cannot confirm the tier definitions, the deposit thresholds, or the fee structure from EBSI’s own pages, so this is reported as what the earlier review described, not as a term we verified.
Set against the rest of the evidence, the promotional claims are the least verifiable part of this review. We could confirm EBSI’s regulatory footprint directly against the Hong Kong SFC register, entity by entity, and we ran EBSI’s name against 1,441 warning-list entries mirrored from CySEC, the FCA and the FSC Mauritius with no match. Neither of those checks touches pricing or promotions, and on promotions specifically we have no register, no firm page, and no fee schedule to check the earlier review’s numbers against.
Opening an Account
We could not find a step-by-step account-opening page on ebshk.com. The site is built on .php paths, and the standard paths we requested for a risk-disclosure statement, a terms-and-conditions or client-agreement document, a fee schedule and an account-types page each returned a 404 or an empty body. What follows is built from the pages that do exist: the firm’s own restrictions notices, its payment-method updates, its site-wide legal terms, and an account-tier breakdown carried over from an earlier review of EBSI and have not independently verified against a fetched EBSI page.
Who EBSI will not open an account for
EBSI’s own site states plainly that it does not accept account opening registrations from investors holding PRC identity cards. That is a blanket exclusion on the identity document itself, not a location test.
Location is handled separately and more narrowly. From 1 October 2026, buy (open) transactions and fund deposits are suspended for Chinese Mainland investors when they are physically in Chinese Mainland, while sell (close) transactions and account inquiries stay available to them. So a Mainland-based client is not locked out of an existing account, only stopped from adding money or opening new positions while physically there.
An earlier review of EBSI reported that US resident and citizen applicants go through a case-by-case compliance review because of FATCA, rather than an automatic bar. We have not seen this stated on EBSI’s own pages and report it as that earlier review’s account, not EBSI’s.
The account tiers an earlier review described
That same earlier review set out three EBSI account tiers, and since we could not locate EBSI’s own account-types page to check the figures, we report them here as what the earlier review said rather than as EBSI’s own terms:
- A Cash Account that the review put at a minimum deposit of HKD 10,000, with no leverage, no short selling and no IPO financing.
- A Margin Account that the review put at a minimum deposit of HKD 50,000, with leverage up to 5x, short selling and IPO financing available, and standard research access.
- A Premier Wealth tier with a stated minimum deposit of HKD 1,000,000, leverage up to 10x, priority IPO financing, a dedicated relationship manager and premium research.
Separately, on EBSI’s own accounts page, Private Funds (leveraged bond funds, private equity funds, hedge funds, structured notes) and QFII/RQFII products are described as directed at institutional, corporate and high-net-worth clients rather than a walk-in retail signup.
Funding an EBSI account once it is open
EBSI’s own site gives one hard deadline here: it will no longer support deposits via PPS from 1 January 2026, so anyone relying on that method needs another route in place before then. Our earlier review described wire transfer as taking 1-2 days to clear as a deposit and 1-3 days to clear as a withdrawal, with bank charges applying, and local transfer between Hong Kong banks as same-day for deposits and next-day for withdrawals with no fee stated. That same review said check deposits take 2-3 days and are not accepted for withdrawal, and that EBSI does not support credit card or e-wallet funding at all. None of this is confirmed against a fetched EBSI fee or payments page, since none was reachable.
What signing up actually commits a visitor to
EBSI’s own site terms, under the heading “Important,” state that “by accessing this site and any of its pages you agree to the terms and conditions set out above and to any additional terms and conditions applicable to any specific part or content of this site.” That means browsing the site is treated as agreement to terms that may not be shown to the visitor at that point, before any account application form is reached. The same terms, under “Use of Site,” put the burden on the visitor to work out whether using the site or its services is even lawful where they are: anyone who “intends to respond to or rely upon the information on this site must satisfy himself that he is not subject to any local requirement which restricts or prohibits him from doing so.” Under “Additional Disclaimer,” any inconsistency between that document and EBSI’s other disclaimers is resolved “in favor of the provisions affording the broadest protection to EBSI Group,” not the applicant. We read these because they are the only account-adjacent legal terms we could find published; a dedicated client agreement covering margin treatment, negative-balance liability or account closure was not among the pages we could reach.
Deposits & Withdrawals
We looked for EBSI’s own fee schedule, account-types page, and payment terms before writing this section. We could not find one. What follows is built from the pages we did fetch, plus specific payment and account figures carried over from the earlier review of this firm, marked where that is the case, because EBSI has not published them on the site we crawled.
What EBSI’s own site says about moving money
EBSI’s site states that the firm will no longer support deposits via PPS, effective 1 January 2026, without naming a replacement channel on the page we read. The same site sets out two restrictions that bear directly on who can fund or withdraw from an account. First, EBSI does not accept account-opening registrations from investors holding PRC identity cards. Second, effective 1 October 2026, buy (open) transactions and fund deposits are suspended for investors who are physically located in Chinese Mainland at the time, while sell (close) transactions and account inquiries stay unaffected. A client based in Chinese Mainland can therefore close a position or check a balance after that date but cannot fund the account or open a new one from there.
What the earlier review reported about deposit and withdrawal rails
Our earlier review described a wire transfer channel taking 1 to 2 days to clear a deposit and 1 to 3 days to clear a withdrawal, with bank charges applying and international transfers supported. It described a local transfer channel, limited to Hong Kong banks, clearing deposits the same day and withdrawals the next day, with no fee stated. It described a cheque deposit channel taking 2 to 3 days, with possible fees, that is not available for withdrawals at all. It also stated that EBSI does not offer credit card or e-wallet funding. We have not verified any of these figures against an EBSI page of our own, so we are reporting them as what the earlier review found rather than as EBSI’s own published terms.
Account minimums and the promotional pricing EBSI is reported to run
The same earlier review put EBSI’s entry point at a Cash Account with a HKD 10,000 minimum deposit, offering no leverage, no short selling and no IPO financing. Above that sits a Margin Account at a HKD 50,000 minimum, with leverage up to 5x, short selling and IPO financing available. At the top sits a Premier Wealth tier at a HKD 1,000,000 minimum, with leverage up to 10x, priority IPO financing, a dedicated manager and what the earlier review called a preferential fee structure. The same source described an account-opening fee waived for an initial period, a reduced commission rate for new clients running through the first three months, and preferential IPO financing rates for qualified accounts. Because none of this is confirmed on a page we fetched from ebshk.com, a prospective client should treat these figures, and in particular the promotional terms, as unverified until EBSI’s own fee schedule or account-opening documents can be checked directly.
Our previous review of EBSI scored it 3.8 out of 10; this review scores it 4.8. The fees criterion here sits at 2 out of 10, and that is the number driving most of the section above: we went looking for EBSI’s own account-opening fee, commission, and payment-processing terms and found none published on the site. A firm whose deposit and withdrawal costs cannot be checked against its own documentation scores poorly on fees regardless of what an earlier review or a promotional line item claims. The overall move to 4.8 reflects this review’s criteria and the evidence gathered now, not any change at EBSI itself.
Customer Support
Score for support moves in this review to 4.3/10. Registration channels and disciplinary history are why: China Everbright Securities (HK) Limited’s SFC licence record, confirmed on the Hong Kong SFC Public Register of Licensed Persons and Registered Institutions under CE reference AAW536, shows two public disciplinary actions against it, a public reprimand and a fine, both dated 16 June 2022, plus two licensing conditions attached to the licence. That sits alongside a contact page listing more channels than most brokers in this catalogue publish, but the channels alone do not offset a disciplinary record on the operating entity, and this review scores the two together rather than separately.
How to reach EBSI
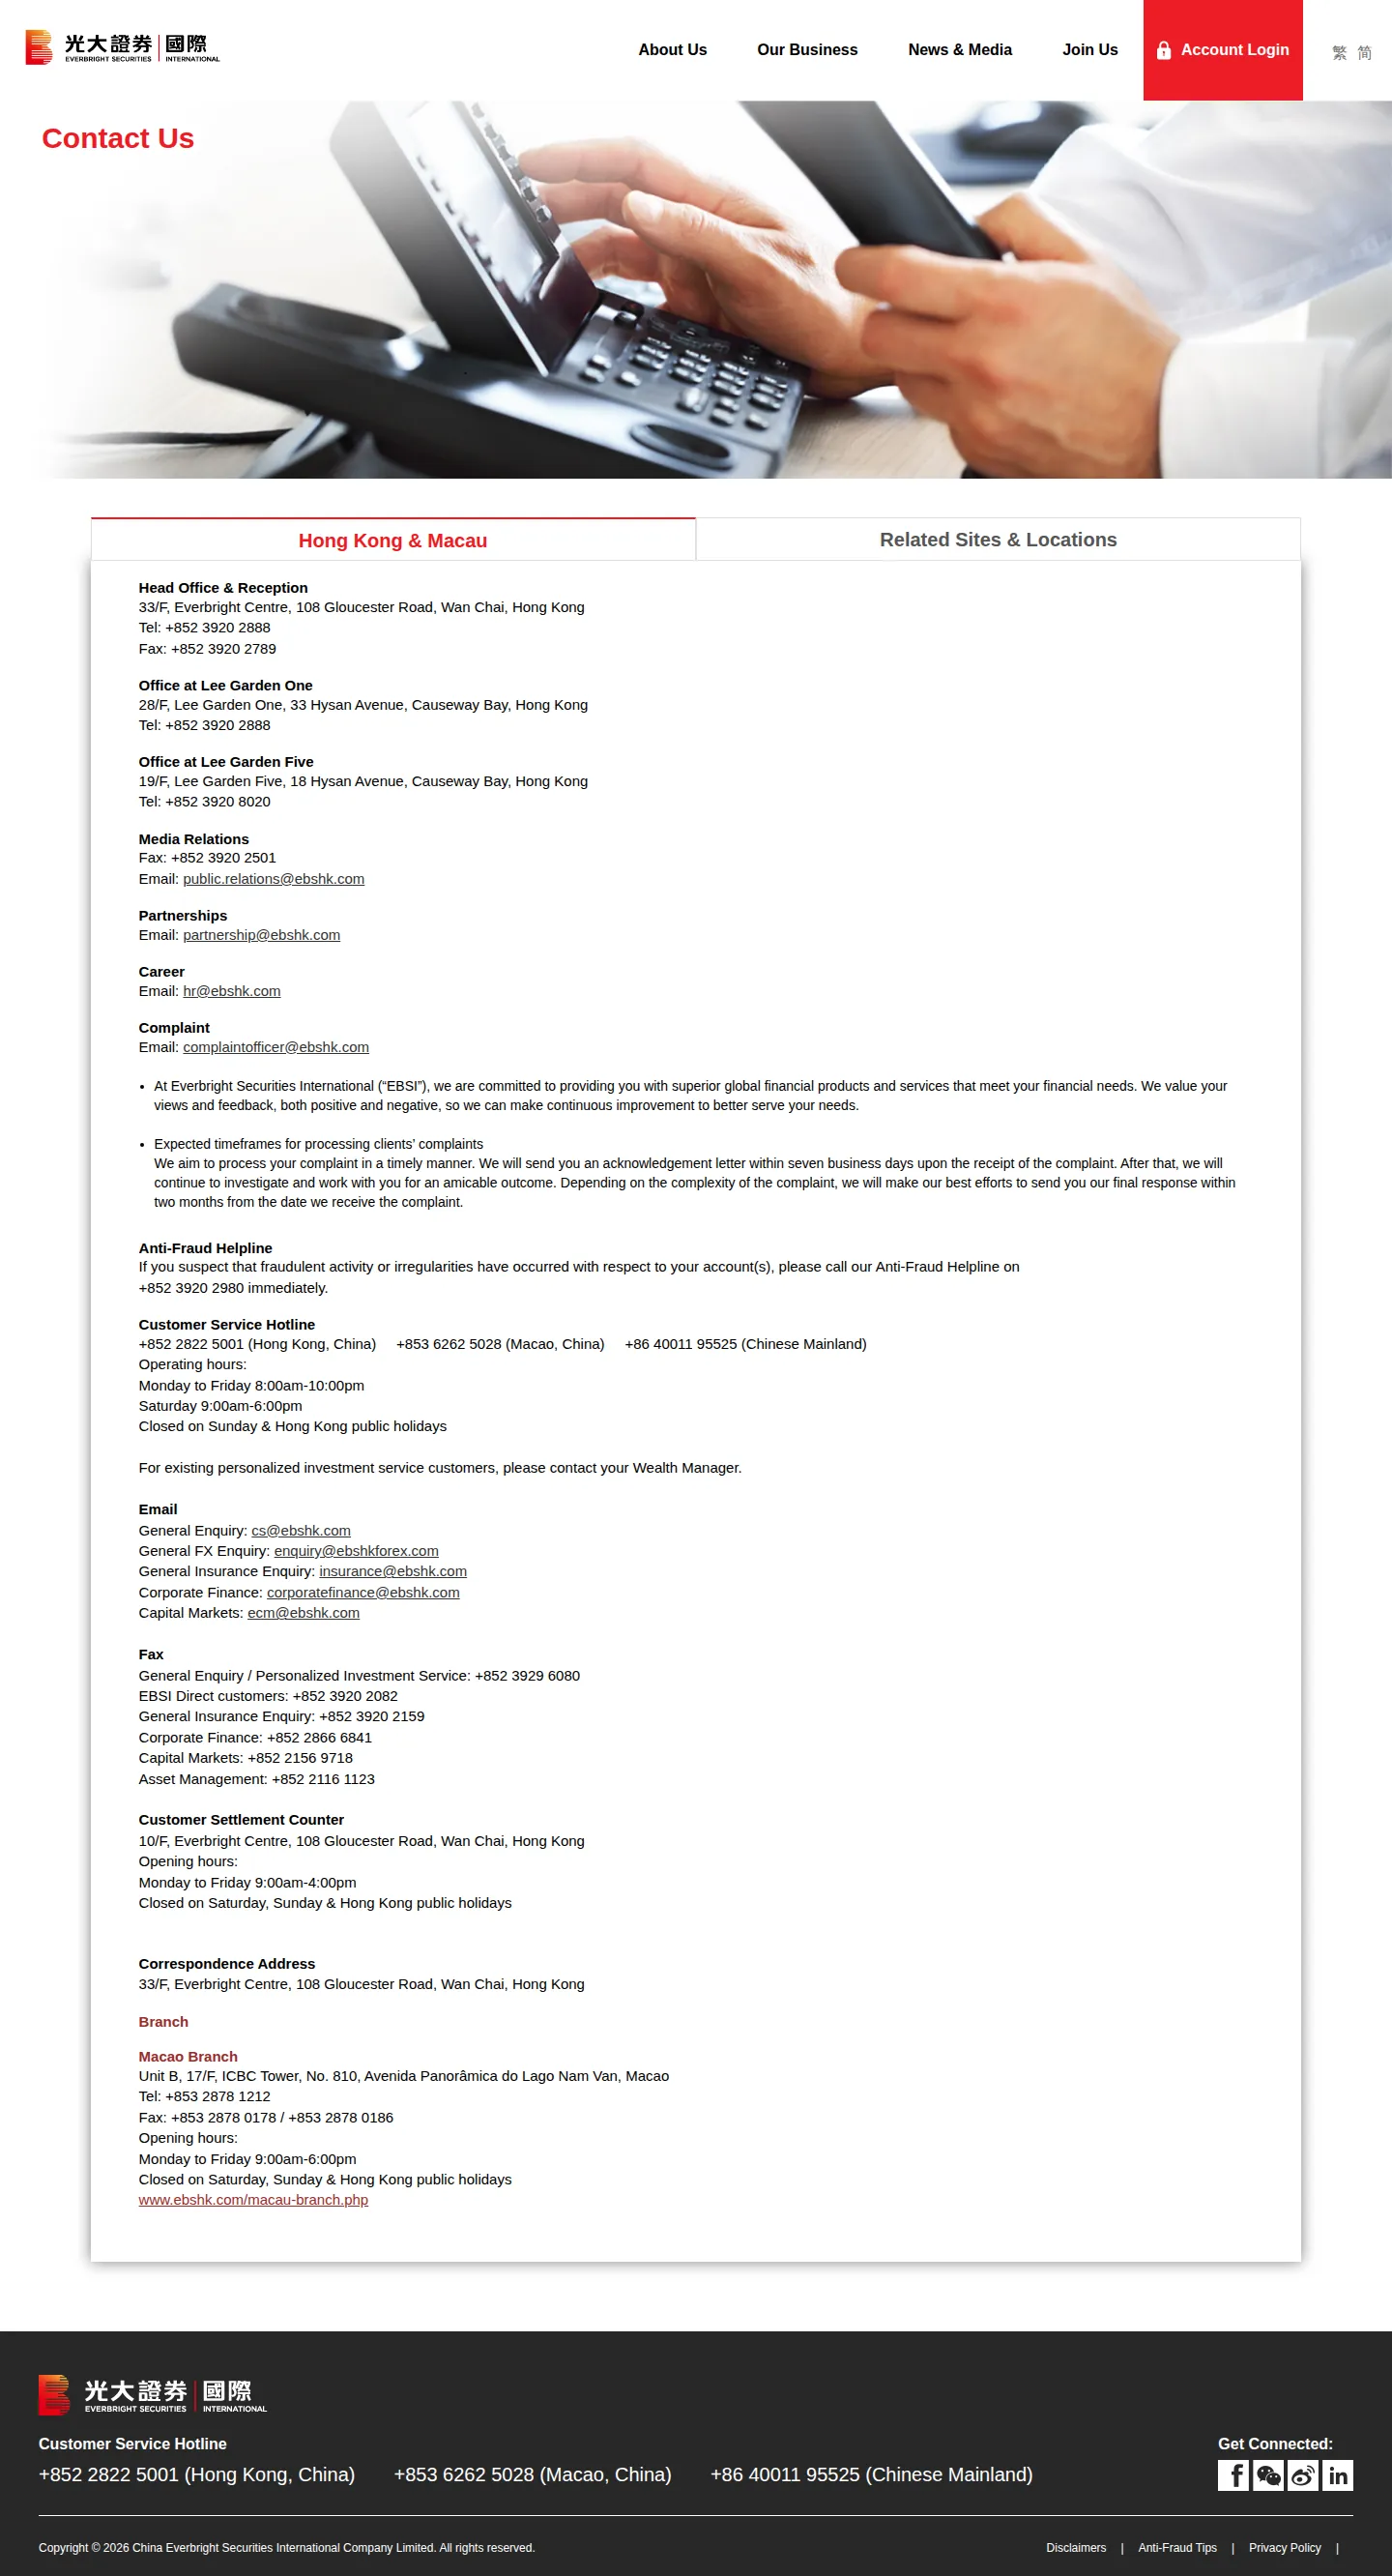
EBSI’s own contact page lists three separate customer service hotlines by market: +852 2822 5001 for Hong Kong, +853 6262 5028 for Macao, and +86 40011 95525 for Chinese Mainland callers. A general head office and reception line, +852 3920 2888, and a head office fax, +852 3920 2789, are listed alongside a dedicated anti-fraud helpline at +852 3920 2980. Email is split by function rather than routed through one inbox: cs@ebshk.com for general enquiries, enquiry@ebshkforex.com for FX, insurance@ebshk.com for insurance, corporatefinance@ebshk.com and ecm@ebshk.com for corporate finance and capital markets, hr@ebshk.com for careers, and public.relations@ebshk.com for media. A complaint specifically has its own address, complaintofficer@ebshk.com, which the contact page lists separately from the general enquiry inbox.
EBSI’s contact page also lists physical addresses: the head office and reception at 33/F, Everbright Centre, 108 Gloucester Road, Wan Chai, Hong Kong, plus two further Hong Kong offices at Lee Garden One (28/F, 33 Hysan Avenue, Causeway Bay) and Lee Garden Five (19/F, 18 Hysan Avenue, Causeway Bay). A customer settlement counter operates at 10/F of the Everbright Centre address, Monday to Friday 9:00am to 4:00pm, and a Macao branch is listed at Unit B, 17/F, ICBC Tower, Avenida Panorâmica do Lago Nam Van, Macao, with its own line at +853 2878 1212.
What we could not verify about EBSI’s service standards
We could not locate a dedicated terms-and-conditions or client-agreement page, a risk-disclosure page, or a fee-schedule page on ebshk.com. That means any claim about response times, complaint-handling procedures, or service-level commitments has no firm-published page behind it in what we fetched. What we did read is the site’s general legal disclaimer, which is not a support policy but does bear on what happens if a client runs into a problem with the site or a linked page rather than with a trade itself. Under the heading “Limitation of Liability,” the disclaimer states that “In no event will any member of the EBSI Group be liable or have any responsibility for any loss or damage of any kind, whether direct, indirect, special, consequential or incidental, resulting from access or use of, or inability to access or use, this site or any sites or pages linked to this site… even if any member of the EBSI Group has been advised of or should have been aware of the possibility thereof.” Under “No Warranty,” site information is provided “as is” and “as available,” subject to change without notice, with the EBSI Group disclaiming warranties of merchantability or fitness for a particular purpose. A separate “Additional Disclaimer” clause resolves any conflict between the firm’s own disclaimer documents in whichever direction affords the broadest protection to EBSI Group as permitted under the applicable laws and regulatory requirements, which puts the benefit of any ambiguity on the firm’s side rather than the client’s. The “Important” clause treats merely accessing the site as agreement to all of the above, including additional terms not necessarily shown to the visitor at the time.
Warning-list result and the wider regulatory picture
We searched 1,441 warning-list entries mirrored from CYSEC, the FCA and the FSC of Mauritius, and EBSI does not appear on any of them. That covers only the lists we mirror, not every regulator’s warning list worldwide, so it is a limited clean result rather than a clearance. On the licensing side, the Hong Kong SFC Public Register of Licensed Persons and Registered Institutions confirms multiple EBSI group entities as separately licensed, active, and (with the one exception above) free of recorded disciplinary action: CES Commodities (HK) Limited (CE reference AAF237), CES Forex (HK) Limited (ACI995), CES Wealth Management (HK) Limited (AAW358), and Everbright Securities Digital Finance (HK) Limited (AAC483). The disciplinary record sits specifically against China Everbright Securities (HK) Limited, the entity named as EBSI’s principal operating company and fund manager on the firm’s own contact page, which is why it carries weight in the support and reliability picture despite the group’s other entities showing a clean record.
Prohibited Countries
The register findings sit above the firm’s own site, and here the gap runs the other way: we could not find the documents that would let us write a normal version of this section. EBSI publishes no such page. There is no page naming excluded countries, no page naming excluded nationalities beyond the one restriction below, and nothing published on the firm’s own site that lists who is barred from opening an account. That absence is ours, not the firm’s: it tells a reader we did not fetch such a page, not that the firm operates with no restrictions at all.
What EBSI’s own site does say
One restriction is stated plainly on the firm’s own root page: EBSI does not accept account opening registrations from investors holding PRC identity cards. That is a specific, document-level exclusion, stated in the firm’s own words, and it applies regardless of where the applicant is physically located.
A second restriction is time-limited and location-based rather than nationality-based. Effective 1 October 2026, EBSI’s own page states that buy (open) transactions and fund deposits are suspended when the investor is physically present in Chinese Mainland. Sell (close) transactions and account inquiries are carried on functioning as before. So a Chinese Mainland-based investor already holding a position keeps the ability to exit it and check their account, but cannot add to a position or fund the account while physically in Chinese Mainland.
Together these two firm-stated restrictions point at the same population from two different angles: identity-card status and physical location. They are not identical. EBSI does not accept account opening registrations from investors holding PRC identity cards, wherever they are; a Chinese Mainland-based investor with an existing account keeps limited functionality but loses the ability to open new positions or deposit funds from 1 October 2026 onward.
What we cannot confirm about US applicants
The earlier published review reported that EBSI subjects US resident and citizen applicants to case-by-case compliance review because of FATCA restrictions. We did not read any EBSI document that says this. We are restating it here as what the earlier review reported, not as something EBSI’s own pages told us, because we could not locate a client-facing document on ebshk.com that names US persons, FATCA, or a case-by-case review process.
Where this leaves a reader checking eligibility
Nobody applying to EBSI can rely on a published, dedicated list of prohibited countries from the firm’s own site, because we could not find one to check against. The two things a reader can verify against EBSI’s own published pages are the PRC identity card exclusion and the Chinese Mainland transaction suspension taking effect 1 October 2026. Anything beyond that, including any wider set of excluded jurisdictions that a firm of this structure would typically maintain, is not something we found on ebshk.com, and we are not going to complete that picture with an assumption. A reader with residency or citizenship questions outside mainland China and the identity-card population described above would need to raise them directly with EBSI, since the firm’s own site does not answer them in a document we could locate.
Conclusion
EBSI scores 4.8 out of 10. This review replaces our earlier score of 3.8; the move is our assessment, drawn from evidence not in the earlier pass, rather than any change at the firm. Regulation is the strongest mark here, and it rests on something checkable: we searched the SFC Public Register of Licensed Persons and Registered Institutions directly and found EBSI Group entities on it by CE reference, including China Everbright Securities (HK) Limited (CE reference AAW536, licensed for Type 1, Type 6 and Type 9, all shown active) and China Everbright Research Limited (AEH589, Type 4). We also searched 1,441 warning-list entries mirrored from CySEC, the FCA and the FSC Mauritius, and EBSI matches none of them.
What pulls the regulation score down from a clean pass
The SFC register also shows two public disciplinary actions against China Everbright Securities (HK) Limited, both dated 16 June 2022: a public reprimand and a fine, and that licence carries two licensing conditions. Several other group entities carry their own conditions too. The parent company’s stock exchange listings, Shanghai Stock Exchange code 601788 and Hong Kong Stock Exchange code 6178, are listing codes rather than financial-services licences, and we hold no register entry for either exchange to check them against; the same gap applies to the RQFII qualification EBSI’s own about page describes as approved in 2016, since China’s RQFII scheme is not one of our registers. Those three are gaps in our directory, not findings about the firm one way or the other.
What EBSI charges and what we couldn’t check
Fees is the weakest mark, and the reason is documentary, not a bad number. EBSI publishes no fee schedule, account-types page, terms and conditions or risk disclosure on ebshk.com. The account tiers, minimum deposits and promotional terms circulating for EBSI, including the Cash, Margin and Premier Wealth tiers with their stated leverage caps, come from the earlier published review, not from any page we fetched, so we report them here only as what that earlier review said, not as EBSI’s own terms.
Platform and what EBSI GO! actually is
Platform is the second-strongest mark, built from EBSI’s own site. EBSI Direct, the firm’s web-based straight-through trading platform, launched in 2000 under the earlier name “SHK Direct.” The firm’s own Milestones page dates the newer EBSI GO! mobile app to 2024, which conflicts with the 2025 launch date the earlier review gave; where the two disagree, the firm’s own page is the one we trust. Alongside those, eMO!, Sharp Point Trader X and UStock Pro round out the mobile lineup, though UStock Pro’s Market Orders, Stop Limit Orders, Stop Market Orders and post-market order placing have been unavailable since 6 October 2025, and PPS deposits stop being supported from 1 January 2026.
Support and reviews
Support draws on a genuinely long channel list, hotlines for Hong Kong, Macao and Chinese Mainland, a head office line, an anti-fraud helpline, a named complaint officer’s email, and physical offices across Wan Chai and Causeway Bay, but the score sits at 4.3 because none of that documents actual response times or service quality. Reviews is held down by what the earlier text itself reveals: it points readers to “BOCOM’s Official Website,” a different bank entirely, for more on EBSI, and closes by recommending a competing broker, BDSwiss, for MT5 support, both signs the earlier review wasn’t written specifically for this firm.
The site’s own legal terms
EBSI’s website legal page, which we read directly, disclaims liability for “any loss or damage of any kind, whether direct, indirect, special, consequential or incidental, resulting from access or use of, or inability to access or use, this site or any sites or pages linked to this site,” with no stated cap or carve-out, and states that merely accessing the site counts as agreement to those terms “and to any additional terms and conditions applicable to any specific part or content of this site.” That governs website use, not a trading agreement, since no client agreement or risk disclosure was reachable on the firm’s own domain.
EBSI holds active Hong Kong SFC licences across multiple group entities, verified on the SFC register, and turns up on none of 1,441 mirrored warning-list entries, but scores 4.8 out of 10 because its own site publishes no fee schedule, account terms, or risk disclosure that we could check.
What we saw
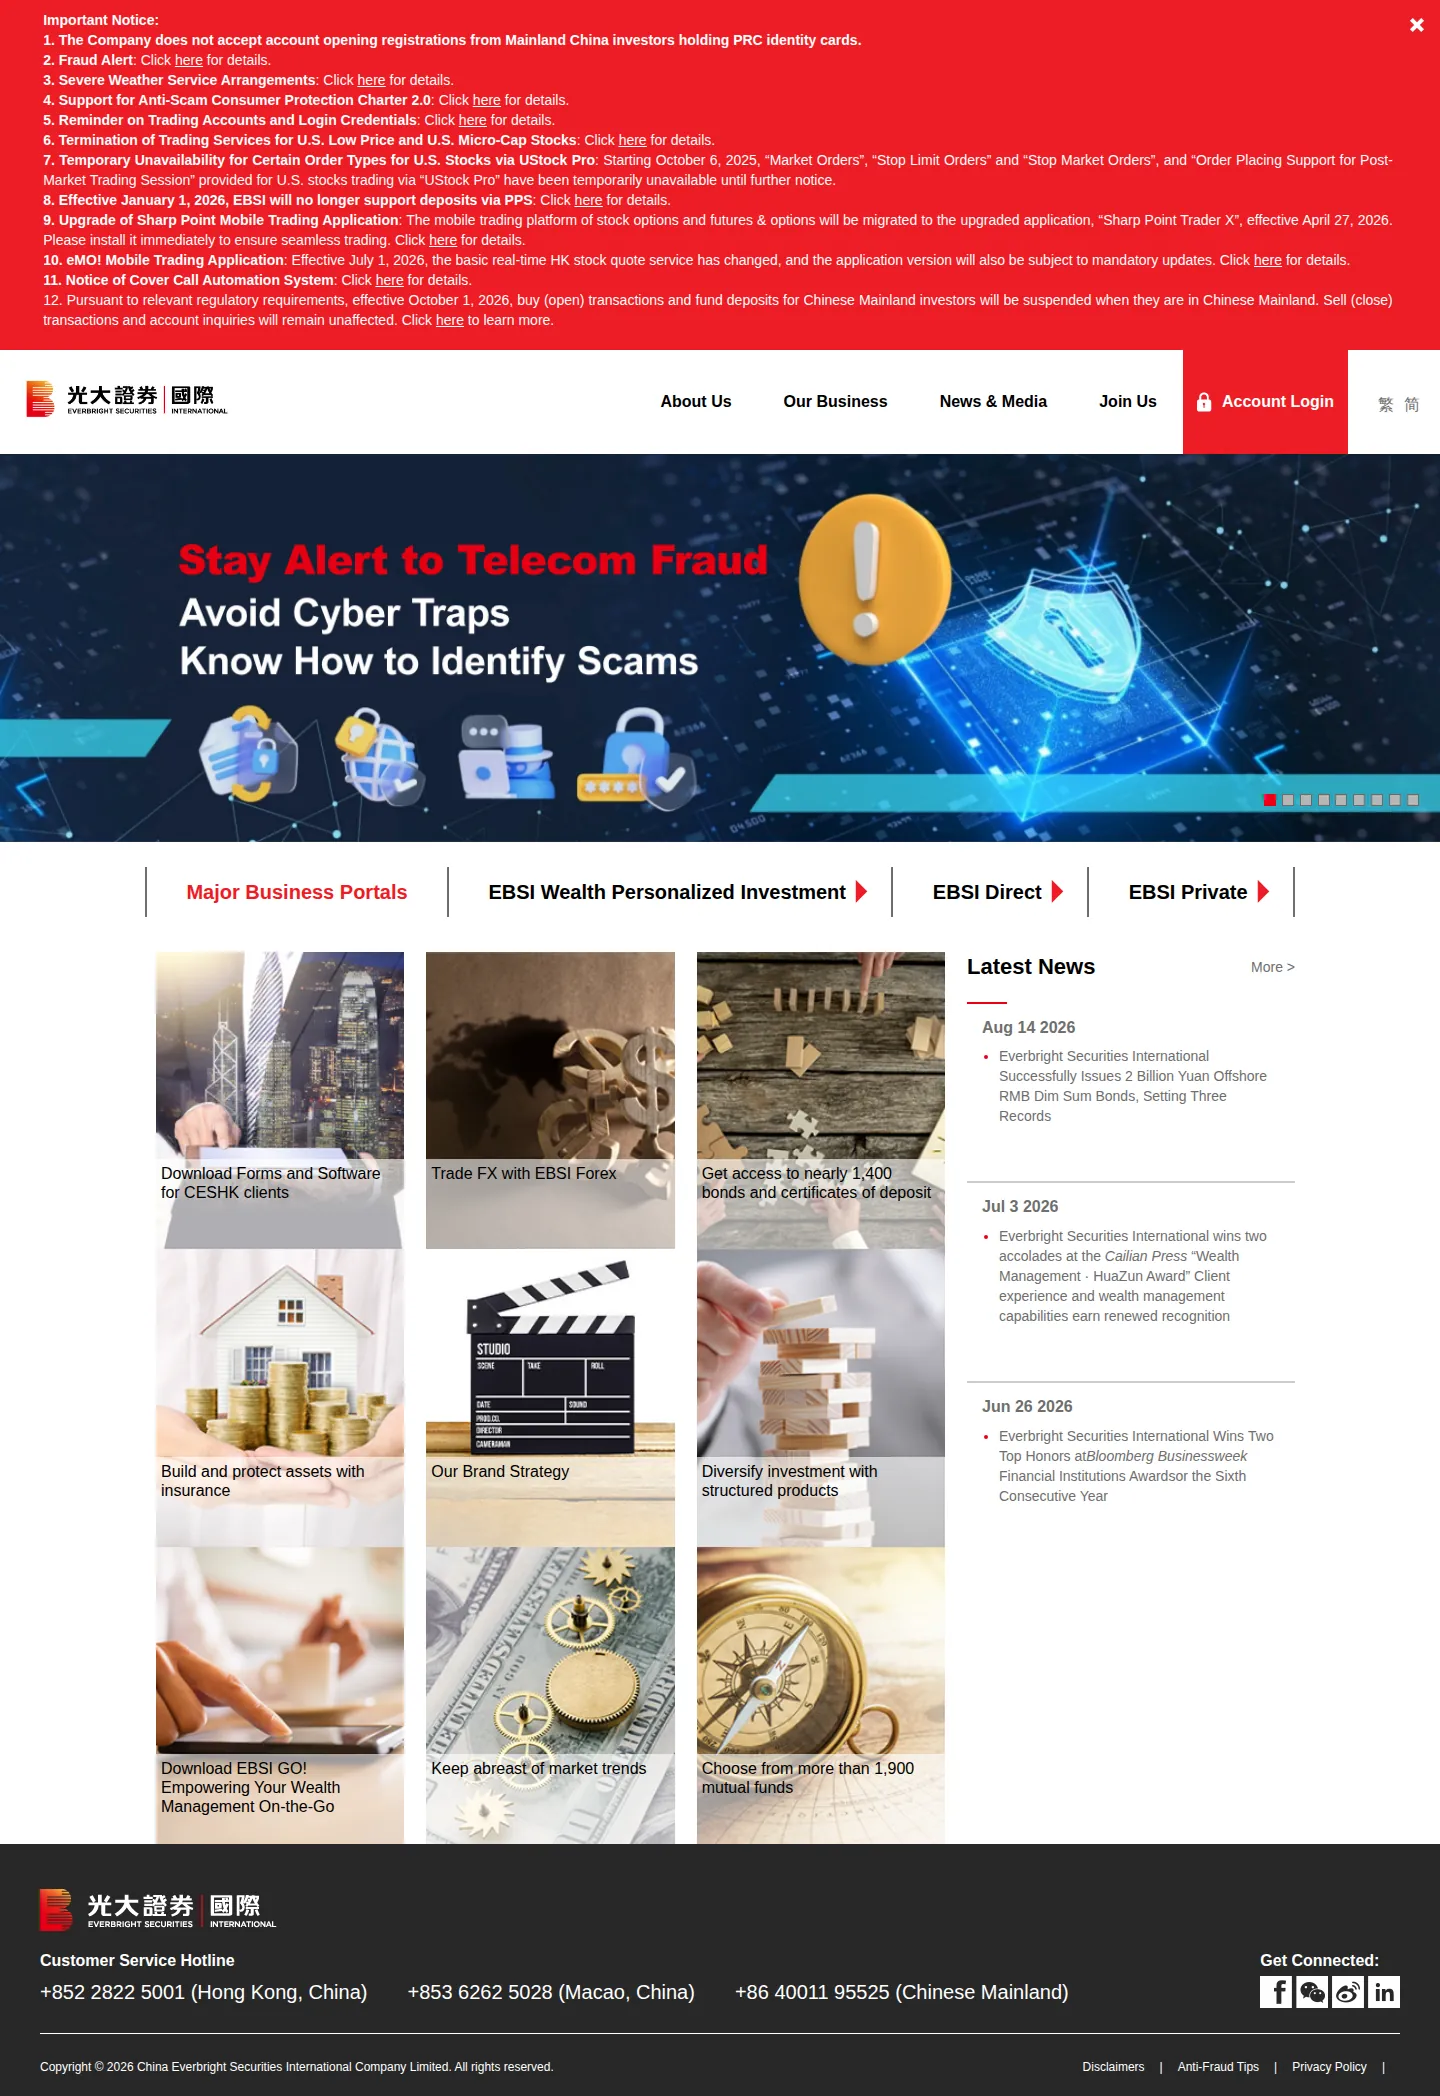
Pages captured from EBSI’s own site when this review was written. Brokers change their terms; these are what we read.
Score history
Recomputed daily; every move is on the record. The current score is always the latest row.
| Date | Score | Move |
|---|---|---|
| 2026-09-22 | 4.8 | ▲ |
| 2026-07-25 | 3.8 | = |
| 2026-07-18 | 3.8 | = |
| 2026-07-11 | 3.8 | · |
FAQ
Is EBSI regulated?
Several EBSI Group entities hold confirmed SFC Hong Kong licences (Types 1,2,3,4,6,9) matching the firm’s own subsidiaries.
What does EBSI charge in fees?
No published cost of trading was found on EBSI’s own pages or documents.
Has EBSI ever been penalized by a regulator?
The SFC register shows a 2022 public reprimand and fine against China Everbright Securities (HK) Limited.
What trading platforms does EBSI offer?
Its own web platform and mobile app, plus Sharp Point Trader X, UStock Pro, EBSI Forex and eMO!.
How can I contact EBSI support?
By email or a published phone number during published hours, though which entity responds depends on who onboarded you.
What do EBSI reviews say?
EBSI has a blended rating of 3.03 stars across 19 ratings.
How this review works
Track EBSI live: score moves and red notices, in your pocket.