STOCK · CHECKED 12 OCT 2026
HSBC Qianhai Securities review.
Mainland China securities company majority owned by HSBC, with no licence number or fees on its site
RISKY
OUT OF 10
HSBC Qianhai Securities shows no licence number anywhere in its own materials. The China Securities Regulatory Commission lists it as a securities company in its 2020 annual report and approved it for margin financing in 2024, and still lists it in its directory of securities companies dated July 2026. Footer registrations are just a website filing and a security filing, not licences, and no trading fees are published.
Each criterion is scored 1 to 10 from primary sources. The overall score is their unweighted mean. How scoring works.
| Founded | 2017 |
|---|---|
| Headquarters | CN |
| Minimum deposit | Not stated |
| Account opening | 1-3 |
- CSRC lists HSBC Qianhai Securities Co., Ltd as a licensed securities firm
- Has its own mobile trading app
- Reachable by email, phone, and published support hours
- No licence number shown anywhere on its site
- Footer registrations are a website filing and a security filing, not licences
- The CSRC directory lists the company but carries no licence number to check
- CSRC listing sits inside a joint venture, not a standalone licence
- No published cost of trading found on the broker's pages or documents
Overview
TrueBroker is a free broker safety checker, and this page is our review of HSBC Qianhai Securities, scored 4.3 out of 10 across regulation, fees, platform, support and reviews. The site we reviewed is operated by HSBC Qianhai Securities Limited Liability Company (汇丰前海证券有限责任公司), a Sino-foreign joint venture securities firm set up in Shenzhen’s Qianhai zone on 2017-08-28 under CEPA Supplementary Agreement X. Its business scope, per its own about page, covers securities underwriting and sponsorship, brokerage, investment advisory, proprietary trading, asset management, and margin financing and securities lending.
Who stands behind HSBC Qianhai
The same about page gives the ownership split: The Hongkong and Shanghai Banking Corporation Limited (香港上海汇丰银行有限公司), based in Hong Kong, holds 90% of registered capital (RMB 16.2亿元), with the remaining 10% (RMB 1.8亿元) held by Qianhai Financial Holdings Co., Ltd. (前海金融控股有限公司), a wholly state-owned enterprise of the Qianhai Authority founded in 2013. The page names HSBC Holdings plc (汇丰控股有限公司) as the ultimate controlling entity behind the HSBC HK stake, and the the Qianhai Authority (深圳市前海深港现代服务业合作区管理局) as the ultimate controller behind the Qianhai Financial Holdings stake.
On the regulatory record, the CSRC list of securities companies in its 2020 annual report (Table 2, row 130) includes HSBC Qianhai Securities Co., Ltd., naming HSBC as foreign shareholder at 51% as at 2020. That list carries no licence number and is dated 2020, so it confirms the entity’s presence on the CSRC’s own roster without giving a current, checkable licence reference. Two other numbers sit in the site footer, a Guangdong ICP website filing (粤ICP备17163758号) and a Guangdong public security network filing (粤公网安备44030502001329号); both are website registrations, an internet-content-provider filing and a public-network-security filing, and name no financial authority, so there is nothing to check them against as a trading licence. We also searched 1441 warning-list entries mirrored from CYSEC, the FCA and FSC Mauritius, and HSBC Qianhai appears on none of them, a clean result against those three lists specifically, not a clearance against every regulator worldwide.
What we could not verify about HSBC Qianhai’s trading terms
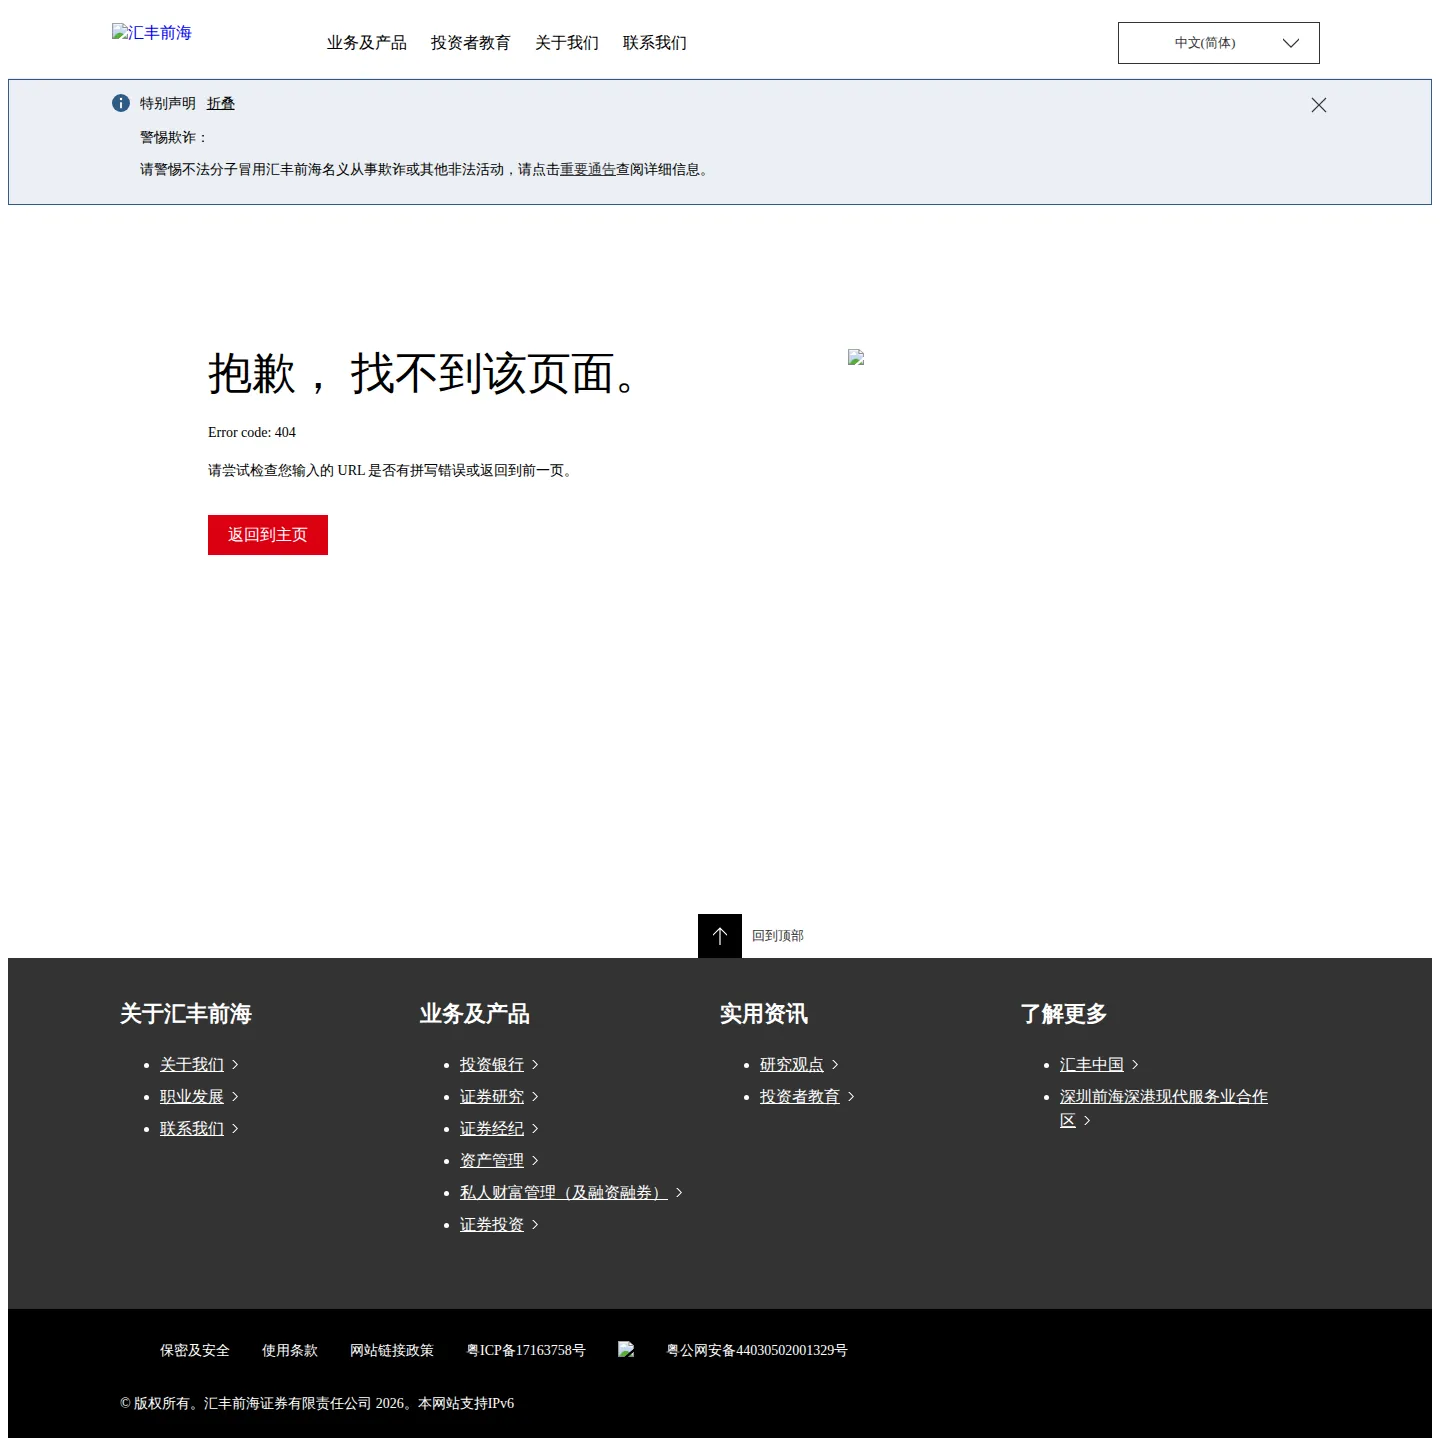
The pages that would normally carry pricing, trading fees, deposits and withdrawals, risk warnings, tradable markets, platform details and account types returned empty bodies, 404s, or generic duplicate shells when we checked them across the UK, UAE, Indonesian and Australian versions of the site. That is why the fees, accounts, instruments and platform facts below read as not stated: the disclosure pages were not retrievable in our evidence, not that the firm was confirmed to omit them.
Where HSBC Qianhai’s site actually points
We probed the site through 10 country exit nodes (id, th, vn, sg, jp, ae, za, gb, de, au) and geo-verification confirmed each hit matched the requested country, but the homepage, legal and terms content served back was near-identical Chinese-language content across most of them. The firm’s own terms state the site is intended primarily for persons in mainland China and that it does not warrant the site or its information complies with the laws of other countries or regions. The same terms state that HSBC Group members reserve the right to decline products or services based solely on a visitor’s country of residence, and that use of the site is governed exclusively by the laws of the People’s Republic of China.
A quirk in the source material worth flagging
One document in our evidence for this firm reads as a third-party review written in first person rather than HSBC Qianhai’s own content, and it closes with an unrelated line promoting a different, unconnected broker. We disregarded that document; figures inside it, including an estimated minimum deposit in the millions of yuan and an unqualified claim of full CSRC licensing, are not corroborated by any firsthand HSBC Qianhai page in our evidence and are excluded from the facts below.
Contact points on record
The contact page lists a general phone line, (86) 0755-8898 3288, a fax number, (86) 0755-8898 3226, and a general enquiries email, ibcn.general@hsbcqh.com.cn, alongside registered addresses for the Shenzhen Qianhai headquarters and securities branch, a Beijing branch, and a Shanghai branch. A separate data-privacy hotline, (86)0755-88983493, is given for weekdays 8:30 to 17:30, alongside a data privacy officer email, ibcndmo@hsbcqh.com.cn.
Terms that bind a client
Under the section 管辖法律, the terms state that use of the website is governed by the laws of the People’s Republic of China. Under 电子邮件, HSBC Qianhai disclaims responsibility for direct, indirect, special, incidental or consequential loss or damage arising from use of the website. Under 互联网传输, the company disclaims responsibility for the accuracy or timeliness of data, information or transactions caused by communications-facility failures outside its control. Under terms (网站内容) and 十一、本政策的制定、生效、privacy policy (更新及其他), both documents state that where the Chinese and English texts are inconsistent, the Chinese text prevails. The privacy policy, under section 4, on how it stores personal information (四、我们如何存储您的个人信息), states that records may be retained for at least 5 years, 20 years, or longer depending on the business scenario, and under section 5, on how it entrusts, shares, transfers and discloses personal information (五、我们如何委托处理、共享、转让和公开披露您的个人信息), states that personal information may be shared with HSBC Group members, contractors, regulators, other financial institutions and industry associations, including cross-border transfers, in some cases without further client consent.
Overview Table
| Headquarters | Shenzhen Qianhai, mainland China (前海周大福金融大厦一期22F2201, per the firm’s contact page) |
| Established | 2017-08-28 (per the firm’s about page) |
| Countries Served | Not stated (terms state the site is primarily for persons in mainland China and content is not warranted to comply with other countries’ laws) |
| Regulated By | Listed in the CSRC’s 2020 annual report roster of securities companies (Table 2, row 130); no licence number given |
| Minimum Deposit | Not stated |
| Maximum Leverage | Not stated |
| Total Instruments | Not stated |
| Platforms | Not stated |
| Customer Support | Phone, fax and email, per the firm’s contact page |
| Languages | Not stated (site content served was in Chinese across the country exit nodes checked) |
Facts List
- HSBC Qianhai is a Sino-foreign joint venture securities company established 2017-08-28 in Shenzhen’s Qianhai zone, per its own about page.
- The Hongkong and Shanghai Banking Corporation Limited holds 90% of registered capital, per the same page.
- Qianhai Financial Holdings Co., Ltd., a wholly state-owned Qianhai Authority enterprise, holds the remaining 10%.
- The about page names HSBC Holdings plc as the ultimate controlling entity behind the HSBC HK stake.
- The CSRC’s 2020 annual report (Table 2, row 130) lists HSBC Qianhai Securities Co., Ltd. among securities companies, with HSBC as a 51% foreign shareholder as at 2020; the list gives no licence number.
- A warning-list search across 1441 entries mirrored from CYSEC, the FCA and FSC Mauritius returned no match for this firm.
- Two site-footer registrations, 粤ICP备17163758号 and 粤公网安备44030502001329号, are website/network filings, not financial licences, and name no authority to check them against.
- Fee, account, instrument and platform pages returned empty, 404, or duplicate content across the UK, UAE, Indonesian and Australian versions of the site we checked.
- The terms state the website is governed by the laws of the People’s Republic of China and is primarily intended for persons in mainland China.
- The privacy policy states client records may be retained for 5 to 20 years or longer, and that personal information may be shared across the HSBC Group and other third parties, including cross-border, sometimes without further consent.
Key Takeaways
What the CSRC register shows about HSBC Qianhai
- The China Securities Regulatory Commission’s 2020 annual report list of securities companies (Table 2, row 130) includes HSBC Qianhai Securities Co., Ltd., naming HSBC as a foreign shareholder holding 51% as at 2020. That is a genuine hit on a named government register, not a claim the firm makes about itself, and it is the strongest single fact in this file.
- The CSRC entry carries no licence number and is dated 2020, so it confirms the entity existed and had HSBC as a foreign shareholder at that point; it does not tell us what HSBC Qianhai is currently licensed to do or at what shareholding. A later CSRC document adds to it: approval 证监许可〔2024〕951号, published on the CSRC website, grants HSBC Qianhai Securities a margin financing and securities lending qualification in 2024, which shows the firm was a CSRC-supervised securities company at that date. The CSRC’s current directory of securities companies, dated July 2026 and published on 9 August 2026, lists 汇丰前海证券有限责任公司 (HSBC Qianhai Securities) at row 127 of 150, registered in Shenzhen. The directory carries no licence numbers.
- The two other numbers the firm publishes in its site footer, 粤ICP备17163758号 and 粤公网安备44030502001329号, name no authority to check them against. They are an internet-content-provider filing and a public-network-security filing, not a financial-services licence, and neither could be checked against any register.
- We searched 1,441 warning-list entries mirrored from the CYSEC, FCA and FSC Mauritius blacklists, and HSBC Qianhai matched none of them. That covers only those three lists, not every regulator worldwide, but it is a clean result the firm can point to.
An ownership picture that doesn’t fully line up
- HSBC Qianhai’s own “about” page puts The Hongkong and Shanghai Banking Corporation Limited at 90% of registered capital (RMB 16.2亿元) and Qianhai Financial Holdings Co., Ltd. at 10% (RMB 1.8亿元), with HSBC Holdings plc named as the ultimate controlling entity behind the HSBC stake.
- The CSRC’s 2020 report instead records HSBC’s foreign shareholding at 51%. Both figures are attributed to their own sources here; our evidence gives no explanation for the gap, and we are not reconciling the two.
What HSBC Qianhai’s own terms bind a client to
- The terms and conditions state use of the website is governed by the laws of the People’s Republic of China (管辖法律), meaning any dispute over site use sits under Chinese law rather than a client’s home jurisdiction.
- Under 电子邮件, the firm states it accepts no responsibility for direct, indirect, special, incidental or consequential loss arising from use of the website, and under 互联网传输 it disclaims responsibility for the accuracy or timeliness of data, information or transactions caused by communications-facility failures outside its control.
- Under 下载软件, the user “bears full responsibility” for protecting and backing up their own data and equipment and for guarding against viruses, with no warranty from the firm against site interruptions or malicious code.
- Both the terms (网站内容) and the privacy policy (十一、本政策的制定、生效、更新及其他) state that where the Chinese and English texts disagree, the Chinese text governs, so a client reading only an English version can be bound by different terms found solely in the Chinese original.
- The privacy policy, section 五, discloses that personal and financial information can be shared with HSBC Group members, contractors, agents, regulators, other financial institutions and industry associations, including cross-border transfers, and that in some statutory cases this does not require further client consent.
- Section 4 (四) of the same policy states records must be kept for periods of not less than 5 years, 20 years, or longer (“不少于5年、20年甚至更长时间”) depending on the type of document, so client data can sit on file long after the relationship ends.
- Section 9 (九) lets the firm decline a data access, correction or deletion request on broad grounds, including where there is sufficient evidence of malicious intent or abuse of rights on the client’s part (“充分证据表明您存在主观恶意或滥用权利”), which limits how enforceable those data rights are in practice.
- The website security (网站安全) section of the privacy policy puts the burden on the client to safeguard their own login credentials and to notify the firm immediately if they are compromised, which is where liability for unauthorized use of an account can land.
Fees, accounts and platforms we couldn’t check
- Our evidence records that pricing, trading-cost, deposit/withdrawal, risk-warning, instrument and account-type pages returned 0-byte bodies, 404s, or generic duplicate shells across every country path probed (gb, ae, id, au and others). No fee, account or platform facts could be pulled from firsthand HSBC Qianhai pages as a result.
- Our evidence also flags a document, the earlier review, written in first-person reviewer voice rather than the firm’s own site content, closing with an unrelated line promoting a different, unconnected broker. Figures in that document, including an “estimated” deposit minimum in the millions of RMB and unqualified licensing claims, are not corroborated anywhere in the firm’s own pages and have been left out of this review entirely.
Reaching HSBC Qianhai
- The contact page lists a general phone line, (86) 0755-8898 3288, a fax number, and a general email, ibcn.general@hsbcqh.com.cn, alongside a separate Data Privacy Officer email (ibcndmo@hsbcqh.com.cn) and a data-privacy hotline, (86)0755-88983493, stated as staffed Monday to Friday, 08:30 to 17:30.
- Registered and branch addresses are given for Shenzhen Qianhai (headquarters and a separate securities-business unit in the same building), Beijing and Shanghai, which is a fuller physical footprint than most of the site’s other disclosures offer.
- The site’s own terms state its products and services are not available in every location where HSBC Group operates, and that HSBC Group members can decline to serve a visitor based solely on country of residence; the terms describe the site as intended primarily for persons in mainland China and do not warrant its compliance with the law of other countries. Ten separate country exit-node checks (including gb, ae, au, sg, jp) each verified the requested geography but were served the same mainland-China-oriented Chinese-language content.
Licenses & Regulation
The registered filer here is HSBC Qianhai Securities Limited Liability Company (汇丰前海证券有限责任公司), a Sino foreign joint venture set up in Shenzhen’s Qianhai zone on 2017 08 28 under CEPA Supplementary Agreement X, with a stated business scope covering securities underwriting and sponsorship, brokerage, investment advisory, proprietary trading, asset management, and margin financing and securities lending. Its majority shareholder is The Hongkong and Shanghai Banking Corporation Limited (香港上海汇丰银行有限公司) of Hong Kong, holding 90 percent of registered capital (RMB 1.62 billion, 16.2亿元), with the remaining 10 percent (RMB 180 million, 1.8亿元) held by Qianhai Financial Holdings Co., Ltd. (前海金融控股有限公司), a wholly state owned enterprise of the Qianhai Authority founded in 2013. The page names HSBC Holdings plc (汇丰控股有限公司) as the ultimate controlling entity behind the Hong Kong stake and the Shenzhen Qianhai authority as the ultimate controller behind the Qianhai Financial Holdings stake.
What the CSRC register shows about HSBC Qianhai
We searched one public register directly, the China Securities Regulatory Commission (CSRC). The CSRC’s list of securities companies in its 2020 annual report, Table 2, row 130, includes HSBC Qianhai Securities Co., Ltd., with HSBC named as foreign shareholder at 51 percent as at 2020. That is a confirmed entity match, drawn from a 2020 dated list that carries no licence number. The 51 percent foreign shareholding figure the CSRC list gives for 2020 does not match the 90 percent stake shown on the firm’s own about page; we have not been able to reconcile the two from the evidence available, and we report both as they stand in their respective sources rather than picking one.
Two other numbers appear in the site footer: 粤ICP备17163758号 and 粤公网安备44030502001329号. Neither claim names an authority, so there is no register to check either one against. The first is an internet content provider filing number and the second is a public network security filing number; both are website and network registrations, not financial services licences, and their absence from any register check is a gap in what the claim itself states rather than a finding about the firm.
Warning list result
We searched 1,441 warning list entries mirrored from CYSEC, the FCA and FSC Mauritius, and HSBC Qianhai appears on none of them. That covers only the lists we mirror, not every regulator worldwide, but it is a clean result across those three.
Governing law and where the site is meant to be used
We read the firm’s own terms and conditions. They state plainly that use of the website is governed by the laws of the People’s Republic of China (“本网站的使用受中华人民共和国法律管辖。”). For a client based outside mainland China, any dispute over use of the site falls to be decided under a legal framework that may be unfamiliar and less accessible than their own. The terms also restrict who the site is meant to serve: HSBC Group members reserve the right to decline to provide products or services based solely on a visitor’s country of residence, and the site is stated to be primarily for persons located in mainland China, with the firm giving no warranty that the site or its information complies with the laws of other countries or regions. Where the Chinese and English texts of the terms, or of the separate privacy policy, disagree, the Chinese text governs (“中英文本之间如有不一致之处,应以中文文本为准。”). A client relying on an English rendering can therefore be bound by obligations that only appear, or appear differently, in the Chinese original.
Although we fetched the site from ten countries, each confirmed to be the country requested, the homepage, legal and terms content served across most of them was near identical Chinese language content, consistent with the terms’ own statement that the site is aimed mainly at mainland China.
What we could not check
Numerous pages a prospective client would look for, including pricing, trading fees, costs, commissions, deposits and withdrawals, risk warning, markets and instruments, platforms and account types, returned empty bodies, 404s, or generic duplicate shells when we probed the gb, ae, id and au site paths. That is why this review has no licence numbers, fee schedule, account tiers or platform facts to report for HSBC Qianhai: the disclosure pages were not retrievable, not that the firm was confirmed to omit them.
Separately, our evidence included a document, the earlier review, written in a first person reviewer voice that closes with an unrelated line promoting a different, unconnected broker. That reads as an injected item rather than firsthand HSBC Qianhai material, and its figures, including an estimated deposit minimum in the millions of RMB and an unqualified claim of full CSRC licensing, are not corroborated by any firsthand HSBC Qianhai page in our evidence, so they are excluded here.
How to Trade
HSBC Qianhai Securities is a Sino-foreign joint venture securities company, established on 2017-08-28 under CEPA Supplementary Agreement X, according to the firm’s own about page. The same page states the firm’s registered business scope, meaning what it is set up and permitted to do, covers:
- securities underwriting and sponsorship
- brokerage
- investment advisory
- proprietary trading
- asset management
- margin financing and securities lending
That is a statement of scope, not a description of how any one of those services is priced, executed, or delivered to a retail client.
What the CSRC register shows about HSBC Qianhai
The China Securities Regulatory Commission’s list of securities companies, published in its 2020 annual report (Table 2, row 130), includes HSBC Qianhai Securities Co., Ltd. and records HSBC as a foreign shareholder holding 51% of the company as at 2020. The firm’s own about page gives a different split as of its own date: The Hongkong and Shanghai Banking Corporation Limited holding 90% (RMB 1.62 billion of registered capital) and Qianhai Financial Holdings Co., Ltd. holding the remaining 10% (RMB 180 million). The two figures come from separately dated sources, and the CSRC entry itself carries no licence number.
What HSBC Qianhai’s own pages did not give us
The pages that would normally describe how trading works here, pricing and trading fees, costs and commissions, deposits and withdrawals, a risk warning, a list of markets and instruments, platform pages, and account-type pages, returned 0-byte bodies, 404s, or generic duplicate shells when checked across the firm’s gb, ae, id, and au site paths. We are not able to report instrument coverage, execution model, spreads, commissions, minimum deposit, platform choice, or account tiers on that basis, because the pages that would state them were not retrievable in this pass. A separate document in the evidence for this review reads as a third-party account of HSBC Qianhai rather than the firm’s own content: it is written in first-person reviewer voice, gives figures such as an “estimated” minimum deposit and account-tier and platform comparison tables, and closes with an unrelated line promoting a different, unconnected broker. None of those figures are corroborated on the firm’s own site, so they are not repeated here.
The terms that bind a client once a position is placed
HSBC Qianhai’s own website terms set conditions that reach the point of trading. Under the heading governing law (管辖法律), the terms state that use of the website is governed by the laws of the People’s Republic of China. Under website content (网站内容), the terms state that where the Chinese and English texts are inconsistent, the Chinese text prevails, so a client reading only the English rendering can be bound by obligations that appear, or appear differently, in the Chinese-language version. Under internet transmission (互联网传输), the firm states it bears no responsibility for the accuracy or timeliness of data, information, or transactions caused by communications-facility failures outside its control, language that reaches the point at which an order is actually transmitted. Under email (电子邮件), the firm disclaims responsibility for direct, indirect, special, incidental, or consequential loss or damage arising from use of the website. Under downloaded software (下载软件), the client is made responsible for backing up their own data and equipment and for taking precautions against viruses, with no warranty from the firm against interruptions or errors on the site.
The same terms state that the website’s products and services are not available in every location where HSBC Group members operate, and that HSBC Group members reserve the right to decline to provide products or services based solely on a visitor’s country of residence. The terms describe the site as intended primarily for persons located in mainland China and state that the firm does not warrant that the site or its information complies with the laws of other countries or regions.
Account Types
The account-types, pricing and account-tier pages that would normally sit behind this section returned nothing usable during our check: pricing, trading fees, costs, commissions, deposits-and-withdrawals and account-types pages across the gb, ae, id and au paths of the site came back as 0-byte bodies, 404s or generic duplicate shells. We cannot report what accounts HSBC Qianhai Securities sells, what each tier costs to open, or what a deposit buys, because the firm’s own pages describing that were not retrievable in this check.
What HSBC Qianhai Securities is set up to sell
The firm’s own “about” page describes HSBC Qianhai Securities Limited Liability Company (汇丰前海证券有限责任公司) as a Sino-foreign joint venture established on 2017-08-28 under CEPA Supplementary Agreement X, with a stated business scope covering securities underwriting and sponsorship, brokerage, investment advisory, proprietary trading, asset management, and margin financing and securities lending. That page does not break any of these lines of business into named account tiers, minimum deposits, or fee schedules, so we can confirm the scope of what the firm is set up to offer without being able to say what a client account within any of those lines actually costs or includes.
Who the firm will and won’t open an account for
HSBC Qianhai’s own terms state that the site is primarily intended for persons located in mainland China, and that the firm does not warrant that the site or its information complies with the laws of other countries or regions. The terms also state that HSBC Group members reserve the right to decline to provide products or services based solely on a visitor’s country of residence, where that visitor sits outside the jurisdictions where HSBC Group holds operating licences. Any prospective client outside mainland China should read this as the firm’s own statement that account access is not guaranteed, rather than as a description of an account-opening process.
One document in our evidence for this firm, “the earlier review”, presents itself as a third-party review in first-person voice and includes an unrelated promotional line steering readers toward a different, unconnected broker. Because it reads as an injected promotional insert rather than firsthand HSBC Qianhai content, we have not drawn account-tier figures, minimum-deposit figures, or platform comparisons from it; none of those figures appear on a firsthand HSBC Qianhai page in our evidence.
Negative Balance Protection
HSBC Qianhai Securities Limited Liability Company, the entity behind this site, lists margin financing and securities lending (融资融券) among its licensed business lines alongside brokerage, underwriting, investment advisory, proprietary trading and asset management, according to the firm’s own about page. That business line is exactly where a stock investor’s losses can run past the cash and securities put up as collateral, since a margin loan against a falling stock can leave a shortfall the client still owes. The pages that would normally set out how HSBC Qianhai runs that margin book, things like margin call triggers, maintenance ratios, forced liquidation rules or any negative balance protection, did not load when we tried to retrieve them: the risk warning, trading fees, costs and commissions pages across the UK, UAE, Indonesian and Australian versions of the site came back as 0 byte bodies, 404s or duplicate generic shells, as our fetch record shows. We have no firsthand HSBC Qianhai page describing what happens if a margin position moves against a client faster than the account can cover.
What HSBC Qianhai’s terms say about losses from its own systems
The site terms and conditions we did read address a narrower kind of loss, the kind caused by the website and its infrastructure rather than by market moves. HSBC Qianhai states, under Email (电子邮件), that it accepts no responsibility for direct, indirect, special, incidental or consequential loss or damage arising from use of the website. Under Internet Transmission (互联网传输), it states the company bears no responsibility for the accuracy or timeliness of data, information or transactions caused by communications facility failures outside its control, meaning a client whose margin order fails to execute, or executes late, because of a network or telecom fault cannot hold the firm liable even where that timing affects the transaction. Under Downloaded Software (下载软件), the user bears full responsibility for protecting and backing up their own data and equipment and for taking reasonable precautions against viruses, and the firm makes no warranty against interruptions, errors or malicious code on the site.
The privacy and account security terms add a point that bears on unauthorized trading losses specifically. Under How We Protect Your Personal Information (一、我们如何保护您的个人信息), the client is told to keep login and password information secure and not to disclose it to others, and to notify HSBC Qianhai immediately if that information is leaked, lost or stolen to prevent the loss from expanding (“以防止损失扩大”). Read together with the liability disclaimers above, the practical effect is that a client whose account is used without authorization, whether through a compromised password or a failed connection, carries the burden of prompt notice, rather than the firm assuming that risk by default.
What the CSRC record and the score reflect
The China Securities Regulatory Commission’s 2020 annual report lists HSBC Qianhai Securities Co., Ltd. in its table of securities companies (Table 2, row 130), with HSBC as the 51% foreign shareholder as at 2020, though the list carries no licence number and is dated to 2020. That entry confirms the entity’s presence in a CSRC filing; it says nothing about margin financing rules or negative balance treatment, and no other register or firm page in our evidence did either. HSBC Qianhai’s regulation score of 4.5 and fees score of 2 reflect the wider evidence rather than anything specific to margin or drawdown handling, since the pages needed to check that were not retrievable.
Trading Instruments
HSBC Qianhai’s own site does not carry a live instrument or markets page that we could retrieve. Pages for pricing, fees, deposits, risk warnings, markets, platforms and account types returned 0-byte bodies, 404s or duplicate shells when we probed them across the UK, UAE, Indonesian and Australian versions of the site, so we have no firsthand page from the firm listing which stocks, boards, bonds or funds a client can actually place an order in.
What HSBC Qianhai’s own about page says it does
The one page that does describe the business is the firm’s “about” page, which gives the business scope of HSBC Qianhai Securities Limited Liability Company (汇丰前海证券有限责任公司) as securities underwriting and sponsorship, brokerage, investment advisory, proprietary trading, asset management, and margin financing and securities lending. The same page dates the firm’s establishment to 28 August 2017, under CEPA Supplementary Agreement X, as a Sino-foreign joint venture based in Shenzhen Qianhai. That is a description of licensed business lines, not a catalogue of tradable instruments: it tells us the firm is set up to broker securities and lend against them, not which exchanges, boards or products a retail client can open a position in, what the minimum lot size is, or whether the “stock” access on offer extends beyond mainland China A-shares.
What the CSRC register confirms
We searched the CSRC register directly. The China Securities Regulatory Commission’s 2020 annual report lists HSBC Qianhai Securities Co., Ltd. in its table of securities companies (Table 2, row 130), with HSBC named as foreign shareholder at 51% as at 2020. That entry confirms the firm sat on the CSRC’s own list of securities companies, which is consistent with the brokerage and underwriting scope described on the firm’s about page, but the entry carries no licence number and dates from 2020. A CSRC approval from 2024 (证监许可〔2024〕951号) shows the firm was still a supervised securities company then, and the CSRC directory dated July 2026 still lists it, but none of these documents tells us which specific markets its brokerage licence covers. The firm’s own about page, separately, states current ownership as 90% to The Hongkong and Shanghai Banking Corporation Limited and 10% to Qianhai Financial Holdings (前海金融控股有限公司), a different split from the CSRC’s 2020 figure; we have no page reconciling the two, so both are reported here as they stand, from their own dates.
Why the asset list stays incomplete
Beyond the business-scope description above, we hold nothing that names an exchange, an instrument class, a minimum trade size or a commission schedule tied to stock trading. Our evidence also flags a document, the earlier review, written in first-person reviewer voice rather than as HSBC Qianhai’s own content, which includes an account-tier and platform comparison table and an unrelated line promoting a different broker, EFSG, for MT4 trading. That document is not the firm’s own material, its figures are not corroborated by any HSBC Qianhai page in our evidence, and it has been left out of this section rather than reported as fact.
Who the offer is even open to
HSBC Qianhai’s own terms state the website is intended primarily for persons located in mainland China, that the firm does not warrant the site or its information complies with the laws of other countries or regions, and that HSBC Group members reserve the right to decline to provide products or services based solely on a visitor’s country of residence. Separately, fetching the site from ten countries, each confirmed to be the country requested, returned near-identical mainland-China-oriented content every time. Put together with the terms above, that means a visitor browsing from most of those locations is looking at the same mainland-China-facing pages rather than a version of the site built for stock access from where they sit, and the terms themselves do not commit to extending the underwriting, brokerage, proprietary trading, asset management or securities-lending scope described above to clients outside mainland China or HSBC Group’s authorized jurisdictions.
Education & Analysis
The pages that would normally carry this section’s material never loaded. When we fetched the UK, UAE, Indonesian and Australian versions of the site, the fee page returned a 404 and the account page an untitled shell, and no markets or platforms page for HSBC Qianhai Securities Limited Liability Company (汇丰前海证券有限责任公司) came back at all. That is what our fetches recorded, not a finding that the firm has nothing to show; we simply could not retrieve a platform or charting page to read.
What HSBC Qianhai’s own pages tell us about its business
The one page in our evidence that describes the firm at all, its about page, gives a business scope rather than a platform description: securities underwriting and sponsorship, brokerage, investment advisory, proprietary trading, asset management, and margin financing and securities lending, under a joint venture structure established on 2017-08-28 under CEPA Supplementary Agreement X. That tells us the lines of business a trading platform would need to support at this firm, brokerage execution and margin lending among them, but the about page stops there. It names no platform, no charting package, and no execution venue, and no other firsthand HSBC Qianhai page in our evidence fills that gap.
The one clause that touches software on the site
The terms page’s Downloading Software (“下载软件”) section is the only firsthand text in our evidence that addresses tooling on the site at all, and it runs the other way: it puts the burden of protecting and backing up data and equipment, and of taking reasonable precautions against viruses, on the user rather than the firm. Read plainly, the firm is disclaiming responsibility for anything downloaded through the site rather than describing a charting or analysis tool it provides. A separate clause in the same terms page states that HSBC Qianhai accepts no responsibility for direct, indirect, special, incidental or consequential loss arising from use of the website, and a third states the firm bears no responsibility for the accuracy or timeliness of data, information or transactions caused by communications-facility failures outside its control. None of the three is written about a trading platform specifically, but all three would apply to one if the firm operates one through this site.
An earlier review we did not use for this section
Our evidence also contains an older, separately sourced document that reads as a third-party review rather than firm material, written in the first person and closing with an unrelated line urging readers to try a broker called EFSG for MT4 support, a firm with no connection to HSBC Qianhai. That document includes account-tier and platform comparison tables, but nothing in HSBC Qianhai’s own pages in our evidence corroborates them, and the promotional line at the end reads as an injection rather than analysis. We have disregarded its platform and tooling figures rather than restate them as if they came from HSBC Qianhai.
What that leaves for a reader comparing charting and tools
We hold no firsthand description of a trading platform, mobile app, charting package, order types, or research and analysis tools for HSBC Qianhai Securities. We hold the firm’s business scope from its about page, a set of liability and software-risk clauses from its terms page that would govern any platform if one exists, and a warning that the site itself is oriented toward mainland China and makes no claim to suit visitors elsewhere. A reader who needs to know what charting tools this firm actually offers has to get that from the firm directly; nothing we fetched answers it, and nothing here should be read as saying the firm has no platform, only that we could not retrieve one that describes it.
Special Offers
We looked for a promotions or offers page across the site paths our evidence covers and did not find one to read. The pages that came back clean were the corporate “about” page describing HSBC Qianhai Securities Limited Liability Company’s shareholders, the site terms, the privacy/legal policy, and the contact page listing phone, fax, email and branch addresses. None of those four documents mentions a bonus, a fee waiver, a discounted commission period, a deposit match or any other promotional term for HSBC Qianhai.
Why the fee and account pages are missing rather than silent
Our fetch record shows that the pages a prospective client would actually need to check for an offer, pricing and trading-fee pages, a costs page, a deposits-and-withdrawals page, and an account-types page, came back as 0-byte bodies, 404s or generic duplicate shells when requested from the UK, UAE, Indonesian and Australian versions of the site. That is a retrieval failure, not a confirmation that HSBC Qianhai runs no promotions. We simply do not have the page that would carry one.
A promotion in our evidence, but not HSBC Qianhai’s
One document in our evidence, labelled the earlier review, is written in the voice of a third-party reviewer rather than anything published by HSBC Qianhai, and it closes by promoting an unrelated broker. EFSG is a different broker with no stated connection to HSBC Qianhai. We are treating that line, and the account-tier, minimum-deposit and platform figures that ride alongside it in the same document, as unconnected to HSBC Qianhai and have left them out of this review rather than reporting them as the firm’s offer.
What the register and site content we do hold cover instead
The CSRC’s 2020 annual report lists HSBC Qianhai Securities Co., Ltd. as a securities company with HSBC holding a 51% foreign stake as at 2020, which confirms the entity exists on that register; it says nothing about pricing or promotions, and it carries no licence number. The terms and privacy documents we did read set out governing law, liability disclaimers and data-retention rules for the site, none of which touch account opening incentives or fee discounts either.
On the basis of what we could retrieve, we cannot describe a special offer, a welcome bonus, a referral scheme or a promotional fee tier for HSBC Qianhai, because the pages that would state one were not among the pages that loaded.
Opening an Account
Our evidence for this section is thin. HSBC Qianhai’s own site pages describing account opening, verification steps, or eligibility restrictions returned 0 byte bodies, 404s, or generic duplicate shells when our review process probed them across the UK, UAE, Indonesian and Australian versions of the site, so there is no firsthand account opening procedure to report. What follows is limited to the terms, privacy policy and register findings that were actually read.
What the CSRC register shows about the entity
The China Securities Regulatory Commission’s list of securities companies, in its 2020 annual report at Table 2, row 130, includes HSBC Qianhai Securities Co., Ltd., with HSBC as foreign shareholder at 51% as at 2020. That list gives no licence number and is dated 2020, so it confirms the entity’s inclusion on the CSRC’s list at that date rather than a current licence status. The firm’s own about page, separately, describes the entity as HSBC Qianhai Securities Limited Liability Company (汇丰前海证券有限责任公司), a Sino foreign joint venture established 2017 08 28 under CEPA Supplementary Agreement X, with a business scope covering securities underwriting and sponsorship, brokerage, investment advisory, proprietary trading, asset management, and margin financing and securities lending. The same page names The Hongkong and Shanghai Banking Corporation Limited (香港上海汇丰银行有限公司) as majority shareholder at 90% (RMB 1.62 billion (16.2亿元) of registered capital) and Qianhai Financial Holdings Co., Ltd. (前海金融控股有限公司) as minority shareholder at 10% (RMB 180 million (1.8亿元)), with HSBC Holdings plc (汇丰控股有限公司) named as the ultimate controlling entity behind the HSBC HK stake.
Who the site says it will and will not serve
The firm’s own terms, read by our review process, state that the website’s products and services are not available in every location where HSBC Group members operate, and that HSBC Group members reserve the right to decline to provide products or services based solely on a visitor’s country of residence. The same terms state the website is primarily for persons located in mainland China, and the firm does not warrant that the site or its information complies with the laws of other countries or regions; content is not intended for distribution where prohibited by local law. Beyond this, our evidence gives no page describing what a prospective client must submit to open an account, no minimum deposit figure, and no identity verification procedure, so none of that can be reported here.
Terms that would bind a client who does open an account
Two documents the firm publishes, its website terms and its privacy or legal policy, set conditions that would apply once someone is dealing with HSBC Qianhai rather than just browsing. Under Governing Law (管辖法律), the terms state that use of the website is governed by the laws of the People’s Republic of China, meaning any dispute over the site itself is decided under Chinese law. Under Website Content (网站内容) in the terms, and again under Section 11, Formulation, Effectiveness, Update and Other Matters of This Policy (十一、本政策的制定、生效、更新及其他) in the privacy policy, both documents state that where the Chinese and English texts are inconsistent, the Chinese text prevails, so a client relying on an English version can be bound by obligations that appear only in the Chinese language original.
The privacy policy, under section 4, on how it stores personal information (四、我们如何存储您的个人信息), states that depending on the business scenario and the nature of the document, related materials, records and information must be kept for no less than 5 years, 20 years, or even longer, meaning client data can be retained well beyond the life of the account. Under Section 5, How We Entrust Processing, Share, Transfer, and Publicly Disclose Your Personal Information (五、我们如何委托处理、共享、转让和公开披露您的个人信息), the same policy states personal and financial information may be shared with HSBC Group members, contractors and agents, regulators, other financial institutions and industry associations, and may involve cross border transfer, with some circumstances permitted by law without further client consent. Under Section 1, How We Protect Your Personal Information (一、我们如何保护您的个人信息) and Website Security (网站安全), the policy places responsibility on the client to safeguard their own account and password information and to notify the firm immediately if credentials are leaked, lost or stolen, to limit further loss, which places the burden of prompt reporting on the client rather than the firm.
Under section 9, on how to contact the firm (九、如何联系我们), the privacy policy also states the firm may refuse a data access, correction or deletion request that it judges unlawful, non compliant, needlessly repetitive, technically excessive, a risk to others’ lawful rights, beyond a reasonable limit, or technically impractical, and lists sufficient evidence of subjective malice or abuse of rights among the grounds it may decline to respond to. That gives the firm broad, partly subjective discretion over a client’s own data requests.
Clean result on the warning lists
our review process searched 1441 warning list entries mirrored from CYSEC, the FCA and the FSC Mauritius, and HSBC Qianhai appears on none of them. That covers only the three regulators mirrored here, not every regulator worldwide, so it is a narrow clean result rather than a general clearance.
What our review process could not check
Two registration numbers appear in the site footer, a Guangdong ICP filing number (粤ICP备17163758号) and a Guangdong public security network filing number (粤公网安备44030502001329号). Neither names an authority in the evidence gathered, so there was no register to check either number against; that is a gap in what the footer states, not a finding about the firm. No licence entries, no account types, and no fee or platform pages were retrievable in our evidence, so steps to open an account, verification documents required, and any minimum deposit or eligibility threshold cannot be stated here.
Deposits & Withdrawals
We went looking for HSBC Qianhai’s own pages on deposits, withdrawals, costs and commissions across the UK, UAE, Indonesian and Australian versions of the site. The pricing/fees page, the trading-costs page, a dedicated deposits-withdrawals page and the risk-warning page all came back as 0-byte bodies, 404s, or generic duplicate shells rather than working pages. That is a gap in what we were able to fetch, not a finding that HSBC Qianhai charges nothing to move money in or out, and the two are different things.
What HSBC Qianhai’s own pages actually cover
The firm’s own material in our evidence is limited to its about page, its contact page, its website terms and its privacy/legal notice. None of those documents state a minimum deposit, a withdrawal fee, a processing cycle, a payment method, or a cap on how much a client can move. The about page does confirm the firm’s registered business scope includes margin financing and securities lending alongside brokerage and asset management, which is a business that necessarily moves client cash, but the page stops there and gives no figures for how that cash moves.
A figure we deliberately left out
A document in our evidence (“the earlier review”) reads as a third-party review rather than anything published by HSBC Qianhai. It carries a first-person reviewer voice, cites an “estimated” minimum deposit in the range of ¥6 million to ¥10 million, and closes with a line promoting an unrelated broker, EFSG, that has nothing to do with HSBC Qianhai. Because that figure is not corroborated by any page we fetched directly from the firm, we have not used it here. A number attributed to HSBC Qianhai in this review needs to come from HSBC Qianhai’s own page, and on deposits and withdrawals specifically, we did not retrieve one.
What the terms and conditions do say about money-related risk
The website terms we did read are not about deposit or withdrawal mechanics either; they are about use of the site itself. They do carry two clauses worth flagging to anyone who will be transacting through this firm. First, the terms state that HSBC Qianhai accepts no responsibility for direct, indirect, special, incidental or consequential loss or damage arising from use of the website, under the section email (电子邮件). Second, under internet transmission (互联网传输), the company disclaims responsibility for the accuracy or timeliness of data, information or transactions caused by communications-facility failures outside its control. Neither clause sets a fee or a cycle, but both bear on what happens if a deposit instruction, a withdrawal request or a trade confirmation goes astray over a network fault: the client, not the firm, carries that risk under the terms as written.
On the specific mechanics a depositing or withdrawing client would want, rails, processing times, minimums, caps, and any fee schedule, we have nothing sourced from HSBC Qianhai to report. The pages that would carry that information did not load in our evidence, and we are not filling the gap with our earlier review’s unverified figures.
Customer Support
Contacting HSBC Qianhai Securities means writing or calling a mainland Chinese office, not a UK or Hong Kong service line. The firm’s own contact page lists a general phone number, a fax number, and a general enquiries mailbox, alongside four physical addresses for its head office and branches.
How to reach HSBC Qianhai’s support desk
The contact page gives a general enquiries phone line at (86) 0755 8898 3288, a fax number at (86) 0755 8898 3226, and a general enquiries email address at ibcn.general@hsbcqh.com.cn. No hours are listed against this phone line in the material we read. The same page gives four addresses: the registered head office at Unit 2201, 22F, Qianhai Chow Tai Fook Finance Building (Phase 1), No. 66 Shuniu Street, Nanshan Street, Qianhai Shenzhen Hong Kong Modern Service Industry Cooperation Zone, Shenzhen, postcode 518052; a separate securities business branch address in the same building at Unit 2202, 22F; a Beijing branch at Unit 07 to 09, 2001, Building 1, Unit 2, No. 1 Dongsanhuan Zhonglu, Chaoyang District, Beijing, postcode 100020; and a Shanghai branch on the 20th floor of the HSBC Building, Shanghai IFC, No. 8 Century Avenue, Pudong New Area, Shanghai, postcode 200120.
Data privacy hotline
Separately from general enquiries, the firm’s privacy policy names a Data Privacy Officer mailbox at ibcndmo@hsbcqh.com.cn and a dedicated privacy hotline at (86) 0755 8898 3493, stated as staffed on working days, Monday to Friday, 8:30 to 17:30. This is the only channel in the material we read that carries stated operating hours.
Terms that shape what happens if a client complains
The website terms state, under governing law (管辖法律), that use of the site is governed by the laws of the People’s Republic of China, so any dispute over use of the site falls to be decided under Chinese law rather than the law of a client’s home jurisdiction. Under 网站内容, and again under the privacy policy’s section 十一, the terms provide that where the Chinese and English texts are inconsistent, the Chinese text prevails, so a client reading only the English version can be bound by obligations that appear only in the Chinese original.
Several clauses limit what a client can hold the firm to. Under 电子邮件, the terms state that HSBC Qianhai accepts no responsibility for direct, indirect, special, incidental or consequential loss or damage arising from use of the website. Under 互联网传输, the firm states it bears no responsibility for the accuracy or timeliness of data, information or transactions caused by communications facility failures outside its control, meaning a client cannot hold the firm liable for a trade or data problem that stems from a network or telecom fault. Under 下载软件, the terms place full responsibility on the user for protecting and backing up their own data and equipment and for taking precautions against viruses, with no warranty from the firm against interruptions, errors or malicious code on the site.
The privacy policy also constrains how a client’s own complaints and data requests are handled. Under section 9, on how to contact the firm (九、如何联系我们), the firm states it may decline requests that are illegal, non compliant, needlessly repetitive, require disproportionate technical means, would put others’ lawful rights at risk, exceed reasonable limits, are technically impractical, or where there is sufficient evidence of the requester’s malicious intent or abuse of rights. Under 五、我们如何委托处理、共享、转让和公开披露您的个人信息, personal and financial information can be shared with HSBC Group members, contractors and agents, regulators, other financial institutions and industry associations, including cross border transfers, and in some statutory circumstances without further client consent. Under 四、我们如何存储您的个人信息, client records may be kept for not less than 5 years, 20 years, or longer depending on the type of business and document. Under 一、我们如何保护您的个人信息 and its 网站安全 sub section, a client is responsible for safeguarding their own login and password information and must notify the firm immediately if it is disclosed, lost or stolen, which places the burden of prompt notice, and the risk of delay, on the client rather than the firm.
Taken together, the channels are conventional phone, fax, email and postal contact points into a mainland Chinese office, backed by terms that route disputes to Chinese law, favour the Chinese language text over any translation, disclaim the firm’s liability for a wide range of site related and network related losses, and give the firm broad grounds to decline a client’s own data requests.
Prohibited Countries
HSBC Qianhai’s own terms page does not publish a list of banned countries. What it publishes instead is a pair of general reservations, and a client outside mainland China has to work out from those where they stand.
What HSBC Qianhai’s terms actually reserve
The firm’s terms page states that its products and services are not available in every location where HSBC Group members operate, and that HSBC Group members reserve the right to decline to provide products or services based solely on a visitor’s country of residence. The clause names no countries; it is a blanket reservation of the right to refuse, not a schedule of exclusions.
The same page goes further on who the site is actually for: it states that the website is primarily intended for persons located in mainland China, that HSBC Qianhai does not warrant the site or its information complies with the laws of other countries or regions, and that its content is not intended for distribution where prohibited by local law. Read together with the country-of-residence clause, this puts the burden on a visitor outside mainland China to establish for themselves whether they are allowed to use the site at all, rather than HSBC Qianhai warranting that they are.
What we found serving the site from ten countries
We fetched HSBC Qianhai’s site from ten countries (Indonesia, Thailand, Vietnam, Singapore, Japan, the UAE, South Africa, the UK, Germany and Australia) and confirmed each request came from the country requested. The homepage, legal and terms content served back was near-identical Chinese-language content across most of those exit points. Combined with the terms’ own statement that the site is intended mainly for mainland China and carries no warranty of compliance elsewhere, a visitor browsing from any of those ten countries is being served the same mainland-China-oriented material as a visitor in Shenzhen, not a locally adapted offering with locally cleared terms.
HSBC Qianhai itself is a Sino-foreign joint venture registered in Shenzhen Qianhai, established in 2017 under CEPA Supplementary Agreement X, majority-owned by The Hongkong and Shanghai Banking Corporation Limited (90% of registered capital) alongside Qianhai Financial Holdings Co., Ltd. (10%), a wholly state-owned enterprise of the Qianhai Authority. The China Securities Regulatory Commission’s 2020 annual report lists HSBC Qianhai Securities Co., Ltd. among securities companies with HSBC as a 51% foreign shareholder as at 2020, though that entry carries no licence number and is five years old. Nothing in that CSRC record, or in the site’s own terms, describes HSBC Qianhai as licensed to solicit or service clients outside mainland China.
The governing law a client outside mainland China would be bound by
HSBC Qianhai’s terms state, under the heading governing law (管辖法律), that use of the website is governed by the laws of the People’s Republic of China. Anyone using the site from another jurisdiction who has a dispute over that use is bound to Chinese law and, by implication, to whatever forum applies under it, rather than to the law of wherever they are actually located.
The terms and the separate privacy policy each also carry a language-priority clause: where the Chinese and English texts are inconsistent, the Chinese text prevails. The terms put it under the heading website content (网站内容), and the privacy policy repeats the same rule under its final section on the policy’s drafting and effect. A client who reads only the English version of either document, and who does not read the governing Chinese text, can be bound by obligations that differ from the ones they actually read.
None of this amounts to a named list of excluded countries. It amounts to a China-registered joint venture whose site defaults to serving mainland-China-oriented content everywhere we checked, whose terms reserve an unqualified right to turn away a visitor on the basis of country of residence alone, and whose governing law and controlling-language clauses both run to the PRC text regardless of where the visitor connects from.
Conclusion
HSBC Qianhai Securities scores 4.3 out of 10 overall. That figure sits on top of a strong regulation score (4.5) and solid platform and support marks (5 and 5.8), dragged down by a weak fee score (2) that reflects how little of the firm’s cost structure we could actually check.
What holds the score up
The regulation score rests on real ground. The CSRC’s own 2020 annual report lists HSBC Qianhai Securities Co., Ltd. among China’s securities companies (Table 2, row 130), with HSBC named as foreign shareholder at 51 percent as of 2020. That is a genuine entry in a government register, which is more than most broker reviews in this catalogue can point to. We also ran the firm’s name against 1,441 warning-list entries mirrored from CYSEC, the FCA and the FSC Mauritius, and it matched none of them. That is a clean result worth stating plainly, and it is a check our earlier review never ran. It only covers those three regulators’ lists, not a global sweep, so treat it as one data point rather than a clearance.
Two other numbers in the site’s own footer, Guangdong ICP Filing No. 17163758 (粤ICP备17163758号) and Guangdong Public Security Network Filing No. 44030502001329 (粤公网安备44030502001329号), are not financial licences at all. They are a website content-provider filing and a public network security filing, the standard registrations any Chinese website carries. They name no financial authority, so there is no register against which to check them, and we have not treated them as evidence of licensing one way or the other.
Why HSBC Qianhai’s fee score is weak
The fee score is low because the pages that would normally carry it, pricing, trading costs, commissions, deposits and withdrawals, were not retrievable across the site paths we probed: several returned empty bodies, 404s, or duplicate shell pages. We have no firsthand HSBC Qianhai fee schedule to quote from, so nothing here should be read as this firm charging little, or charging a lot; it is a gap in what we could fetch, not a finding about the firm’s pricing.
Terms that bind a client
The terms and privacy documents we did read carry real obligations. The site’s own terms state that use of the website is governed by the laws of the People’s Republic of China, and where the Chinese and English texts disagree, the Chinese text controls, a term repeated in the privacy policy for that document too. The firm disclaims responsibility for direct, indirect, special, incidental or consequential loss arising from use of the site, and separately disclaims liability for data or transaction problems caused by communications failures outside its control. The privacy policy states that personal and financial information can be shared across the wider HSBC Group and other third parties, including cross-border transfers, and that in some statutory circumstances this needs no further client consent; it also states that records may be kept for five years, twenty years, or longer depending on the type of document. None of this is unusual for a large group’s boilerplate, but a client relying on the English-language version of either document should know the Chinese text is what actually governs.
Reach and who the site is actually for
The terms state the website is aimed primarily at persons located in mainland China, and the firm does not warrant that the site or its content complies with the laws of other countries. Separately, HSBC Group members reserve the right to decline services based solely on a visitor’s country of residence. Our fetches came from ten countries, each confirmed, yet the content served back was near-identical Chinese-language material in almost every case. A visitor browsing from outside mainland China is not getting a localized offering; they are getting the same mainland-facing site with a disclaimer attached.
Support channels are concrete and checkable rather than generic: a Shenzhen head office and securities business branch, plus branch addresses in Beijing and Shanghai, a general enquiries phone line and email, and a dedicated data privacy hotline with stated weekday hours. That specificity is part of what supports the support score.
What we did not find
An earlier third-party review in our evidence claimed an estimated CN¥6 to 10 million minimum deposit, described the firm as fully CSRC-licensed without qualification, and listed account tiers and platform comparisons. None of those figures appear on any HSBC Qianhai page we fetched, and that same document ends with an unrelated line promoting a different, unconnected broker. We have treated all of it as uncorroborated and left it out of this review entirely.
HSBC Qianhai Securities is a real, CSRC-listed joint venture with a clean result across three warning-list registers, but its own fee, account and platform pages were unreachable in our check, leaving cost and product details unverified; it scores 4.3 out of 10.
What we saw
Pages captured from HSBC Qianhai Securities’s own site when this review was written. Brokers change their terms; these are what we read.





Score history
Recomputed daily; every move is on the record. The current score is always the latest row.
| Date | Score | Move |
|---|---|---|
| 2026-07-25 | 4.3 | = |
| 2026-07-18 | 4.3 | ▲ |
| 2026-07-11 | 4.2 | · |
FAQ
Is HSBC Qianhai Securities regulated for stock trading?
No licence number is shown or claimed on its site. The China Securities Regulatory Commission lists HSBC Qianhai Securities Co., Ltd as a securities company in its 2020 annual report and approved it for margin financing in 2024, and its directory of securities companies dated July 2026 still lists the firm.
What are HSBC Qianhai Securities' trading fees?
No published cost of trading was found on the broker’s own pages or documents.
Does HSBC Qianhai Securities have a mobile trading app?
Yes, it offers its own mobile app.
How can I contact HSBC Qianhai Securities' support?
By email, a published phone number, and published support hours.
Are HSBC Qianhai Securities' footer registration claims proof of a financial licence?
No. The two registrations shown are a website ICP filing and a network-security filing, not financial-services permissions.
How this review works
Track HSBC Qianhai Securities live: score moves and red notices, in your pocket.